Sixth Street Specialty Lending Must Prove Its Activity Rebound Can Lift Flat Earnings
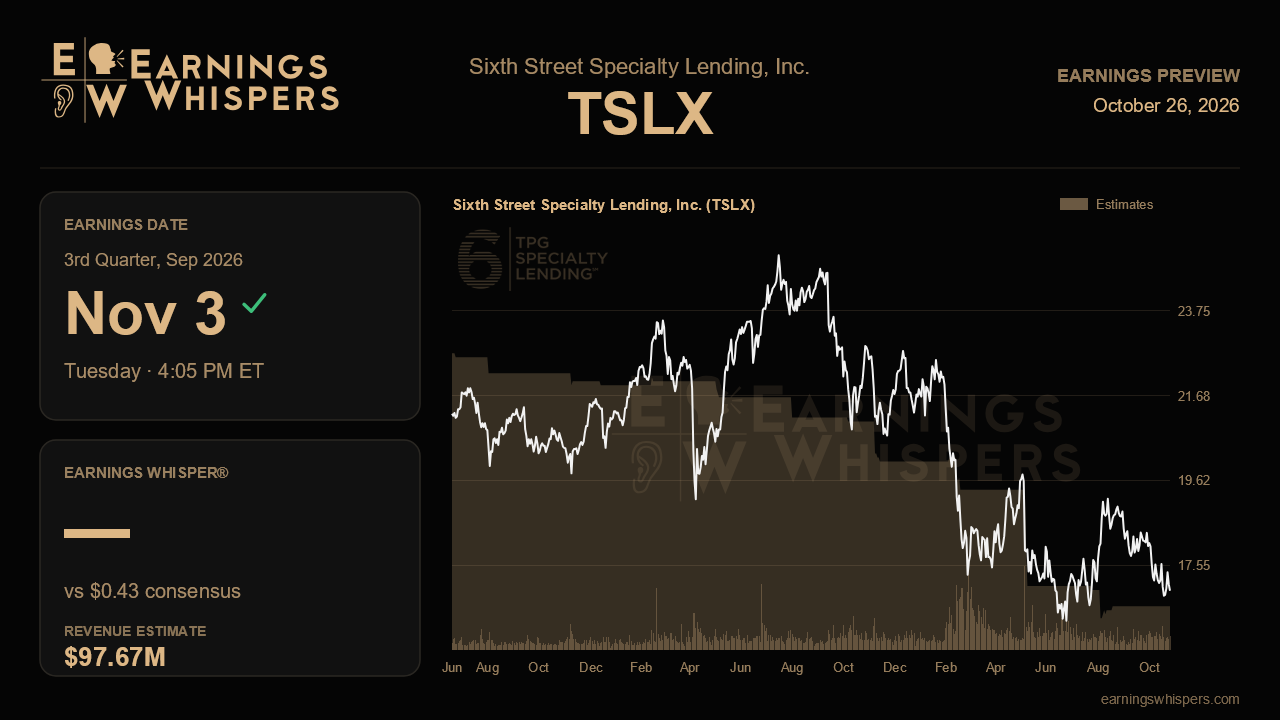
Last quarter Sixth Street Specialty Lending told investors it was approaching an inflection point. Fees were climbing, repayments had surged and the pipeline was accelerating after a sluggish spring. Yet the Street is not pricing in much of that turn. Consensus calls for net investment income of $0.43 a share on revenue of $97.7 million, essentially identical to the prior quarter. When the business development company reports after the close on November 3, the question is whether management's more confident tone starts showing up in the numbers or remains a story about the future.
The year-over-year comparison is unflattering by design. Expected earnings are down about 19% and revenue about 11% from the same quarter last year, when the company earned $0.53 a share on $109.4 million of investment income. That gap reflects a reset that has already happened. Portfolio yield has slipped from 11.7% a year ago to 11.2%, the base dividend was cut to $0.42 from $0.46 earlier this fiscal year, and management's return-on-equity target for the year sits at 10% to 10.5%, below both last year's results and its own original outlook. The real benchmark is sequential: can a company earning a penny above its dividend begin to rebuild that cushion?
The most direct evidence will come from activity-based fees, which rose to $0.08 a share last quarter from $0.05 as repayments jumped roughly 70% to $192 million. Management warned that these fees could take several quarters to normalize, so a flat or slightly higher reading would support the recovery narrative, while a slide back toward first-quarter levels would suggest the second-quarter bounce was episodic. The tricky part is that repayments are a double-edged sword. They generate prepayment fees, but they also shrink the earning asset base unless new lending keeps pace. Direct lending volumes fell about half sequentially last quarter, so originations need to recover if higher turnover is to translate into durable income rather than a one-time lift.
Newer catalysts should also be easier to judge. The structured credit joint venture had called about $154 million of a $200 million commitment by June, with a low-to-mid-teens yield target. Further ramping should add a growing stream of dividend income. The new Shutterfly first-lien loan at SOFR plus 700 basis points, and new-deal spreads around 690 basis points versus roughly 527 for peers, point to pricing discipline that could slow the yield erosion. Management also flagged a forward rate curve roughly 40 to 50 basis points higher than at the prior call, a tailwind for a largely floating-rate book. Holding portfolio yield at 11.2% or nudging it higher would confirm those forces are offsetting the earlier compression.
Credit quality is the other pillar. Non-accruals held at 1.3% of fair value with no new additions, while portfolio company EBITDA growth improved to 11% and interest coverage rose to 2.4 times. Management did caution that dispersion across the market is widening, particularly among software businesses exposed to AI disruption. Any new non-accrual would quickly undercut the constructive tone.
The market has not given much credit for the improvement. Shares are down 3.8% since the last report, trailing the S&P 500 by 2.5 points, and at $16.93 they sit below the 200-day moving average of $18.34 and near the bottom of a post-earnings range of $16.65 to $19.26. Sentiment remains bearish but less so, improving to 31.2% bearish from 43.5% a quarter ago. That combination sets a fairly low bar. The report will hinge on whether fees, joint venture income and steadier yields push earnings meaningfully above the $0.42 dividend, turning management's inflection talk into measurable momentum.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-02 | |
| Aug-05 | |
| Aug-04 | |
| Jul-02 | |
| May-07 | |
| May-05 | |
| May-05 | |
| Apr-24 | |
| Apr-07 | |
| Apr-02 | |
| Mar-17 | |
| Feb-20 | |
| Feb-19 | |
| Feb-13 |
