Sixth Street Specialty Lending Edges Past Estimates On Rate-Driven NII, But Credit Creep And A Stalled M&A Rebound Cloud The Beat
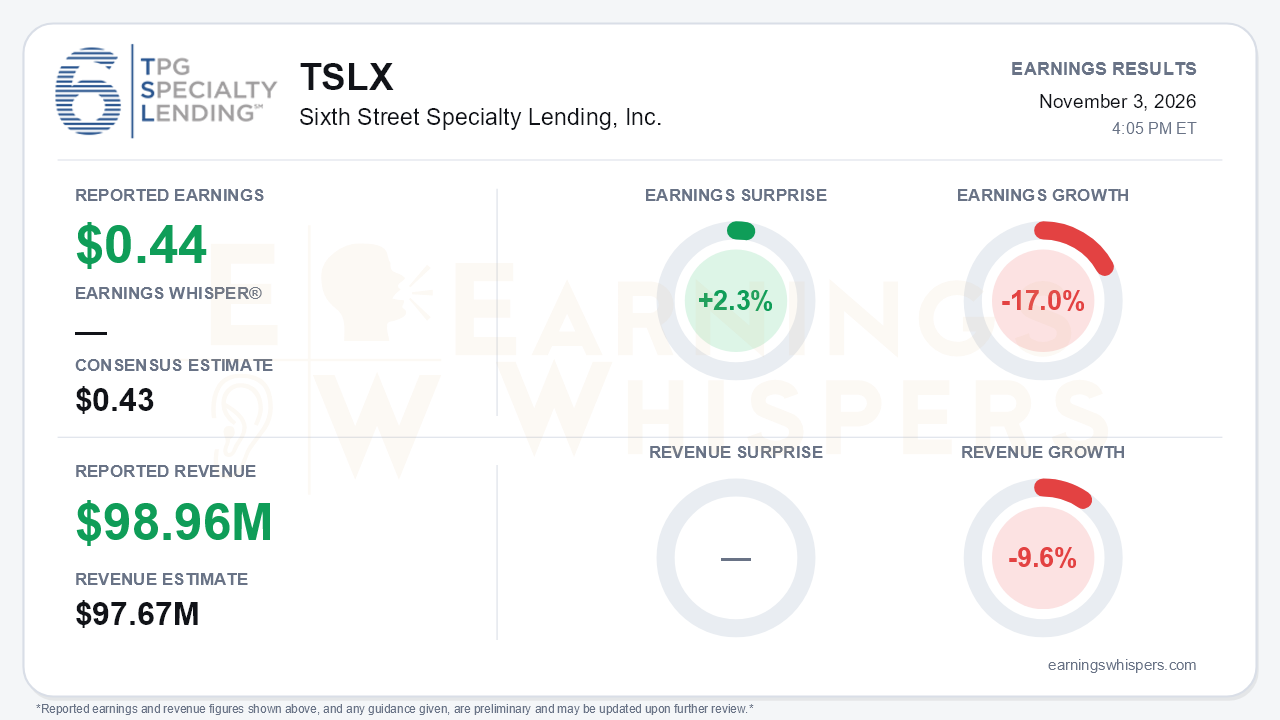
Sixth Street Specialty Lending (NYSE: TSLX) reported third-quarter earnings of $0.44 per share on revenue of $98.96 million. That topped the $0.43 consensus by 2.3%, and revenue beat the $97.67 million estimate by 1.3%. The sequential story is constructive. Net investment income per share rose for a third straight quarter, from $0.42 in Q1 to $0.43 in Q2 and $0.44 now, and covered the reduced $0.42 base dividend at roughly 105%. The year-over-year comparison is much harsher: earnings fell 17.0% and revenue fell 9.6%. That is the central tension. A higher-rate environment is gradually rebuilding earnings power, but off a lower base, and the quarter exposed cracks in credit and deal flow that the modest beat does not capture.
The quality of the beat deserves scrutiny. The headline $0.44 reflects net investment income, but GAAP net income per share fell to $0.36 from $0.43 in Q2. The drag was a $0.10-per-share net realized loss tied to the New Intel/PriceSpider restructuring, which helped push net asset value down to $16.19 from $16.24. On the income side, the gains were real but partly fee-assisted. Total investment income rose to $99.0 million from $97.8 million, while prepayment and other fees climbed to $6.7 million from $5.4 million. Portfolio yield improved to 11.4% from 11.2%. Non-accruals also eased to 1.1% of fair value from 1.3%, an encouraging data point.
Beneath that surface, several underlying credit metrics drifted the wrong way:
- The watch list (risk rating 3) expanded to roughly 5% of the portfolio from about 2%, across four names where management expects covenant defaults.
- The average internal rating slipped to 1.25 from 1.20 in Q2 and 1.19 in Q1.
- Interest coverage edged down to 2.3x from 2.4x.
- Portfolio company EBITDA growth slowed to 9% from 11%.
None of this signals a credit event. But it is a steady deterioration that bears can legitimately point to, especially alongside a NAV decline.
The call also walked back some of the optimism expressed last quarter. The M&A thaw that management framed as an inflection point on the Q2 call did not materialize. PE-backed direct lending volume fell 47% year over year in Q3. Repayments dropped to $160 million from $192 million, and turnover slowed to 19% from 23%. That matters because payoffs drive fee income and redeployment opportunities. Fundings did reach a 2026 high of $247 million, versus $137 million in Q2, and were skewed toward upper-middle-market borrowers at lower leverage. However, new-deal spreads compressed roughly 90 basis points to about 600 bps, so fresh capital is going to work at thinner economics. Leverage of 1.25x sits at the top of the target range, undrawn revolver capacity fell to $812 million, and the company is not issuing equity through its ATM. That combination constrains how aggressively TSLX can grow even if deal flow returns.
Management did offer credible forward catalysts:
- **Rate reset:** The September rate hike and a higher forward curve should lift fourth-quarter earnings through the portfolio's one-quarter reset lag.
- **Deal slippage:** Delayed M&A transactions and payoffs are shifting into Q4.
- **Election clarity:** With election uncertainty now removed, management views early-to-mid 2027 as a potential tailwind.
- **Pricing:** There are early signs of better premiums on complex special-situation deals.
- **Consolidation:** The company is open to accretive BDC consolidation or portfolio purchases.
The return of a $0.01 supplemental dividend signals confidence in near-term coverage. Even so, guidance did not move. The full-year 10%–10.5% ROE target was reaffirmed and remains below the original 11%–11.5% outlook that was cut in Q1.
Investor sentiment remains negative but improved meaningfully, rising to -0.27 from -0.44 at the prior report. Expectations have thawed, though they are far from bullish. Price action has been similarly muted. Shares at $17.90 are up 1.7% since the open following the August report but sit about 1.7% below the 200-day moving average of $18.21. The Earnings Whispers trend readings lean negative, with sequential growth and AVWAP trends still soft while price and momentum are neutral. That fits a stock the market has been reluctant to rerate.
The bottom line is that TSLX delivered a clean but narrow beat built on rising rates, and the near-term earnings trajectory looks supportive heading into Q4. However, a realized loss, a lower NAV, a tripled watch list, compressing spreads and a balance sheet near its leverage ceiling make the setup more complicated than the surprise implies. Higher rates can carry NII for now, but a durable rerating likely requires the M&A recovery management has twice anticipated and credit metrics that stop drifting lower.
Read our earnings preview for Sixth Street Specialty Lending, Inc.: https://www.earningswhispers.com/article/TSLX/21641
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-03 | |
| Oct-26 | |
| Oct-02 | |
| Aug-05 | |
| Aug-04 | |
| Jul-02 | |
| May-07 | |
| May-05 | |
| May-05 | |
| Apr-24 | |
| Apr-07 | |
| Apr-02 | |
| Mar-17 | |
| Feb-20 |
