Hecla's Delayed Greens Creek Shipments Set Up A Revenue Test As Shares Slide Toward Lows
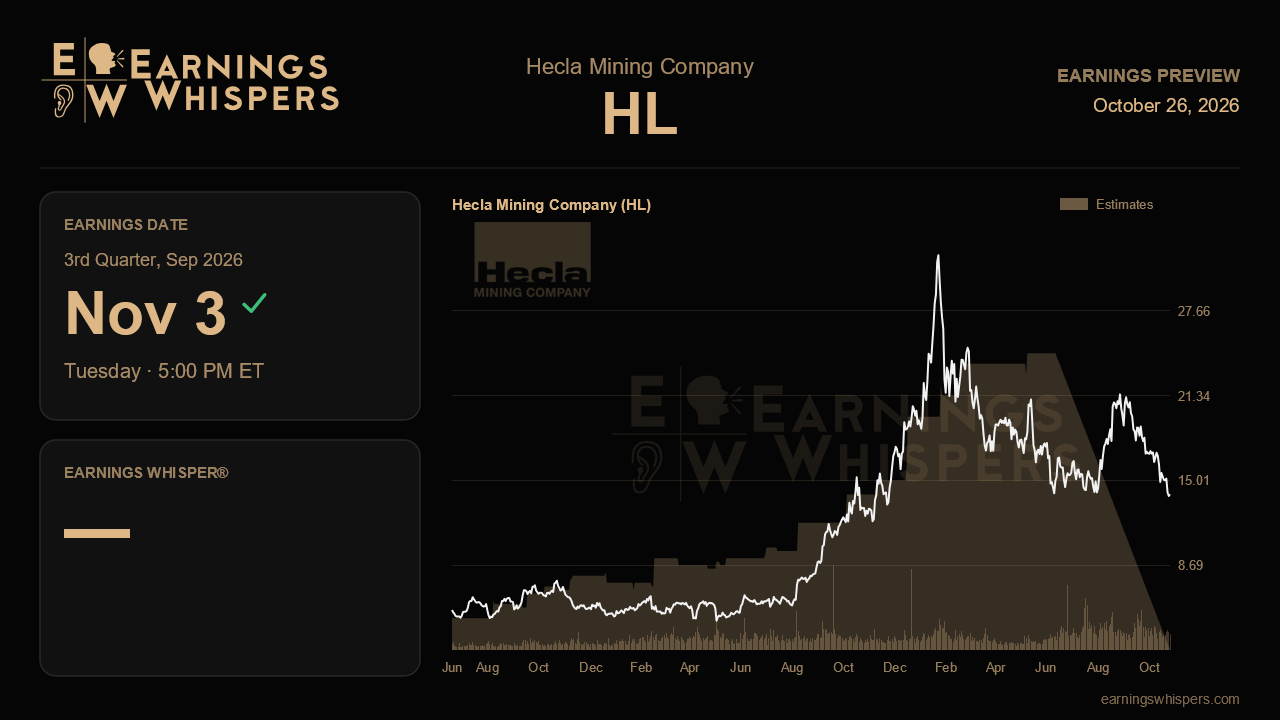
Hecla Mining enters its third-quarter report with an unusual setup: its operations have arguably never looked better, but its stock has rarely felt worse. Last quarter management raised guidance at both flagship silver mines, posted record site-level cash flow and reported the strongest balance sheet in company history. Since then, the shares have fallen about 15%, trailing the S&P 500 by nearly 14 percentage points. The November 3 release, due after the close, needs to show whether that disconnect reflects lower metal prices or something the market fears is starting to crack.
The most mechanical part of the story is revenue timing. Second-quarter sales fell to $333.9 million from a record $411 million in the first quarter. Management blamed two things: a pullback in metal prices and a meaningful batch of Greens Creek concentrate that was produced but not sold before quarter-end. That material shipped in early August, so it should land in third-quarter revenue. A clear rebound toward the level of a year ago, when revenue reached $409.5 million, would support management's view that the second-quarter dip was a timing quirk rather than a production problem. If revenue stays near second-quarter levels, the timing explanation gets harder to accept, and the drag from metal prices starts to look larger than the company suggested. The year-ago quarter earned $0.12 a share against $0.17 last quarter, so a modest improvement would be consistent with the operating trend.
The guidance raises create a higher bar. Greens Creek is now expected to produce 8.0 to 8.3 million ounces of silver this year, with byproduct credits large enough to push cash costs well below zero. Lucky Friday was tightened toward 4.9 to 5.2 million ounces after a record 1.5 million ounce quarter. After raising those ranges in July, management will be expected to show that both mines are tracking at least to the midpoint. Any further upward revision would extend the momentum. A quiet reaffirmation would be fine. A step back at either mine would undercut the central argument behind the more confident tone. At Lucky Friday, also check that higher sustaining capital keeps all-in costs inside the newly raised $20.50 to $26 range.
Keno Hill remains the weak link. Its 2026 silver outlook was cut to 2.2 to 2.6 million ounces, and the meaningful tonnage ramp was pushed to around the end of 2029, pending permits targeted for mid-2029. Another cut would suggest the Yukon asset is still drifting. Steady output with continued drilling success along the extended high-grade trend would help restore some confidence that the delay is about sequencing, not geology.
Cash generation is the other test. Free cash flow was $136 million last quarter, close to the first-quarter record, but management flagged heavier second-half capital spending and lowered its cash flow sensitivity to reflect weaker prices. Some compression is therefore expected. The key question is whether the roughly $472 million net cash position holds up as Hecla shifts from paying down debt to investing in projects such as the Greens Creek pyrite concentrate circuit. That project is budgeted at $40 million to $60 million and targeted for first production between late 2027 and early 2028.
Sentiment is mildly bearish and only slightly less so than before the last report. The stock, at $13.98, sits just above its post-earnings low of $13.50 and far below its 200-day moving average of $18.85. That leaves room for relief if the report confirms the story, but also little technical support if it does not. Ultimately, the report hinges on one question: can the recovered Greens Creek sales and strong flagship costs show that Hecla's margin engine is intact despite softer prices and a slower Keno Hill?
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-26 | |
| Oct-13 | |
| Oct-09 | |
| Sep-24 | |
| Sep-17 | |
| Sep-16 | |
| Sep-16 | |
| Aug-26 | |
| Aug-26 | |
| Aug-20 | |
| Aug-14 | |
| Aug-13 | |
| Aug-10 | |
| Aug-05 |
