Hecla Posts Record Free Cash Flow And Better Cost Guidance, But A Multi-Year Keno Hill Curtailment Clouds The Growth Story
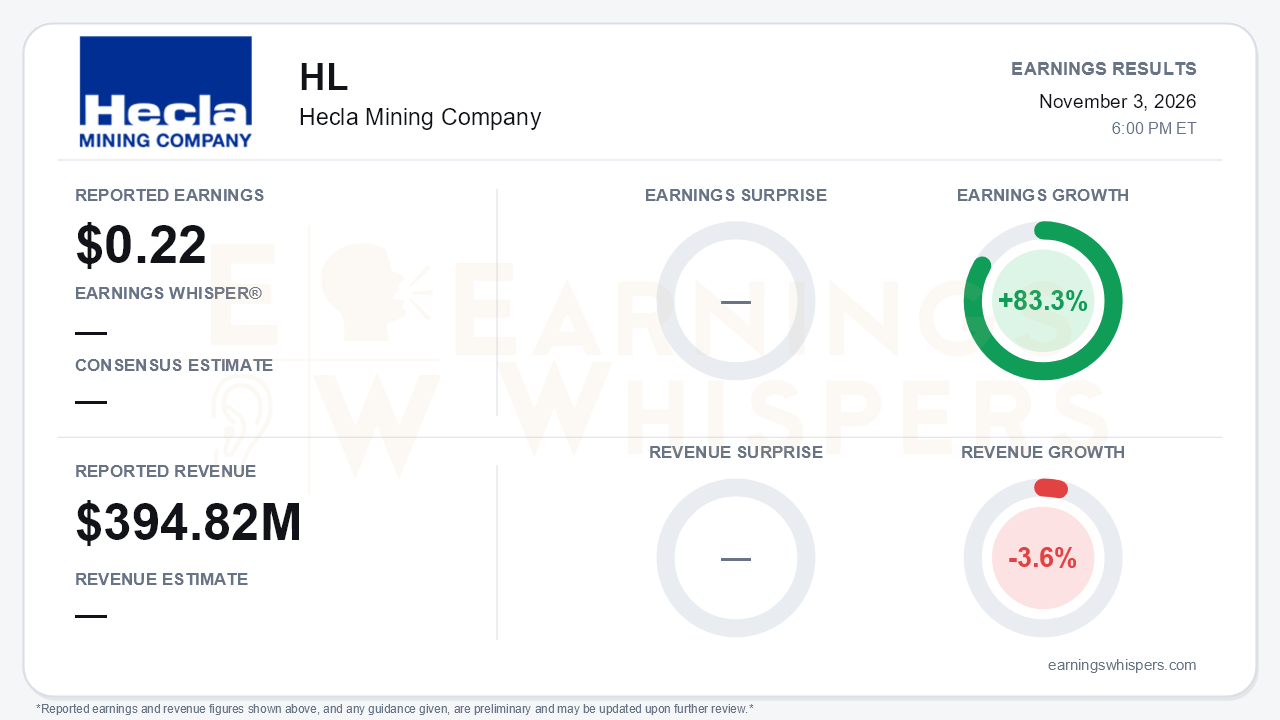
Hecla Mining's third quarter had two stories that pull against each other. The company earned $0.22 per share from continuing operations, up 83.3% from a year ago. It produced record free cash flow of $151 million, and it improved full-year cost guidance for the second straight quarter. In the same release, management disclosed a deliberate, multi-year throttling of Keno Hill, the asset that was supposed to be Hecla's next leg of growth. That is the central tension. The cash machine at Greens Creek is stronger than ever, while the production-growth narrative investors were underwriting at Keno Hill has been pushed out by years.
The headline numbers deserve some scrutiny. Revenue of $394.8 million fell 3.6% year over year on Earnings Whispers' normalized basis. The company's recast continuing-operations table, which excludes the divested Casa Berardi, shows year-ago sales of $316 million, so the comparison depends heavily on the basis used.
Sequentially, sales rose 18%. That gain came mostly from shipment timing at Greens Creek, where silver concentrate sold far exceeded concentrate produced as the Q2 backlog shipped. Earnings quality was also helped by a $26.7 million fair-value gain, mostly on marketable securities, which compared with a $9.2 million loss in Q2. Operating income rose only about 8% sequentially, and adjusted EBITDA rose 6%. Underlying production was not the driver. Silver output was flat at 4.2 million ounces, and year-to-date production of 12.3 million ounces trails last year's 13.2 million.
Unit costs moved the wrong way during the quarter. Consolidated AISC jumped to $14.34 per ounce from $6.07 in Q2, for three reasons:
- Greens Creek ran more maintenance than planned.
- Lucky Friday moved out of the high-grade pocket that drove its Q2 record.
- By-product credits fell $14 million on lower gold output.
The call framed the per-ounce margin as 77% of the realized silver price, down from 90% in the first half. Yet the full-year guide improved. Consolidated cash costs are now guided to negative $4.75 to negative $4.25 per ounce, AISC to $11.50 to $12.50, and capital spending was trimmed to $198 to $214 million. Management is effectively saying that the first nine months banked enough outperformance to absorb a softer Q3 and a heavier Q4 maintenance schedule at Greens Creek. That maintenance work extends into 2027.
Keno Hill is where the setup changed most. The mine actually set a production record of 963,000 ounces, with milled grade up 36%. Even so, throughput will drop to roughly 300 tons per day in Q4 and fall further from January 2027. The aim is to stretch about 200,000 tons of remaining permitted tailings capacity until license amendments arrive, currently estimated around mid-2029. Management stressed this is not a cost-driven decision. On the call, however, it acknowledged that commercial production slips to late this decade or early next, and that care and maintenance is not ruled out if permits slip or silver weakens. Keno Hill free cash flow already turned negative, at minus $2 million, after five positive quarters. It follows a Q2 cut to Keno Hill production guidance.
The offsets are real but mostly longer-dated:
- **Pyrite concentrate circuit at Greens Creek.** It could add 1.0 to 1.2 million ounces of silver and 10,000 to 15,000 ounces of gold annually. An accelerated path targets intermittent output in late 2027, subject to permits and final approval.
- **Dry-stack tailings.** The tailings reprocessing effort now has three possible pathways, including a 5,500-tonne trial shipment to a smelter. The dry-stack pile holds an estimated 51 million ounces of silver, though this material is explicitly not a resource.
- **Balance sheet and capital returns.** Hecla holds $692 million of cash, no debt beyond finance leases, a new $500 million revolver and about $1.2 billion of liquidity. Management said capital returns will get a serious board discussion in the first half of 2027.
The market has not been rewarding the cash story. Shares closed at $13.21, down 19.8% from the $16.47 open after the August report. They sit nearly 29% below the 200-day moving average of $18.57. Part of that decline tracks the metal itself: average London silver fell to $62.73 in Q3 from $73.44 in Q2 and $84.39 in Q1. Earnings Whispers trend readings are mixed, with price and AVWAP trends negative even as momentum has turned positive. Investor sentiment remained negative and slipped marginally, from -0.376 to -0.390. This report did not shift expectations so much as reinforce existing caution.
The bottom line is that Hecla delivered a high-quality cash quarter and a credible cost outlook, but the headline earnings growth leaned on shipment timing and investment gains rather than rising production. Bulls can point to record free cash flow, a fortress balance sheet and the prospect of capital returns. Bears have legitimate ammunition in flat output, a sharp sequential AISC increase, falling silver prices and a Keno Hill growth plan now deferred toward 2029 or later. Until the pyrite circuit or tailings options move from concept to approved projects, Hecla is primarily a Greens Creek cash-flow story with a growth gap.
Read our earnings preview for Hecla Mining Company: https://www.earningswhispers.com/article/HL/21659
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| Nov-03 | |
| Nov-03 | |
| Oct-26 | |
| Oct-26 | |
| Oct-13 | |
| Oct-09 | |
| Sep-24 | |
| Sep-17 | |
| Sep-16 | |
| Sep-16 | |
| Aug-26 | |
| Aug-26 | |
| Aug-20 | |
| Aug-14 |
