Northwest Bancshares Matches Consensus But Misses The Whisper As Margin Streak Snaps And Costs Drift Higher
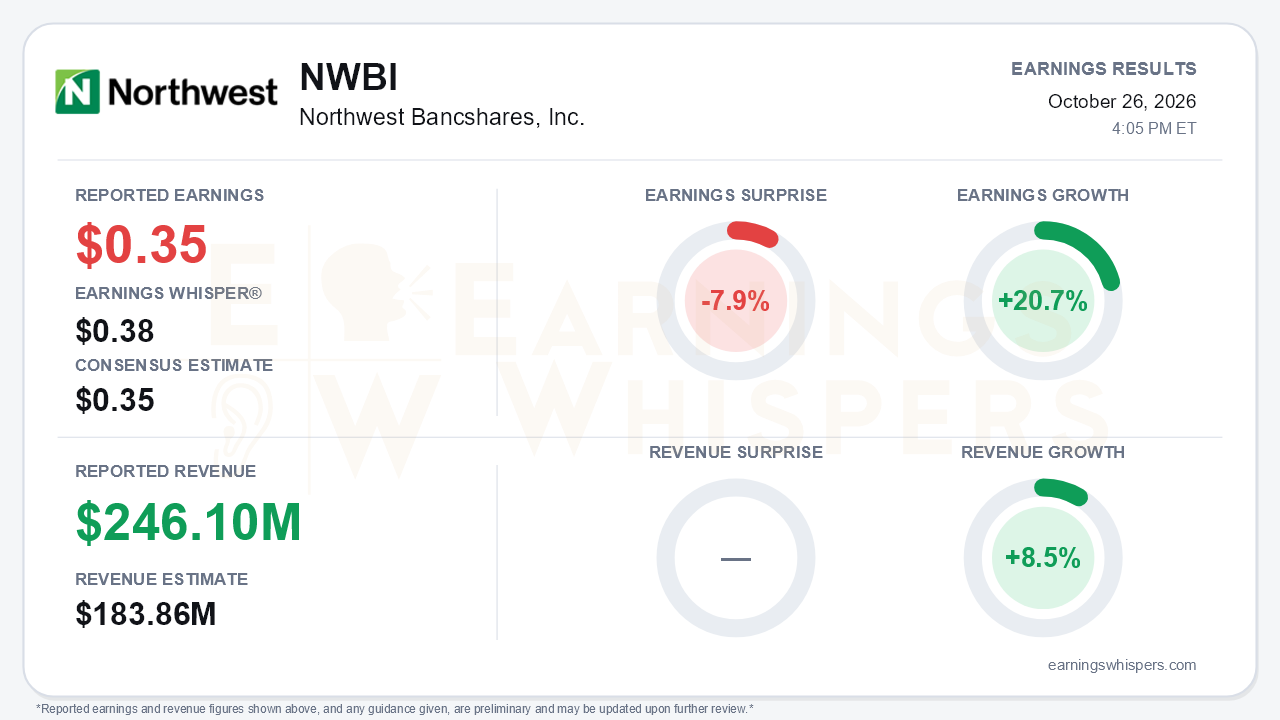
Northwest Bancshares (NASDAQ: NWBI) reported third-quarter adjusted earnings of $0.35 per share, in line with the $0.35 consensus but 7.9% short of the $0.38 Earnings Whisper number. Earnings grew 20.7% from a year earlier. The year-ago comparison is flattered, though: GAAP EPS was just $0.02 last year, weighed down by $31 million of Penns Woods merger costs and a $20.6 million Day 1 credit provision. Adjusted EPS was $0.29. The sequential picture matters more, and it went the wrong way. Adjusted EPS slipped from $0.37 in the second quarter and GAAP EPS fell from $0.36 to $0.34. That is the central tension of the quarter. Northwest produced record revenue and lifted several guidance metrics, yet earnings per share declined because the margin stalled and expenses rose.
The revenue line needs context. Earnings Whispers puts revenue at $246.1 million, 33.9% above the $183.86 million consensus and up 8.5% year over year. That figure, however, sits on a gross basis that includes total interest income. The company's own measure is net interest income plus fee income, which came to a record roughly $185 million, up about 2% sequentially and 9.9% year over year. On that basis the top line was solid but essentially in line with expectations. The apparent blowout is mostly a definitional gap, not a sign of demand far above forecasts. Net interest income reached a record $149 million, but it rose only $2 million sequentially because the net interest margin compressed 5 basis points to 3.70%. That ended four straight quarters of margin expansion. Several forces drove the compression:
- Average borrowings jumped $238 million as loan and securities growth outran deposits.
- Purchase-accounting accretion faded.
- Deposit costs ticked up a basis point to 1.44%, the first increase in four quarters.
The operating story beneath the headline remains constructive. Average commercial and industrial (C&I) loans grew $201 million sequentially and roughly 31% year over year, an acceleration from the second quarter's $148 million gain. National specialty verticals now make up about 30% of the commercial book, up from 23% in the first quarter. The mix shift is deliberate. Commercial real estate (CRE) balances have fallen from $3.50 billion a year ago to $2.93 billion, and management now expects the net decline to shrink or turn positive within one to two quarters. Fee income grew 11.6% year over year, led by a 25.7% jump in trust and wealth revenue. Guidance moved in two directions:
- **Raised:** revenue to the high end of the $710-730 million range, fee income to above the high end of $125-130 million, and net charge-offs to the low end of 20-27 basis points.
- **Cut or pushed higher:** full-year margin trimmed to 3.71% from 3.73-3.75%, and noninterest expense moved to the high end of the $420-430 million range, implying a roughly $109 million quarterly run rate as the Columbus build-out ramps.
The forward catalysts are real but carry conditions. Management guided the fourth-quarter margin to 3.73%. Its reasoning is that the asset-sensitive balance sheet benefits from the September rate hike and the late-quarter redemption of $114.8 million of subordinated debt adds about 2 basis points. Management also flagged a $50 million buyback authorization likely entering the mix in 2027, a new efficiency review and additional Columbus branches. Bears have legitimate ammunition, however:
- **Rate exposure in the securities book:** the accumulated other comprehensive loss widened from $83 million to $142 million, pushing tangible book value down to $9.65 from $9.88 and tangible common equity to 8.40%. The same rate environment that helps the margin is hurting book value.
- **C&I credit:** headline credit still looks clean, with 0.15% annualized net charge-offs and classified loans down to 3.50% of loans. But C&I nonaccruals rose from $22 million to $34.5 million, and 60-89 day C&I delinquencies nearly quadrupled to $22.7 million. Nonperforming loans edged up to 0.74%. That warrants monitoring given how quickly the C&I book is growing.
- **Competition:** management cited loan pricing pressure, with origination yields in the low-to-mid 6% range, and deposit competition in new markets.
Investor sentiment shifted noticeably. It swung from a modestly positive 0.18 at the prior report to a mildly negative -0.11. That suggests the market had positioned for a cleaner beat than the in-line result delivered. Price action has been muted rather than punishing. Shares are down 2.1% since the opening after the July report but remain about 9.9% above the 200-day moving average of $14.13. Earnings Whispers momentum and AVWAP trend readings remain positive, consistent with a stock that has consolidated gains rather than broken down. The dividend yield of roughly 5.4% continues to anchor the income case.
The bottom line is that Northwest delivered a quarter of good franchise momentum and soft per-share earnings. C&I growth, fee expansion, benign charge-offs and raised revenue guidance support the strategic repositioning away from CRE. But the broken margin streak, higher expense guidance and an EPS step-down explain why a consensus match registered as a whisper miss. The fourth quarter now carries the burden of proof. The guided margin rebound to 3.73% must materialize while expenses hold near the $109 million run rate and early C&I delinquency signs stay contained.
Read our earnings preview for Northwest Bancshares, Inc.: https://www.earningswhispers.com/article/NWBI/20662
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-26 | |
| Oct-26 | |
| Oct-22 | |
| Oct-08 | |
| Oct-05 | |
| Sep-10 | |
| Sep-01 | |
| Aug-25 | |
| Aug-17 | |
| Jul-30 | |
| Jul-29 | |
| Jul-27 | |
| Jul-27 | |
| Jul-16 |
