Trivago's Q3 Report Tests Whether Its Margin Story Can Outrun A 27% Stock Slide
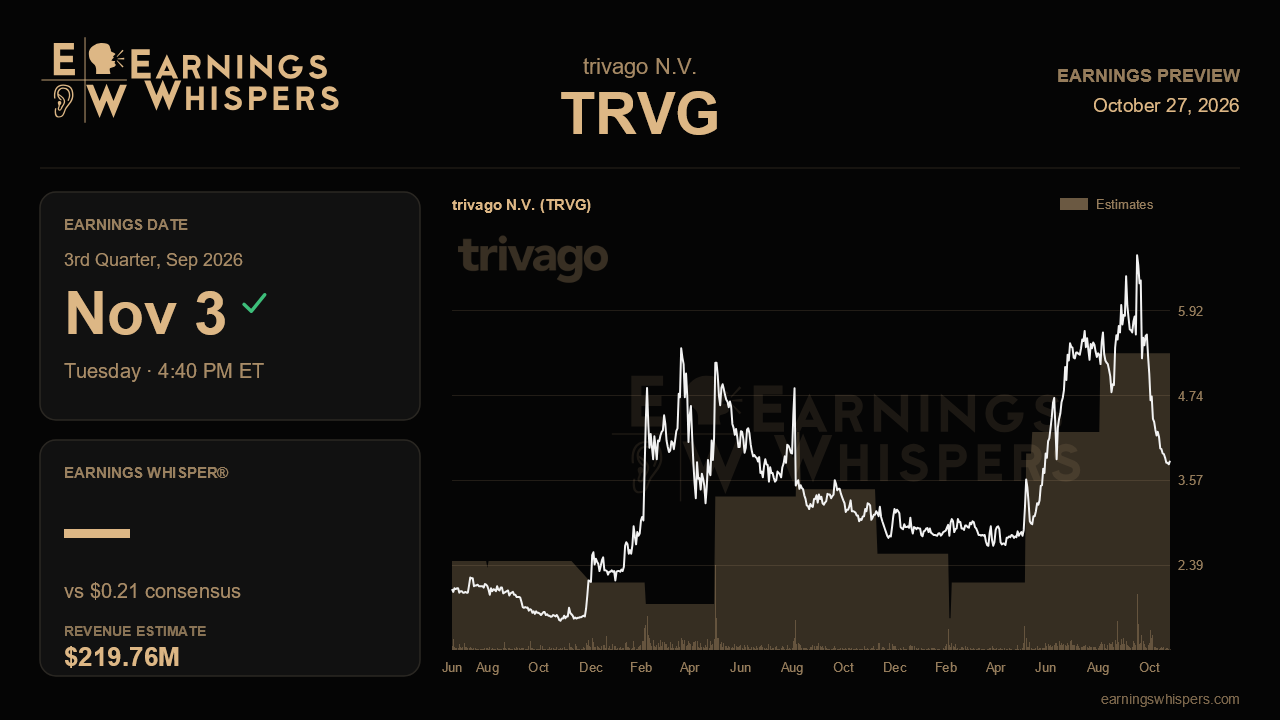
Trivago heads into its third-quarter report with an odd disconnect. The company has spent most of a year telling a steadily improving story, raising its full-year adjusted EBITDA target three times and, last quarter, putting a firm 2028 date on its goal of a 10% adjusted EBITDA margin. The stock has gone the other way. Shares have fallen about 27% since the August report while the S&P 500 slipped less than 2%. The November 3 release, due after the close, is the market's next chance to decide which story to believe.
The Street is looking for earnings of $0.21 per share on revenue of roughly $219.8 million. Revenue at that level would be about 13.5% growth over the year-ago quarter's $193.5 million. That is solid, though a step down from the 21% pace posted in the second quarter. The expected jump in EPS from $0.04 a year ago looks dramatic in percentage terms, but it mostly reflects a small base. The real point is that the third quarter is the seasonal peak for hotel search, so this is the quarter where trivago's operating leverage either shows up in full or does not. Management's raised guidance calls for mid-teens revenue growth for the year and about €30 million of adjusted EBITDA, up from €25 million a quarter earlier and €20 million before that. With the first half producing only a modest positive figure after a first-quarter loss of €4.5 million, a large share of that annual target has to come from the summer months. A consensus revenue figure in the low teens sits comfortably within a mid-teens annual framework, but it leaves little room for a slowdown if the full-year EBITDA number is going to hold.
The second-quarter call laid out the drivers that need to keep working. Conversion has improved by 64% since 2023, and that is what lets trivago earn more from each marketing euro. Global return on ad spend edged up to 121.8%, although developed Europe slipped slightly as the company spent more on its brand. Investors should want to see that brand spending pay off in referral volume without further erosion in efficiency. The newer catalysts deserve close scrutiny too. Book & Go, the on-platform booking product, roughly tripled its share and recently added Expedia as a supply partner. The CRM and owned-media channel more than doubled its revenue at structurally better margins. If either keeps scaling, it supports the case that margin expansion is structural rather than a one-off from cost timing.
The main soft spot is the rest-of-world segment. Referral revenue there fell 11% last quarter after a 12% drop before that, hurt by currency headwinds of about 7% and pressure from the Middle East conflict, including airspace restrictions and higher oil prices. That segment is only 18% of referral revenue, so it is contained, but further deterioration during peak travel season would chip away at the growth rate. The EU's €890 million fine against Google for self-preferencing, which specifically named hotels, is a longer-term tailwind. Any commentary on how remedies are being implemented will matter more for sentiment than for this quarter's numbers.
Sentiment has cooled noticeably, with bullish readings falling to about 15.9% from 33.8% ahead of the last report. At $3.84 the stock trades below its 200-day average near $4.03 and sits just above the $3.70 low of its post-earnings range, far from the $6.80 high. Expectations, in other words, look subdued relative to the guidance management has put on the table.
That makes the question fairly simple. Trivago needs to show that peak-season revenue converted into the kind of EBITDA that keeps the €30 million target, and the 2028 margin goal, credible. A reaffirmation or another raise, backed by continued conversion gains and Book & Go traction, would challenge the market's skepticism. A trimmed outlook, or evidence that the rest-of-world drag is spreading, would suggest the selloff was early rather than excessive.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-27 | |
| Sep-04 | |
| Sep-04 | |
| Sep-04 | |
| Sep-04 | |
| Sep-04 | |
| Aug-14 | |
| Aug-05 | |
| Aug-04 | |
| Jul-27 | |
| Jun-29 | |
| Jun-11 | |
| May-05 | |
| May-05 |
