Trivago Misses Badly On EPS But Delivers Its Best Adjusted EBITDA Since 2023 And A 45 Million 2027 Target, While Growth Slows
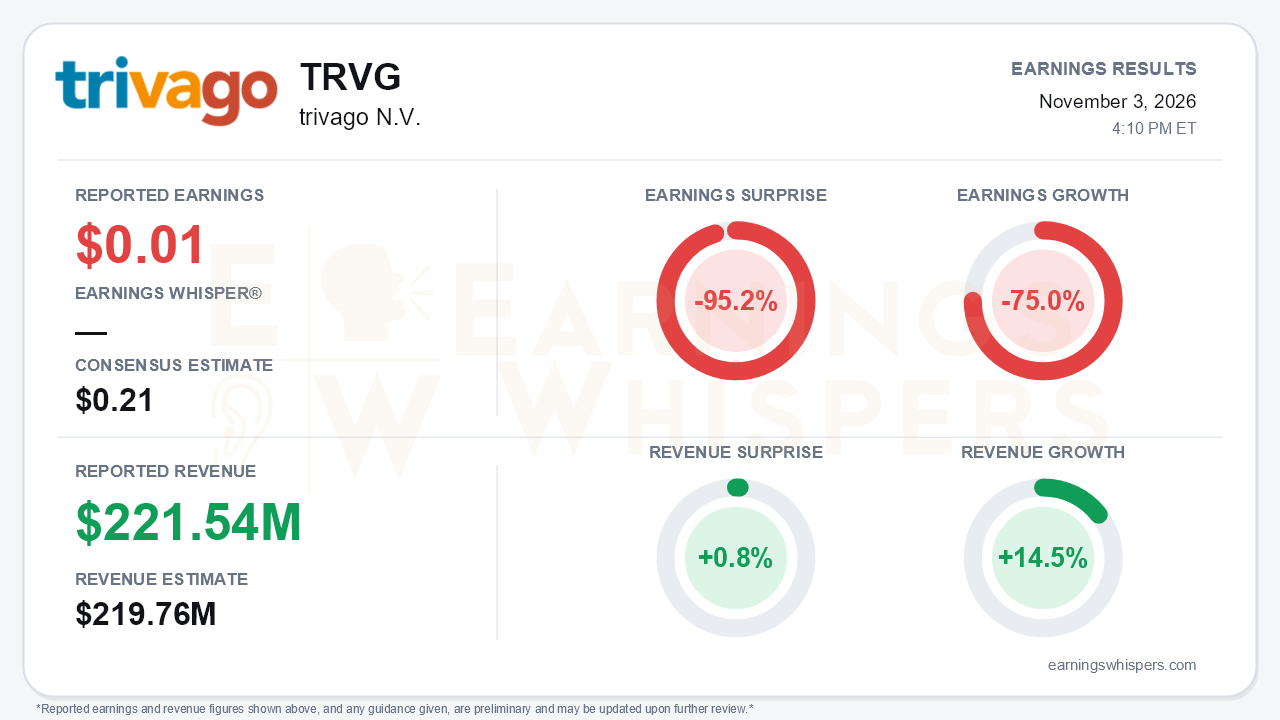
trivago's third quarter looks different depending on which line you read. On the bottom line, the company reported earnings of $0.01 per share against a consensus estimate of $0.21, a 95.2% miss, and earnings fell 75.0% from a year ago. On the top line, revenue of $221.54 million beat the $219.76 million consensus by 0.8% and grew 14.5% year over year in dollar terms. In euros, the company reported 16% growth to €192.5 million. Operationally, the quarter was trivago's strongest since management returned in mid-2023: adjusted EBITDA reached €18.7 million, up 17%. The central tension is that the profit-generating engine is improving while GAAP earnings are being diluted by non-operating and below-the-line items, and topline growth is clearly cooling.
The EPS miss deserves scrutiny rather than dismissal. Net income fell to €5.4 million from €11.0 million, and most of that decline came from items outside the core marketplace:
- **Gain not repeated:** last year's quarter included a €3.2 million gain tied to the trivago DEALS acquisition.
- **Higher share-based compensation:** it rose to €4.9 million from €2.0 million, with €2.8 million of the increase from options granted to the DEALS founders.
- **Abandoned deal costs:** €1.3 million in advisory costs for a potential corporate transaction that was not completed.
- **Tax rate:** the effective tax rate jumped to 50.6% from 28.7%, partly because share-based compensation is not deductible.
These are real costs to shareholders, not accounting noise. Even so, they say less about demand than the headline miss suggests. Operating income slipped to €10.1 million from €12.2 million as technology and G&A costs grew 31% and 40%, respectively.
The operating trends beneath the revenue line are mixed:
- **Growth is slowing.** Total growth decelerated to 16% from 21% in the second quarter. Organic Referral Revenue grew only 10%; the gap is filled by DEALS, which contributed €14.0 million versus €3.2 million a year ago, almost entirely because of acquisition timing.
- **Developed Europe is the bright spot.** Referral growth accelerated slightly to 15% from 14%, and ROAS improved to 142.0%, suggesting compounding returns from earlier brand investment.
- **The Americas are the soft spot.** Referral growth eased to 15% from 16% in Q2 and 17% in Q1. Management raised advertising spend there 23%, and segment ROAS fell to 129.0% from 135.4%. Management expects returns on that spend to follow, but that is a forecast, not a result.
- **Rest of World is still shrinking but stabilizing.** Revenue fell 10%, extending a moderating trend from -12% and -11% in the first two quarters, with FX and the Middle East conflict still weighing.
Several structural metrics argue the business is becoming more resilient:
- **More direct traffic:** logged-in members now account for more than 35% of Referral Revenue, up from above 30% earlier in the year, and branded traffic grew faster than total traffic.
- **Less advertiser concentration:** Booking Holdings' share of Referral Revenue fell to 38% from 44%, Expedia's fell to 27% from 30%, and all other advertisers rose to 35% from 26%.
- **New distribution channels:** management highlighted joining OpenAI's paid ads program and renewed growth in AI-referred revenue, though that revenue remains well below 1%. It also pointed to Google's DMA-driven search changes in Europe, while acknowledging no measurable impact yet and that Google remains not fully compliant.
Guidance was the clearest positive. Management held its full-year 2026 outlook of mid-teens revenue growth and roughly €30 million of adjusted EBITDA, a target already raised twice this year. It also introduced a 2027 outlook of double-digit revenue growth and about €45 million of adjusted EBITDA, keeping the 10% margin target for 2028 in view. Bears have legitimate ammunition, though. A "double-digit" 2027 growth rate implies slowing from 2026's mid-teens pace, and management flagged a tough fourth-quarter comparison against 27% growth a year ago. The investment case is shifting from growth acceleration to margin delivery.
The market had already turned skeptical before this report. Shares have fallen 33.2% since opening at $5.27 after the August release, despite that release raising guidance. They now sit at $3.52, about 13% below the 200-day moving average of $4.06. Investor sentiment weakened meaningfully, falling from 0.34 to 0.07 and leaving it only barely positive. The internal trend readings are mixed: momentum is positive while AVWAP remains negative, which fits a stock whose fundamental narrative has outpaced its price action.
The bottom line is that trivago produced a headline EPS miss that overstates the deterioration in the core business, but not one investors can wave away. Rising share-based compensation, abandoned deal costs and a heavy tax rate are diluting real profit even as adjusted EBITDA hits multi-year highs. The call preserved a credible profitability story, anchored by a €45 million 2027 target, but it also confirmed that topline growth is normalizing and that the Americas spending push has yet to pay off. With the stock down a third since August and sentiment nearly neutral, the burden now falls on management to show those margin gains reaching GAAP earnings.
Read our earnings preview for trivago N.V.: https://www.earningswhispers.com/article/TRVG/21666
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-03 | |
| Oct-27 | |
| Oct-27 | |
| Sep-04 | |
| Sep-04 | |
| Sep-04 | |
| Sep-04 | |
| Sep-04 | |
| Aug-14 | |
| Aug-05 | |
| Aug-04 | |
| Jul-27 | |
| Jun-29 | |
| Jun-11 |
