Compass Pathways Earnings Hinge On FDA Review Progress And DEA Rescheduling Path For Comp360
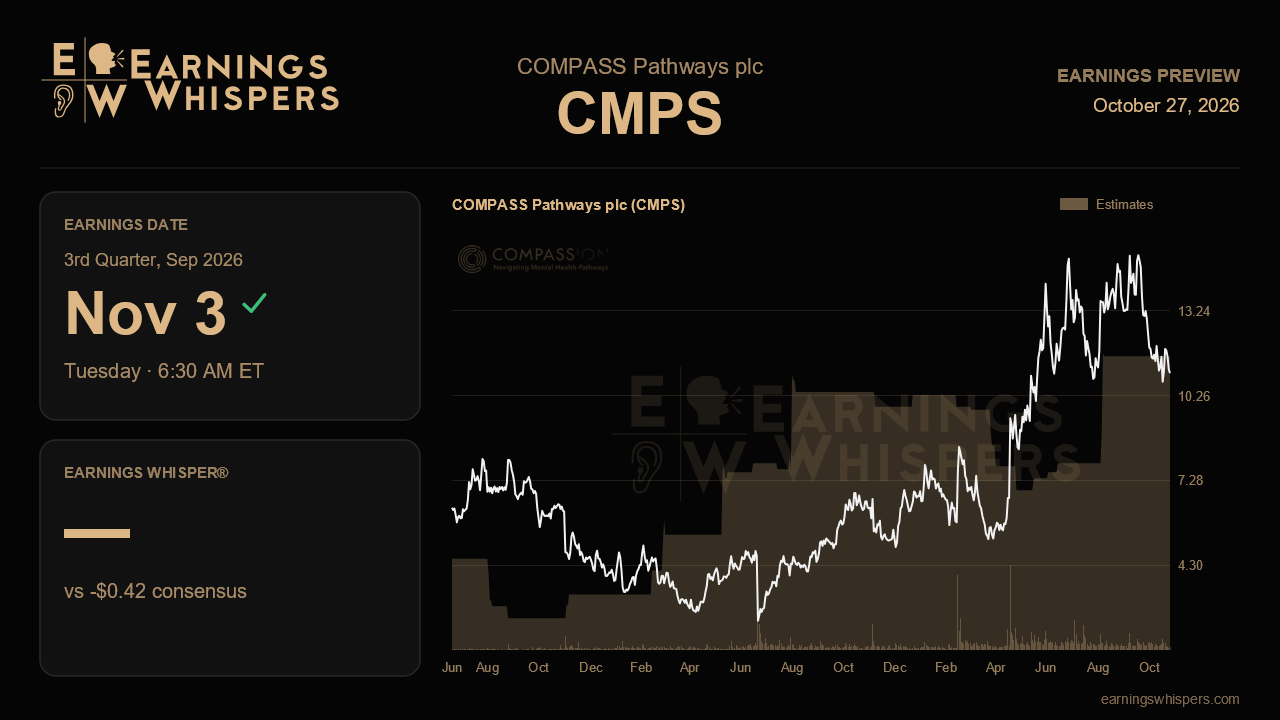
For a company with no product revenue, Compass Pathways heads into its third-quarter report carrying an unusual amount of narrative weight. Over the past year management has assembled what it describes as a largely de-risked package for Comp360, its psilocybin treatment for treatment-resistant depression. That package includes two positive Phase 3 trials, 26-week durability data and a rolling new drug application that the FDA is already reviewing. Yet the August call also moved the practical launch window into the first half of 2027, and management explicitly called that timeline fluid. The November 3 release, due before the open, is less about the loss per share than about whether the path from approval to availability is getting clearer or murkier.
The Street expects a loss of $0.42 per share, wider than the $0.36 loss last quarter and the $0.38 loss a year ago. That roughly 10.5% deterioration year over year is exactly what a company should look like when it is staffing up for a launch. Compass has hired a commercial leadership team with experience across roughly 70 launches at J&J, Gilead, Otsuka and Axsome, and it has begun recruiting a field force. It has also restarted investigator-initiated studies and is enrolling a 300-patient PTSD Phase 3 trial. A wider loss would therefore be consistent with the plan. A materially smaller loss might even raise questions about whether launch spending is being paced more cautiously. Management has not issued formal financial guidance. The balance sheet is the relevant anchor instead: $433 million in cash at the end of June, which the company said funds operations into 2028. Any revision to that runway would matter more than a few cents on EPS.
The regulatory update is the real test. Last quarter's confidence rested on the rolling NDA being underway and on the Commissioner's National Priority Voucher, which could compress the review to one or two months. The most validating news would be confirmation that the submission is complete and accepted, with a clearer sense of when a decision could land. The other half of the equation is rescheduling. Federal DEA action, which carries a roughly 90-day process, and state-level changes are what separate an approval from a product doctors can actually use. Concrete engagement or timelines there would support the first-half 2027 target. Further hedging, or any hint that the window is slipping again, would challenge it. The new final FDA guidance on psychedelics, which references 12-month blinded durability, is another item to monitor. Management called that bar a tall order but said it does not affect the current review. Any change in that stance would be significant.
Commercial readiness metrics offer a secondary check. Interventional psychiatry sites topped 8,000 last quarter and have been growing by about 500 per quarter. Strategic collaborations reached eight with the addition of Radial and Osmind. Roughly 90% of surveyed interventional psychiatrists said they would prescribe within the first year. Continued site growth at that pace, along with more payer or delivery partnerships, would show the infrastructure is keeping up with the regulatory timeline.
Sentiment has swung noticeably, from bearish going into the last report to modestly bullish now. The stock has not followed. Shares are down 4.7% since August, trailing the S&P 500 by about 3.4 points. At $11.05 they sit near the bottom of a post-earnings range of $10.72 to $15.87, though still above the 200-day average of $10.29. That pattern suggests the market has priced in some timing risk despite the improving clinical story.
Ultimately, the quarter comes down to one question: can management turn a fluid launch window into a credible schedule? Evidence that the FDA review and DEA rescheduling are converging toward early 2027 would keep the de-risking narrative intact. Another round of vague timing would hand the skeptics their argument.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 5 hours | |
| 11 hours | |
| Oct-14 | |
| Oct-02 | |
| Sep-30 | |
| Sep-16 | |
| Sep-15 | |
| Sep-10 | |
| Sep-10 | |
| Sep-10 | |
| Sep-09 | |
| Sep-09 | |
| Sep-09 | |
| Sep-09 | |
| Sep-09 |
