BioCryst Must Prove Orladeo Can Carry The Load Without A License Windfall
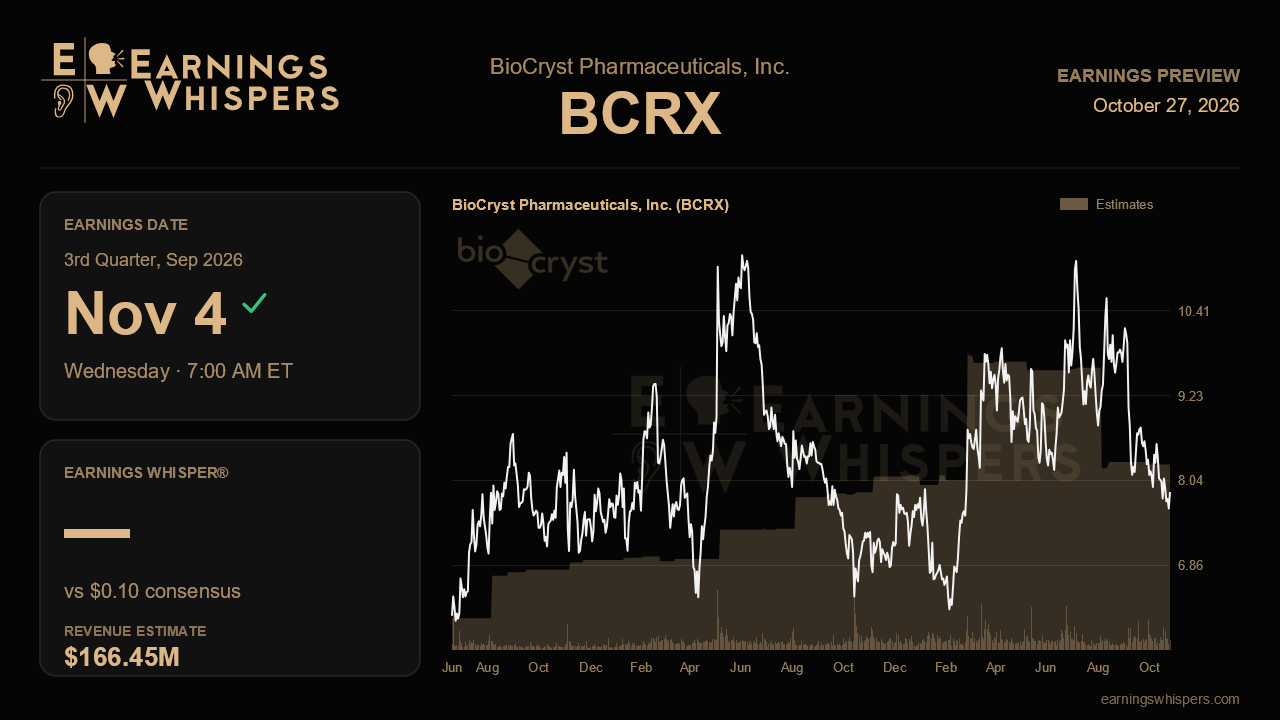
BioCryst Pharmaceuticals heads into its third-quarter report with a curious disconnect. Management raised its full-year revenue outlook, cut its cost envelope and launched a long-delayed pediatric formulation last quarter, yet the stock has fallen 16.5% since then while the S&P 500 slipped just 1.4%. The November 4 release, due before the open, is the first quarter without the one-time license payment that flattered the prior period. That makes it a clean read on whether core Orladeo demand is strong enough to justify the confidence management projected in the summer.
The Street is looking for earnings of $0.10 per share on revenue of $166.5 million. That compares with $0.06 and $159.4 million a year ago, so profit is expected to rise about 67% on revenue growth of only 4.4%. The modest top-line figure needs context. The year-ago quarter included European sales that are no longer part of the comparison, and management said Orladeo grew about 10% on a comparable basis last quarter. A sequential drop from the $218.3 million reported in the second quarter should not alarm anyone. Roughly $55.7 million of that came from the upfront payment on the Navenibart European license, which leaves underlying revenue in the low $160 millions.
The guidance math is where this report gets interesting. Management lifted its 2026 revenue forecast to $690 million to $715 million, but the full increase came from the license deal. Orladeo guidance stayed at $625 million to $645 million for the third straight update. First-half Orladeo sales totaled about $306.5 million, which implies the second half must deliver roughly $159 million to $169 million per quarter. Consensus for the full year sits near $676.5 million, below the low end of the company's range. Analysts are either skeptical or slow to update, and either way the bar for this quarter looks reachable. An Orladeo figure in the mid-$160 millions would show the core business is pacing toward the upper half of its range. That would also make an increase to Orladeo guidance, which management has so far avoided, a real possibility.
Several operating threads from the last call will decide that outcome. The pediatric oral pellets started shipping in the summer and logged 47 prescriptions by the end of July. That was well ahead of the company's full-year expectation, and several came from new prescribers. Continued momentum, along with prescriber additions above the historical pace of about 60 a month, would show the launch is broadening demand rather than shifting existing patients. The pay rate, which edged up to 84%, should hold or improve, because management credited price for about half of recent growth. The main swing factor is the move to CareMed as Orladeo's sole specialty pharmacy, which only began last quarter. Pharmacy transitions often cause shipment timing hiccups, and a soft quarter blamed on CareMed would test the stable-demand story.
On costs, management cut non-GAAP operating expense guidance to $420 million to $440 million from $450 million to $470 million. It is also closing its Birmingham research facility and ending internal discovery work. Steady spending discipline would support the earnings leverage built into the consensus estimate and protect a balance sheet that management calls the strongest in the company's history, with more than $350 million in cash.
Sentiment has clearly soured, with bearish readings rising to about 36% from roughly 14% a quarter ago. At $7.88, the stock trades below its 200-day moving average of $8.71 and sits near the bottom of its post-earnings range of $7.52 to $10.68. Expectations look subdued rather than stretched. The test is straightforward: Orladeo needs to show, without help from a license payment, that the pediatric launch and steady pricing can push the core franchise past a guidance range that has not moved all year.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 8 hours | |
| Oct-21 | |
| Oct-21 | |
| Oct-05 | |
| Sep-21 | |
| Sep-10 | |
| Sep-08 | |
| Sep-01 | |
| Aug-28 | |
| Aug-25 | |
| Aug-05 | |
| Aug-05 | |
| Aug-05 | |
| Aug-05 | |
| Jul-22 |
