BioCryst Beats On ORLADEYO Strength, But A One-Time Pharmacy Inventory Build Explains Why Product Guidance Stayed Put
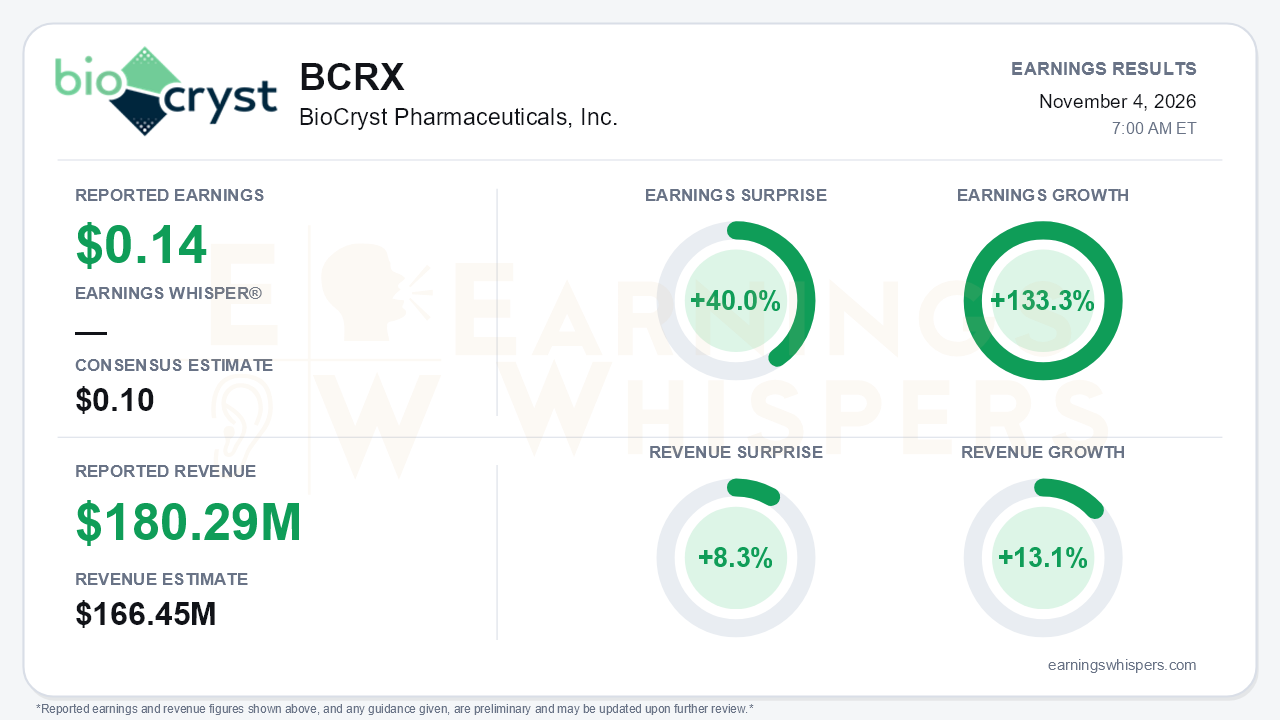
BioCryst Pharmaceuticals delivered a clear beat in the third quarter. Diluted EPS of $0.14 topped the $0.10 consensus by 40.0% and grew 133.3% year over year. Revenue of $180.29 million exceeded the $166.45 million estimate by 8.3% and rose 13.1%. Management raised total-revenue guidance for a second straight quarter and cut its operating-expense outlook again. Yet the most telling number is the one that did not move. ORLADEYO guidance stayed at $625 million to $645 million because part of the quarter's product strength came from a one-time inventory build at new specialty pharmacy CareMed. That is the central tension: the earnings power is real, but the top-line acceleration is partly borrowed.
The quality of the beat deserves scrutiny. ORLADEYO revenue reached $174.8 million, up from $158.2 million in Q2 and $148.3 million in Q1. Growth excluding Europe was about 20%, versus roughly 10% in Q2. On the call, management sized the CareMed stocking at the upper-teens millions of dollars and said it will not recur. Strip out a build of that size and ORLADEYO looks closer to Q2's level than the headline suggests. Management said only that ex-Europe ORLADEYO revenue still grew year over year after removing the build. The full-year guidance makes the same point. With $481.4 million booked through nine months, the unchanged range implies fourth-quarter ORLADEYO revenue of roughly $144 million to $164 million, below Q3's figure.
The profitability story is cleaner. Non-GAAP operating profit jumped to $86.5 million from $50.8 million, and non-GAAP net income roughly doubled to $71.1 million. Non-GAAP R&D slipped to $37.1 million, even as navenibart pivotal spending rose, because the Birmingham site closure eliminated internal programs. On a GAAP basis, operating profit nearly doubled to $53.3 million and net income reached $37.9 million. Those GAAP figures absorbed about $19 million of restructuring charges, of which roughly $10 million was cash. The company now expects the closure to save $30 million to $35 million a year once fully realized. Full-year non-GAAP opex guidance fell for a third time, to $415 million to $425 million from an original $450 million to $470 million. Management also pointed to lower 2027 spending. Cash rose to $376.4 million from about $350 million in Q2 and $261 million in Q1. That cushion matters against a $395.6 million term loan and a $421.7 million royalty financing obligation.
The guidance raise also needs context. Total revenue guidance moved to $715 million to $730 million from $690 million to $715 million. The increase came from navenibart European licensing revenue and international RAPIVAB orders, not from the core HAE franchise, and the call characterized those sources as low margin.
The call preserved a credible growth story around ORLADEYO's reach. The pediatric pellet launch is running ahead of plan with strong early reimbursement, and management now suggests that market may exceed its prior 500-patient estimate. The October approval of 150 mg pellets for patients 12 and older opens a new formulation choice for the core adult population, with launch slated for November. Management also said CareMed is shortening the time from prescription to first shipment. Bears have legitimate ammunition, though:
- **Paid rate:** It dipped seasonally to roughly 80% to 83% from 84%.
- **Competition:** Management expects oral rival deucrictibant to take share, while arguing it will not erode the existing ORLADEYO base.
- **Market size:** The 2033 HAE market outlook was reframed as a $1.4 billion to $2.8 billion range, versus the earlier "$1.8 billion-plus."
The pipeline narrowed to rare diseases with the discontinuation of STAR-0310. Netherton syndrome data for BCX17725 is due in December, and management framed a 20% to 25% improvement on the disease's severity score (IASI) as clinically meaningful. That readout is binary. Navenibart pivotal results remain on track for Q3 2027.
The market was not leaning bullish into the print. Earnings Whispers investor sentiment fell from -0.14 after the prior report to -0.35, a meaningful move deeper into negative territory. Shares closed at $8.57 before the release, down 9.2% from the $9.44 open after the August report. The stock sat about 2% below its 200-day moving average of $8.75 and well below its August 12 quarter high of $10.68. It had rebounded 14% off the October 23 low of $7.52. Price and AVWAP trend readings remain negative, while momentum has turned positive, consistent with a recovery from the October low that has not yet reclaimed the summer highs.
The bottom line is that BioCryst's quarter showed a business becoming structurally more profitable, with expanding margins, falling costs and a growing cash balance. The ORLADEYO revenue acceleration, however, was flattered by a non-recurring inventory build that management itself declined to extrapolate. Investors weighing the beat should focus on whether pellet uptake and the CareMed transition can sustain growth in the fourth quarter without that stocking benefit, and on the December Netherton readout.
Read our earnings preview for BioCryst Pharmaceuticals, Inc.: https://www.earningswhispers.com/article/BCRX/21679
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Oct-29 | |
| Oct-27 | |
| Oct-21 | |
| Oct-21 | |
| Oct-05 | |
| Sep-21 | |
| Sep-10 | |
| Sep-08 | |
| Sep-01 | |
| Aug-28 | |
| Aug-25 |
