Autohome Faces A Sequential Rebound Test As China's Car Slump Deepens
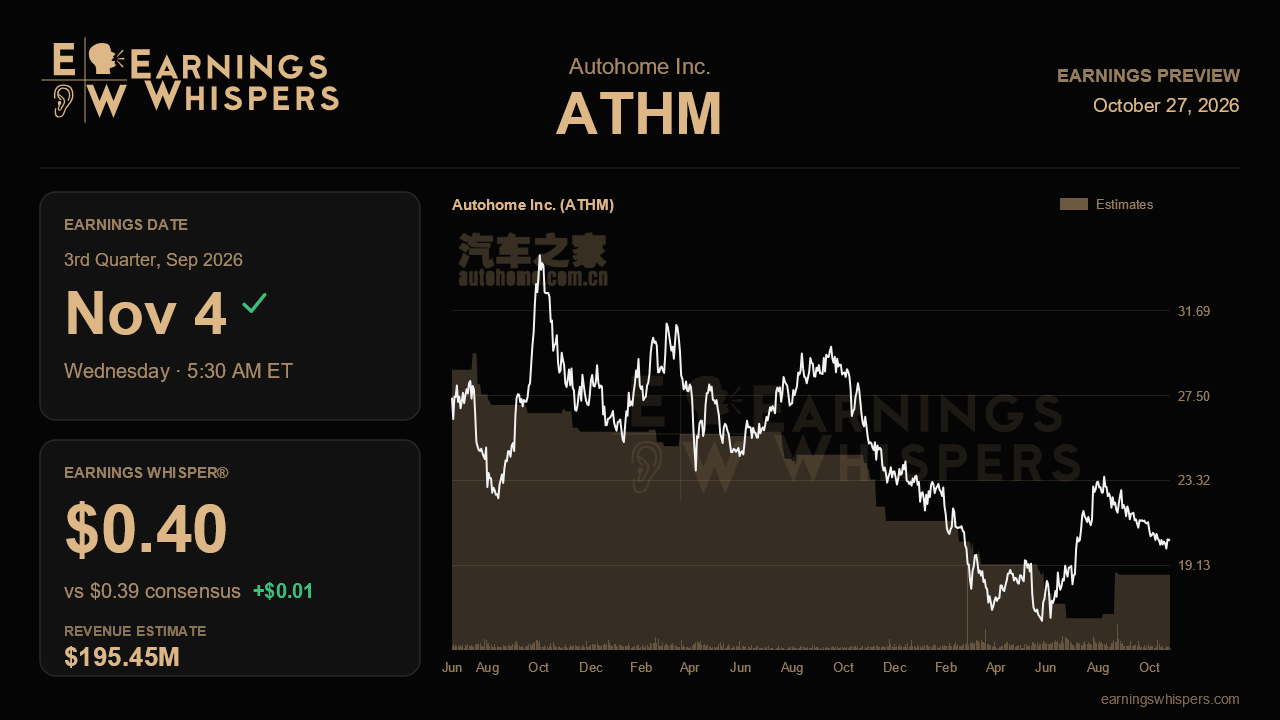
Autohome heads into its third-quarter report with an awkward mismatch between the industry it serves and the numbers Wall Street expects. Three months ago, management relayed a brutal downgrade in China's auto outlook, with full-year passenger vehicle retail now seen falling about 16% after early-year forecasts called for slight growth. Yet consensus calls for both revenue and earnings to climb from the second quarter. The report due before the open on November 4 will show whether margin discipline, buybacks and a handful of new businesses can carry results while the core advertising and lead-generation engine keeps shrinking.
Analysts expect earnings of $0.39 per share on revenue of roughly $195.5 million. That top line would mark a 21.8% contraction from the year-ago $249.8 million, a steep decline by any measure. But it would also represent an increase of about 11% from the $176.6 million reported last quarter, and the EPS target sits well above the prior quarter's $0.32 while matching the year-ago figure. The Earnings Whisper of $0.40 is only a penny above consensus, so the bar is not being quietly raised in any meaningful way. Management did not provide formal guidance, which leaves the industry data from the last call as the best yardstick.
That yardstick is not encouraging for the revenue line. On the prior call, management noted second-quarter domestic new vehicle sales fell 22%, with new energy vehicles declining 8% and combustion models down 38%. Losing NEV growth matters because it had been the one segment still funding automaker marketing budgets. Media services revenue has slid for several quarters amid the price war, and dealers are stretched, with roughly three quarters missing first-half targets and industry profit margins at a record low. Any sign that media or lead-generation revenue stabilized sequentially would validate the Street's rebound math. Another step down in both would challenge it and suggest the consensus top line is too generous.
The more defensible part of the story is profitability. Gross margin recovered to 77.1% last quarter from 75.5% in the first quarter and a trough of 63.7% a year ago, when lower-margin transaction revenue weighed on the mix. Flat year-over-year EPS on sharply lower revenue only works if that margin holds and the share count keeps falling. Here the capital return story helps: the company finished its $200 million repurchase early, launched a larger $400 million program with about a tenth already executed, and reaffirmed a full-year dividend of at least RMB1.5 billion. The tension is that management's growth bets, from online car purchasing in five cities to the new offline franchise network and used-car exports, are transaction-heavy and will dilute margins as they scale. Early volume data on these initiatives, and on the Cheese Car Butler AI agent, would show whether they are becoming real revenue contributors or remain small experiments.
Sentiment has warmed considerably, with bullish readings near 41% compared with about 15% ahead of the last report. The stock has not followed. Shares are down about 9% since the prior release, trailing a flat S&P 500, and at $20.40 they sit near the lower end of the post-earnings range of $19.62 to $22.92, barely above the 200-day moving average of $20.08. That range is far tighter than the previous quarter's swings, hinting at a market waiting for evidence rather than betting on a turn.
The central question is whether Autohome can show its earnings floor is sturdy even as the auto market weakens. A quarter that holds gross margin in the high 70s, delivers the sequential revenue lift, and shows traction in the new transaction businesses would keep the margin-and-buyback narrative intact. A further slide in media and lead revenue, especially with commentary pointing to deeper industry cuts, would suggest buybacks are cushioning a business that has yet to find its bottom.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| Oct-14 | |
| Aug-20 | |
| Aug-20 | |
| Aug-20 | |
| Aug-18 | |
| Aug-12 | |
| Aug-12 | |
| Jul-31 | |
| Jul-28 | |
| Jun-23 | |
| May-28 | |
| May-28 | |
| May-28 | |
| May-14 |
