Autohome Misses On EPS As Lower-Margin Transaction Revenue Rebuilds The Top Line While The Core Business Keeps Shrinking
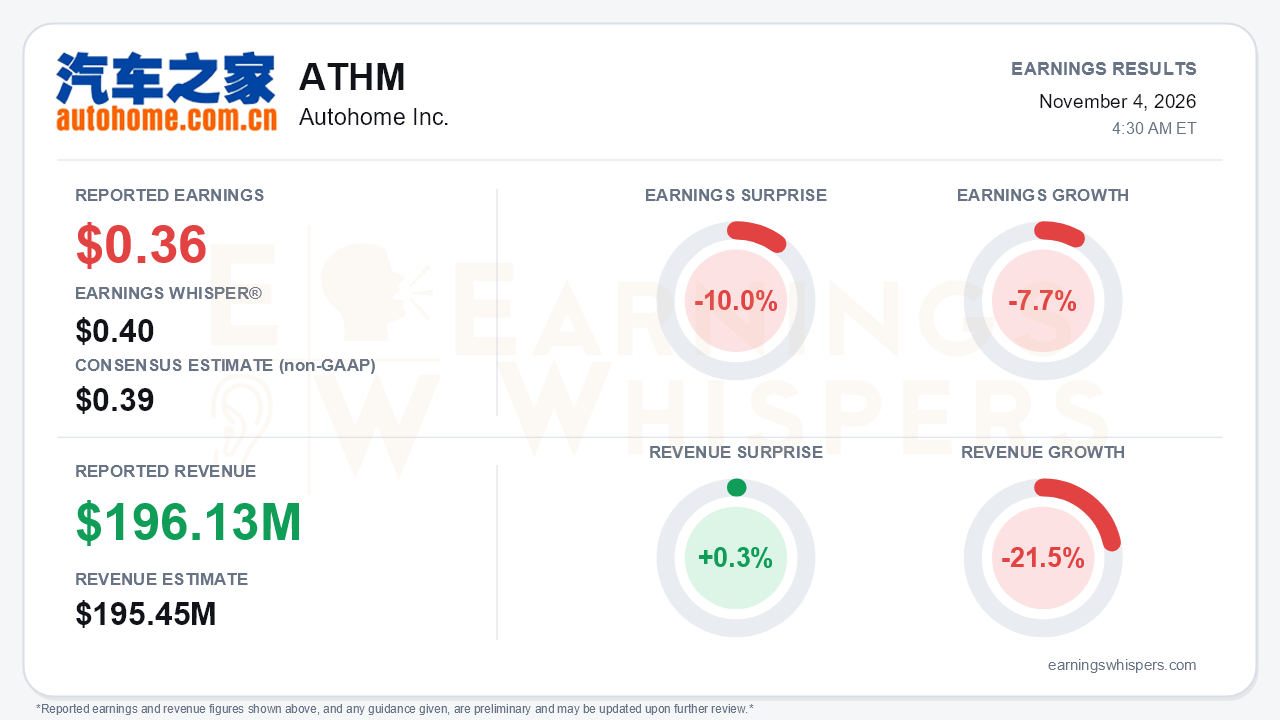
Autohome (NYSE: ATHM) reported third-quarter non-GAAP earnings of $0.36 per ADS, missing the $0.39 consensus by 10.0% and falling short of the $0.40 Earnings Whisper. Earnings fell 7.7% from a year ago. Revenue of $196.13 million (RMB1.31 billion) was essentially in line, edging past consensus by 0.3%, but fell 21.5% year over year. The central tension is that the top line is recovering sequentially, from RMB1.05 billion in Q1 to RMB1.2 billion in Q2 and RMB1.31 billion now. That improvement comes almost entirely from a lower-margin transaction business. Meanwhile the high-margin media and lead-generation franchise that built the company keeps shrinking.
The composition of the quarter tells the story. Online marketplace and others revenue rose to RMB547 million from RMB357 million in Q2, as the new retail model began contributing. Media services fell to RMB241 million from RMB280 million in Q2. Lead generation slipped to RMB526 million from RMB560 million, with management citing lower dealer spending and fewer paying dealers. The mix shift pulled gross margin down to 67.2% from 77.1% in Q2, although it is still above the 63.7% of a year ago. Operating profit fell to RMB96 million from RMB130 million in Q2 and RMB147 million a year earlier. That figure was helped by RMB73 million of other operating income and by deep cost cuts, including product development down to RMB195 million from RMB279 million on lower personnel costs.
The GAAP picture is weaker still. Net income attributable to Autohome was RMB195 million versus RMB437 million last year. Two non-operating factors drove much of that gap. Equity-method investments swung from a RMB133 million gain to a RMB16 million loss, and interest and investment income dropped to RMB94 million from RMB162 million as the cash pile shrank. On an adjusted basis, net income fell to RMB253 million from RMB407 million a year ago and RMB277 million in Q2. Per-ADS figures were cushioned by a much smaller share count, so buybacks are doing meaningful work in protecting the per-share results.
The call made clear that the industry backdrop worsened again. The China Passenger Car Association (CPCA) now forecasts 2026 retail sales down 22%. That compares with -16% cited on the Q2 call and roughly +1% at the start of the year, and implies a fourth-quarter decline of 20-25%. The 'Golden September, Silver October' recovery management expected last quarter did not materialize. Management now argues the market has bottomed and points to the CPCA's 0-5% growth forecast for 2027. That is a forward-looking framing, not something the quarter's numbers demonstrate. Industry profit margins near 3.3% and dealer distress continue to squeeze customer budgets.
Execution on new initiatives, by contrast, was fast:
- **Autohome Mall** expanded to 38 cities and more than 1,700 dealers, from 5 cities and about 400 dealers last quarter.
- **Good Car franchise stores** grew to more than 170 from about 100.
- **The full-process used-car selling pilot** expanded from 2 cities to 6.
- **The cross-border export platform** is averaging more than 3,000 daily listings, with monthly volume rising since its first order in July.
- **The Cheese Car Butler AI agent** officially launched in September. Management conceded AI is not yet producing revenue at scale, while its costs already sit in the results.
- **Mobile daily active users** recovered to 79.14 million, up 3.4% year over year.
Capital returns remain a pillar of the story. Operating cash flow improved to RMB360 million from RMB261 million in Q2. The company declared a roughly RMB1 billion second-half dividend ($1.58 per ADS), bringing 2026 declarations to about RMB1.5 billion. It has also executed $155.4 million of its $400 million buyback, up from $43.6 million at the Q2 call. The cost is a steadily declining balance sheet: cash and investments stand at RMB17.65 billion, down from RMB19.36 billion in Q2 and RMB21.36 billion at the end of 2025.
Investor sentiment moved noticeably more positive heading into the report, rising from 0.145 to 0.342. That contrasts sharply with price action. Shares fell 11.1% from the open after the August report to $19.96. They sit essentially on the $20.00 200-day moving average, 12.9% below the inter-earnings high and just 1.7% above the October low. Improving sentiment, a whisper number above consensus and a stock pressed near its lows set up a quarter that needed to deliver. A miss with declining profitability does not resolve that disconnect, and the AVWAP reading remains negative.
The bottom line is that Autohome is successfully building a larger transaction-driven business, but it is doing so at structurally lower margins while its legacy core erodes amid a deepening auto downturn. Bulls can point to sequential revenue growth, rapid footprint expansion, rising cash flow and generous shareholder returns. Bears have legitimate ammunition in the earnings miss, compressing margins, a missed seasonal recovery and a shrinking cash base. Until the new businesses show they can carry margins, or the industry bottom management describes shows up in the numbers, the quality of the top-line recovery deserves scrutiny.
Read our earnings preview for Autohome Inc.: https://www.earningswhispers.com/article/ATHM/21671
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Oct-27 | |
| Oct-14 | |
| Aug-20 | |
| Aug-20 | |
| Aug-20 | |
| Aug-18 | |
| Aug-12 | |
| Aug-12 | |
| Jul-31 | |
| Jul-28 | |
| Jun-23 | |
| May-28 | |
| May-28 |
