ArcBest Must Prove Its Margin Breakout Can Hold As Fuel Fades And The Stock Slides
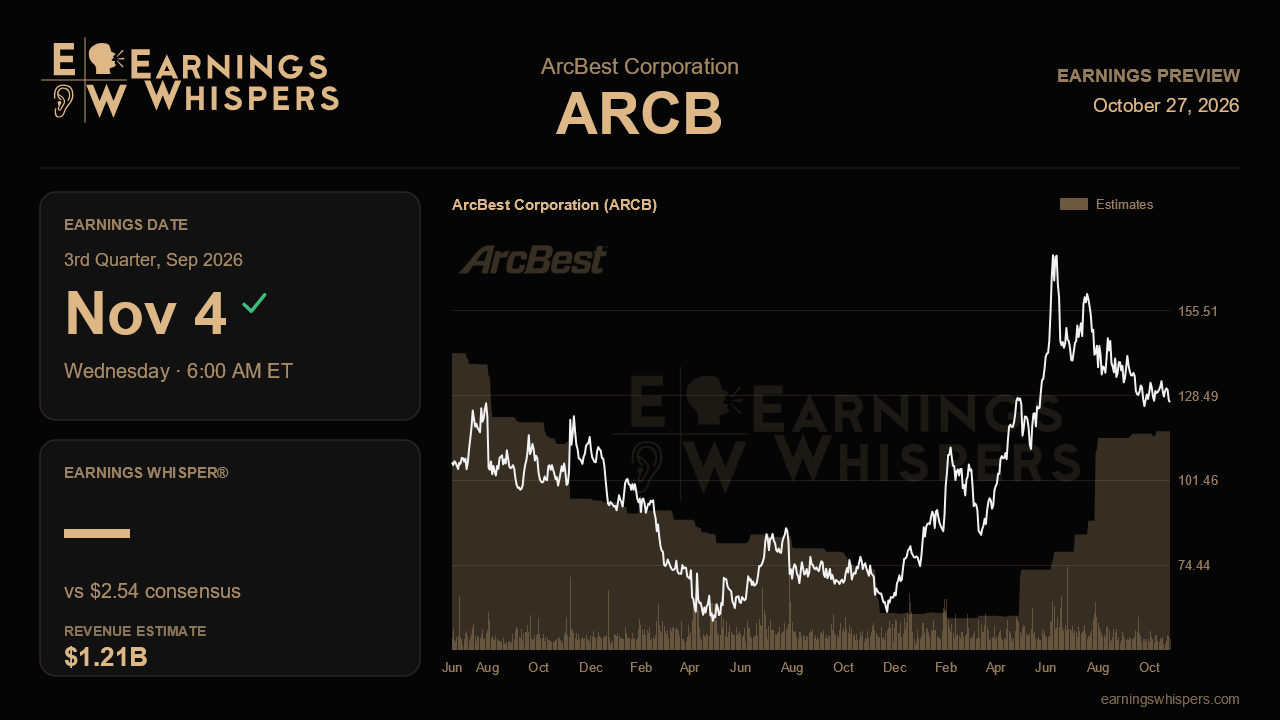
ArcBest's second quarter looked like the turn shareholders had been waiting for, yet the stock has behaved as if nobody believes it. Adjusted earnings leapt to $2.38 a share from just $0.32 in the first quarter, the asset-based unit's operating ratio improved by 650 basis points in a single quarter to 90.8%, and management layered a roughly $40 million cost-cutting program on top. Since then the shares have fallen 15.5% while the S&P 500 gained 3.4%. The third-quarter report, due before the open on November 4, is the first real test of whether that inflection was durable or flattered by fuel and favorable freight mix.
The Street is not asking for a retreat. Consensus calls for $2.54 a share on revenue of about $1.21 billion, implying 74% earnings growth and 15.4% revenue growth from a year ago, when ArcBest earned $1.46 on $1.05 billion. That is strong growth by any standard. The more telling comparison is sequential: analysts expect earnings to climb above the second quarter even though management guided the asset-based operating ratio roughly flat from 90.8% and warned that fuel surcharge revenue would step down. Some of the gap can be bridged by the asset-light business, which management guided to $6 million to $8 million of operating income versus $6.3 million last quarter, and by early savings from the restructuring. Still, the estimate leaves little room for slippage in the core less-than-truckload network.
Volume is where the story either holds or cracks. Daily tonnage accelerated to 8% growth in July from 5% in the second quarter, and weight per shipment jumped 11%, helped by heavier freight and some spillover as truckload capacity exits the market. The question is whether that momentum carried through August and September. The caution flags are already visible: revenue per day growth slowed from 11% in April to 7% in July, and revenue per hundredweight excluding fuel slipped by low single digits as heavier shipments diluted yield. Pricing discipline looks intact on paper, with contract renewals near 5.8% and a 5.9% general rate increase in June, so a further yield decline would point to mix and demand rather than concessions. Management also acknowledged that industrial demand has not broadly recovered, with consumer and apparel freight soft and housing-related volumes depressed.
The restructuring adds noise and opportunity. Brand consolidation, closing about 1% of ABF doors and shutting down Vox are expected to save roughly $40 million annually at full run rate by early 2027, but $6 million to $7 million of cash costs land mostly in this quarter. Clean adjusted numbers matter less here than evidence that savings are beginning to show up in labor and facility costs. Updates on the new ArcBest View platform and AI-driven routing and capacity sourcing will help show whether the 35% productivity jump in asset-light was a one-off or a structural gain.
Sentiment has cooled sharply, sliding to barely positive from a reading of 24.5% bullish heading into the last report. The shares, at $126.35, sit just above the post-earnings low of $124.06 and only marginally over the 200-day moving average near $123.61, so the stock is leaning on support rather than pressing toward the $149.55 high. Lower enthusiasm can make a solid print easier to reward, but a break of that floor on disappointing results would be technically damaging.
The central issue is whether ArcBest can hold an operating ratio near 91% without the fuel tailwind while tonnage keeps growing. If it does, the second quarter becomes a new baseline rather than a peak, and the market's skepticism looks overdone. If the ratio drifts back and yields keep eroding, investors will conclude the inflection was borrowed from fuel and freight mix.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-13 | |
| Oct-01 | |
| Sep-24 | |
| Sep-09 | |
| Sep-08 | |
| Aug-03 | |
| Jul-31 | |
| Jul-29 | |
| Jul-29 | |
| Jul-29 | |
| Jul-29 | |
| Jul-24 | |
| Jul-16 | |
| Jul-16 |
