Cencora's Fiscal Year-End Report Tests Whether Its US Operating Rebound Has Staying Power
Three months ago Cencora turned a soft quarter into a convincing comeback story. US operating income growth jumped to 17% from 6%, guidance moved higher, and the company spent $1 billion buying back its own stock. Management went further and called the fiscal fourth quarter the year's strongest stretch of organic growth. When the drug distributor reports before the open on November 4, the question is simple: did that promise hold up, and can the momentum carry into a fiscal 2027 that already faces a known headwind?
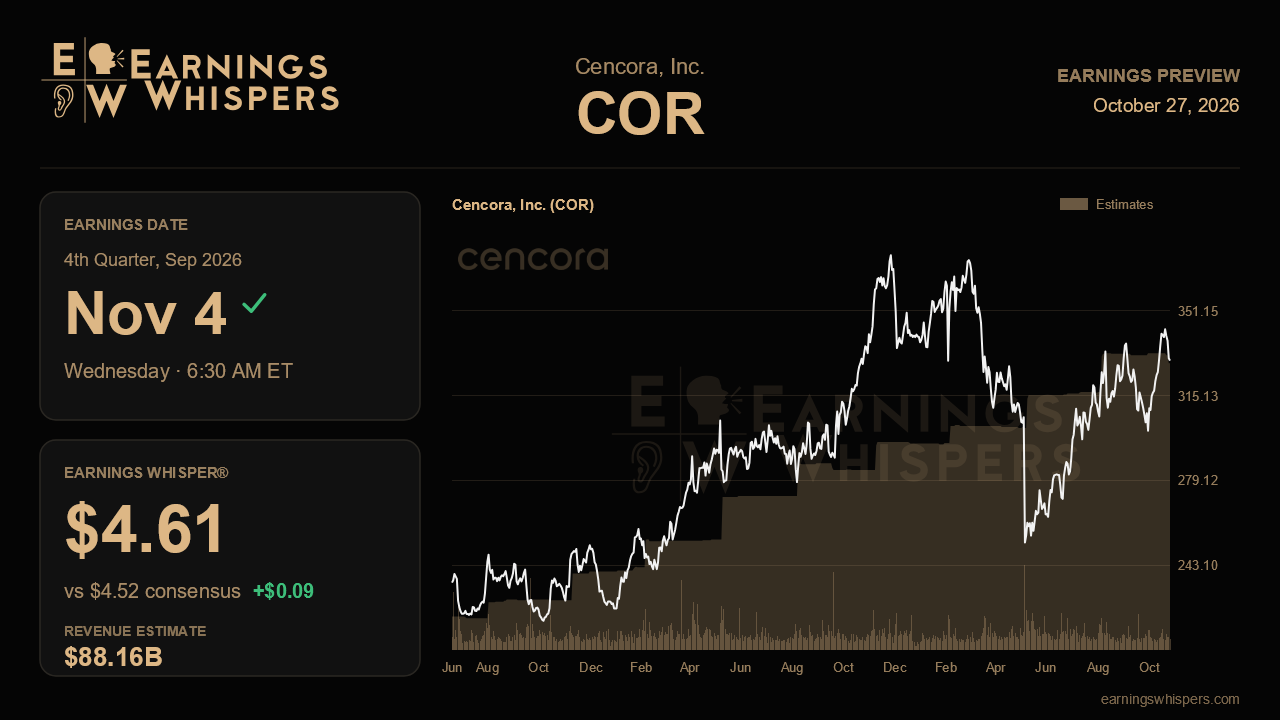
The Street expects adjusted earnings of $4.52 a share on revenue of about $88.16 billion. That would be roughly 17.7% EPS growth on revenue growth of just 5.3%, a gap that sums up Cencora's model right now. The top line grows modestly while margins, mix and a shrinking share count do the heavy lifting. The Earnings Whisper figure of $4.61 sits about 2% above consensus. That is not dramatic, but it suggests the informal bar is closer to a clean beat than an in-line print. Full-year consensus of $17.79 sits near the low end of management's raised $17.75 to $17.95 range, below the $17.85 midpoint. If the fourth quarter delivers what management signaled, there is room for results to land comfortably above where the Street is anchored.
The most important evidence will come from US Healthcare Solutions. Last quarter's rebound was driven by renewed utilization in specialty, oncology and retina after weather hurt physician-office volumes in the spring. Core organic operating income, excluding One Oncology and a lapped oncology customer loss, grew at a double-digit rate, up from about 7%. Validation would mean that pace holds or improves and that full-year US operating income growth lands in the 14.5% to 15.5% range. Management also said One Oncology and RCA were running ahead of plan. Continued outperformance there would show the specialty and management services strategy is adding real value rather than simply adding revenue. A slip back toward single-digit core growth would suggest the third quarter was mostly a weather catch-up rather than a durable acceleration.
Revenue deserves attention for a different reason. Management already guided US revenue growth to the lower half of its 4% to 6% range. It also trimmed international growth toward 8% because of a stronger dollar. On top of that, Cencora is absorbing a $2.4 billion headwind from manufacturer list-price cuts and lower sales to a large mail-order customer that is insourcing biosimilars and brands. Because that business carries thin margins, a light top line would not necessarily matter. The concern would be if revenue softness starts showing up as pressure on gross profit. Internationally, the test is whether World Courier and European third-party logistics extend the double-digit operating income growth that pushed the segment up 21% last quarter.
The market has given Cencora some credit. Shares have gained 4.4% since the last report while the S&P 500 slipped 1.4%. At $330, the stock sits above its 200-day moving average of about $317 and in the upper half of its post-earnings range. It remains roughly 4.5% below the $345.46 high, so it is not yet pressing for a breakout. Sentiment has cooled slightly, to 16.0% bullish from 18.7%, which hints at measured optimism rather than euphoria.
Because this report closes the fiscal year, the forward conversation may matter as much as the quarter itself. Management has already put a figure on the MWI and Covetris combination: about $150 million of operating income and roughly $0.35 of EPS dilution in fiscal 2027 at a midpoint close. It also advised against modeling the iSouth retina carve-out. Policy issues around 340B and Part B drug pricing remain in the background. The narrative stays intact if Cencora shows that specialty-driven US operating growth is strong enough to absorb those known headwinds. Evidence that the third-quarter acceleration was a one-time recovery would challenge it.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-21 | |
| Oct-02 | |
| Sep-25 | |
| Sep-16 | |
| Sep-15 | |
| Aug-12 | |
| Aug-11 |
S&P 500 Medical Stocks: Three Trade Near Buy Points; One Rallies Despite Mixed Results
COR
Investor's Business Daily
|
| Aug-05 | |
| Aug-05 | |
| Aug-05 | |
| Aug-05 | |
| Jul-27 | |
| Jul-09 | |
| Jul-08 |
