Cencora Closes FY26 Above Raised Guidance, But A Divestiture-Diluted FY27 Outlook Resets Expectations Lower
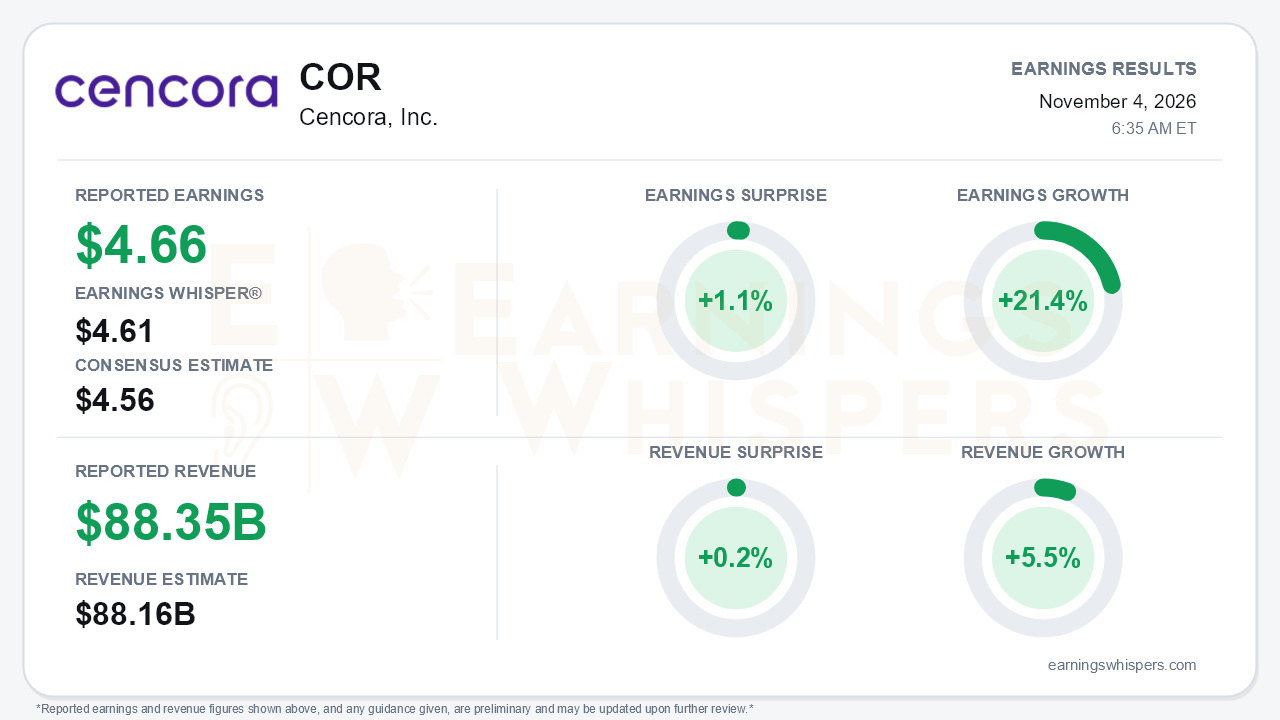
Cencora delivered a clean fiscal fourth-quarter beat. The more consequential news was a fiscal 2027 outlook that undershoots what the Street had penciled in. Adjusted EPS of $4.66 topped the $4.56 consensus by 1.1% and edged past the $4.61 Earnings Whisper number. Revenue of $88.355 billion beat by 0.2%. Earnings grew 21.4% year over year on 5.5% revenue growth. That closed a fiscal year in which adjusted EPS of $17.97 cleared even the twice-raised $17.75-$17.95 range. Management then guided FY27 adjusted EPS to $19.40-$19.75, implying 8% to 10% growth. That is well short of the roughly 14% Street figure referenced on the prior call, and it is the central tension: a business accelerating into year-end, paired with a headline guide that looks like a slowdown.
The quarter itself was largely driven by operations, though the quality of the beat deserves some scrutiny. On a GAAP basis, Cencora swung to diluted EPS of $2.71 from a $(1.75) loss a year ago, when a $724 million PharmaLex goodwill impairment hit results. Adjusted gross margin expanded 57 basis points to 4.04%, primarily from the February OneOncology acquisition, partly offset by lower-margin GLP-1 volume. Adjusted operating income rose 22.1%, and a 1.8% lower share count helped at the per-share line. Several items cut the other way:
- **Gross margin trajectory:** it slipped sequentially from 4.16% in Q3 and 4.31% in Q2, as GLP-1 revenue growth accelerated to $2.8 billion year over year.
- **Interest expense:** it jumped 75% on acquisition financing.
- **The "Other" bucket:** its 35.8% operating income gain was flattered partly by halted depreciation on held-for-sale assets.
- **Tax items:** a $146.8 million Swiss deferred-tax valuation charge was excluded from adjusted results.
Beneath the headline, the U.S. engine strengthened markedly. U.S. segment operating income growth accelerated from 6% in Q2 to 16% in Q3 and 22% in Q4, the strongest quarter of the year. Management's tone shifted accordingly, from defending transitory headwinds earlier in the year to talking about "momentum." Cash generation was a standout: FY26 adjusted free cash flow of $3.8 billion beat the roughly $3.0 billion guide held all year. The softer spot was International, where operating income growth eased to 16% from 21% in Q3, though constant-currency growth was a healthier 18.9%.
The resegmentation is the strategic story investors will now underwrite. The new Specialty Pharmaceutical and Provider Services segment is guided to 18% to 21% operating income growth in FY27, against a mid-teens long-term target. Specialty distribution revenue is expected to approach $100 billion. MSOs already contributed about 10% of FY26 operating income, and the pending majority-stake acquisition of American Oncology Network extends that platform. The cost of that clarity is a visibly slower legacy business. Pharmaceutical Distribution and Services is guided to just 2% to 4% operating income growth, weighed by a customer volume-shift wraparound and roughly $20 million of FX headwind.
The divestitures explain much of the guidance gap. Consolidated operating income growth of 4% to 6% becomes 8.5% to 11% excluding Other. Excluding the roughly $0.35 MWI/Covetrus impact, EPS growth would be 10% to 12%, consistent with the reaffirmed 10% to 14% long-term algorithm. Bears still have legitimate ammunition:
- free cash flow is guided down to about $3.5 billion as capex rises to about $1 billion;
- revenue growth slows to 3% to 5%;
- management addressed exposure to Option Care's infusion move and Cigna's new wholesale business only by saying it sits within the guidance range;
- post-election reimbursement uncertainty lingers.
Shareholder returns soften the blow: a 10% dividend increase and $1.25 billion of planned buybacks.
The market setup is more complicated than the surprise implies. Shares stood at $340.50 heading into the report, up 7.8% since the open after the August release. That left the stock about 7.4% above its 200-day moving average and just 1.4% below its inter-earnings high of $345.46, after a sharp rebound from a September 30 low of $295.01. Investor sentiment remained positive but roughly halved, from 0.19 to 0.09, so enthusiasm had already been cooling. The Earnings Whispers trend signals were uniformly positive entering the print, reflecting the strong run. A stock trading near the top of its range is less forgiving of a guide that reads light on the surface.
The bottom line is that Cencora's operating momentum, specialty mix shift and cash generation all improved, and its underlying FY27 growth sits within its long-term algorithm. However, divestiture dilution and a sluggish core distribution segment produce headline guidance below what investors expected. With shares near their quarterly high and sentiment already fading, the debate now turns on whether investors look through the portfolio pruning or anchor on the 8% to 10% figure.
Read our earnings preview for Cencora, Inc.: https://www.earningswhispers.com/article/COR/21688
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| 10 hours | |
| 10 hours | |
| 10 hours | |
| Oct-27 | |
| Oct-21 | |
| Oct-02 | |
| Sep-25 | |
| Sep-16 | |
| Sep-15 | |
| Aug-12 | |
| Aug-11 |
S&P 500 Medical Stocks: Three Trade Near Buy Points; One Rallies Despite Mixed Results
COR
Investor's Business Daily
|
| Aug-05 | |
| Aug-05 | |
| Aug-05 |
