CDW's 40% Rally Puts Margins, Cash Flow And A Fourth Guidance Raise To The Test
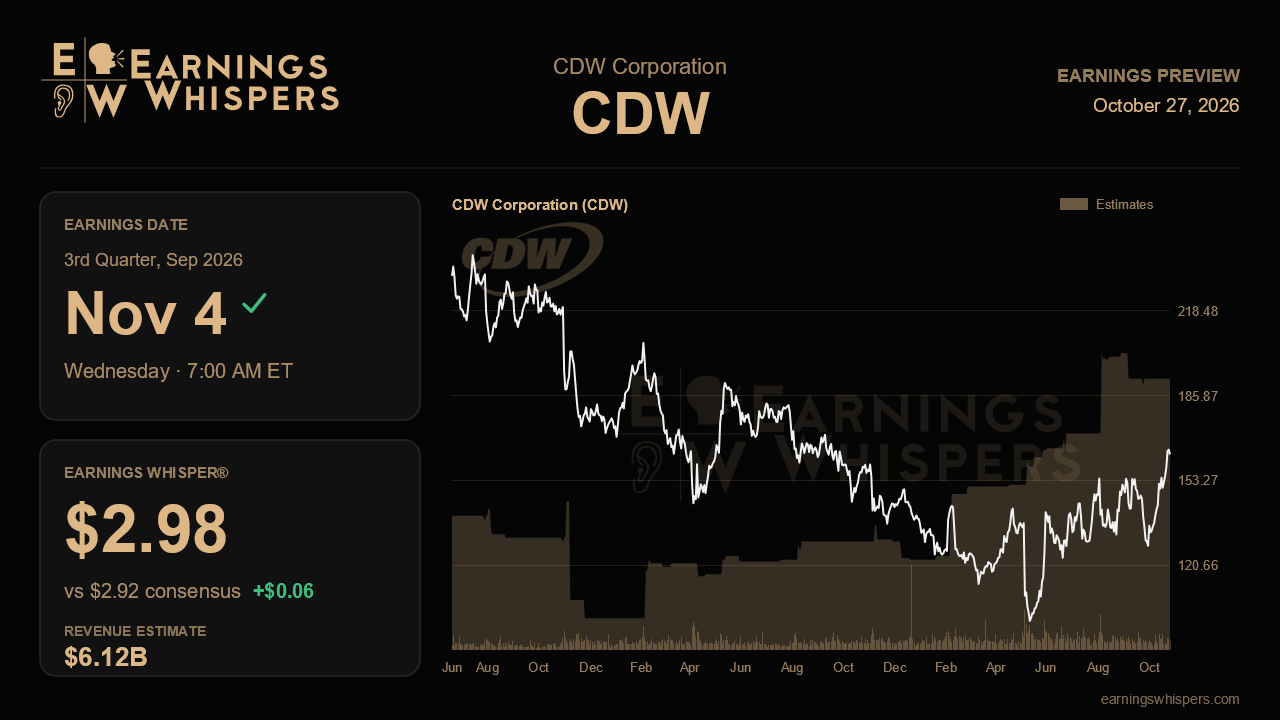
CDW heads into its third-quarter report as a very different stock than it was three months ago. Shares have climbed about 41% since the last release, while the S&P 500 slipped slightly. Behind the move was a quarter that finally delivered the operating leverage management had been promising, along with a third straight lift to the full-year outlook. The question now is whether the back half can carry that momentum without the margin and cash-flow soft spots growing large enough to matter.
The Street expects non-GAAP earnings of $2.92 per share on revenue of about $6.12 billion. That revenue figure would be roughly 6.7% above last year's $5.74 billion. It would also be a step down from the record $6.57 billion posted last quarter, so investors should not read a sequential decline as a demand problem. On earnings, consensus implies growth in the mid-teens from last year's $2.55, faster than the top line. That gap only works if cost discipline keeps doing its job. The Earnings Whisper of $2.98 sits modestly above consensus, a sign that the informal bar is a bit higher than the published one.
The progression of guidance is the core of the setup. Over three calls, management moved its full-year gross profit outlook from low single digits to mid-single digits. Over the same stretch, it lifted EPS growth expectations from mid-single digits to the high end of high-single digits and upgraded its view of the U.S. IT market. Guidance raised that many times sets a demanding standard. Simply reaffirming the outlook could feel like a pause, while another raise would confirm that the broadening demand is real. Last quarter, government sales rose 14% with federal improving, international sales jumped 23%, and server, storage and networking all grew double digits. Continued strength in those areas, along with backlog that keeps running ahead of invoicing, would support the improving narrative.
The less flattering half of the story is margin mix. Gross margin fell to 20.1% last quarter as large, low-margin enterprise infrastructure deals crowded out higher-value work. Management trimmed its full-year margin view to modestly below last year and warned that second-half margins would trail the prior-year period. A reading in that neighborhood is already expected. A further slide would raise doubts about how much of the revenue growth reaches the bottom line. Services, which grew just 1% on deployment timing, are the likely remedy. Management pushed the higher-margin services catch-up to late this year or early 2027. Any early evidence of that recovery, perhaps tied to the AI360 work with state and local governments or the AI security vulnerability program, would carry outsized weight.
Cash flow is the other swing factor. First-half free cash flow conversion was only 42% of non-GAAP net income, well short of the company's usual 80% to 90% benchmark, because of a roughly $400 million inventory build. Investors will want to see that inventory begin to unwind and conversion improve. Otherwise the earnings quality debate could resurface, especially with CFO Al Morales planning to retire in 2027 and a successor still being sought.
Sentiment has swung from firmly bearish before the last report to mildly bullish now, and the stock trades well above its 200-day moving average. At about $163, it sits within 2% of its post-earnings high of $166.15, so it is testing a breakout. That leaves little cushion for disappointment. The verdict will likely depend less on the headline beat than on whether operating income again outpaces gross profit while margins stabilize and cash conversion recovers. If CDW can show that the Geared for Growth savings are offsetting mix pressure, the improving story stays intact. If margins erode further, the rally may have priced in more than the quarter can deliver.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-21 | |
| Oct-19 | |
| Oct-15 | |
| Oct-13 | |
| Oct-01 | |
| Sep-28 | |
| Sep-25 | |
| Sep-22 | |
| Sep-11 | |
| Sep-11 | |
| Sep-02 | |
| Aug-27 | |
| Aug-25 | |
| Aug-25 |
