CDW's Growth Surges As Raised Outlook Outruns Margin Compression And Pull-Forward Questions
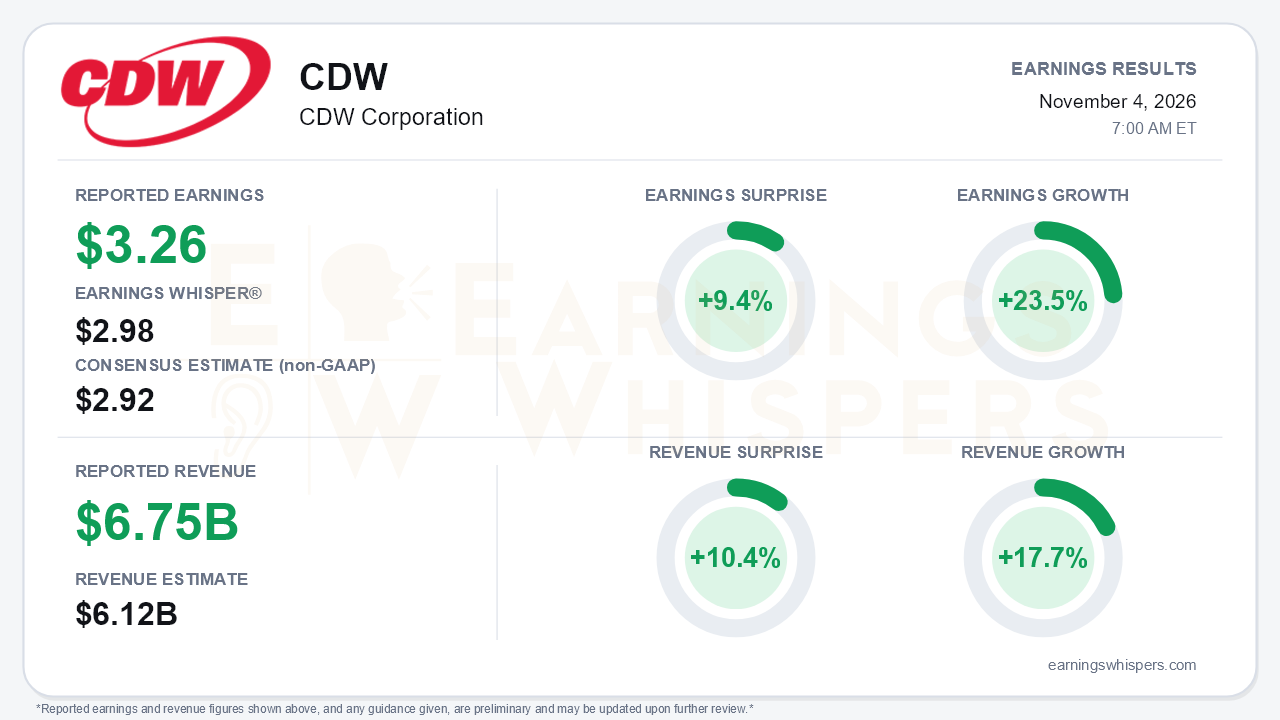
CDW delivered its strongest growth quarter in years. Non-GAAP earnings of $3.26 per share beat the $2.92 consensus by 9.4% and cleared the $2.98 Earnings Whisper number. Revenue of $6.755 billion topped the $6.12 billion consensus by 10.4%. Earnings grew 23.5% year over year on Earnings Whispers' normalized basis; the company's own comparison against $2.71 shows non-GAAP EPS growth of 20.4%. Revenue rose 17.7%, a sharp step up from roughly 10% in Q2, 9% in Q1 and 5% in Q4 2025. Management also raised its full-year outlook for the third consecutive quarter. That is the headline: a reseller that spent much of the past two years grinding through a soft IT market is now growing faster than almost anyone expected. The central tension is that much of this growth is coming in lower-margin form, and nobody, including management, will say how much of it is borrowed from 2027.
The quality of the beat deserves scrutiny. Gross profit rose a healthier-than-guided 10.3%, but gross margin fell 140 basis points year over year to 20.5%. The release attributes the decline to mix into, and lower margin in, certain product categories. That decline is steeper than the 70- and 60-basis-point slippage in Q2 and Q1, although margin did improve 40 basis points sequentially. GAAP results tell a more modest story. GAAP EPS rose 11.6% to $2.46 and net income increased just 6.5%. Below the operating line, the drags were a 19.8% jump in net interest expense and a tax rate that rose to 26.9% from 25.3%. Above it, workplace optimization charges of $31.0 million (versus $2.7 million) and acquisition costs of $13.8 million were excluded from non-GAAP results. A 4.6% reduction in diluted shares to 125.7 million also contributed meaningfully to per-share growth.
The operating breadth, however, is real. Commercial sales climbed 20.8%, led by a 73.2% surge in Financial Services. UK and Canada rose 26.0%, Government 9.9% and Education 7.5%, the last up from roughly 1% in Q2. Servers and storage more than doubled, and software rose 14%. Netted-down revenue reached a record 38.2% of gross profit. Services returned to growth at 2%, earlier than management expected. The more durable improvement may be on cost. Non-GAAP SG&A fell to 55.3% of gross profit, down 260 basis points sequentially, as Geared for Growth savings came in at or above plan. That held non-GAAP operating margin flat at 9.2% despite the gross margin squeeze. One caution: client device units declined, with growth driven by higher prices and richer configurations rather than volume.
The guidance trajectory is the key catalyst. Management now sees US IT market growth in the high single digits, up from mid single digits in Q2 and low single digits earlier in the year. It expects CDW to outperform that market by 300-400 basis points, versus 200-300 previously. Full-year gross profit growth is now guided to mid-to-high single digits and non-GAAP EPS growth to low double digits. Backlog continues to build, with new orders outpacing invoicing in enterprise infrastructure. The $525 million Lovelytics acquisition adds gross-margin-accretive data and AI services, and the dividend rose roughly 8% to $0.68. Bears still have legitimate ammunition:
- The full-year gross margin outlook has now been cut four times, sliding from "slightly higher" to "down" versus 2025.
- Interest expense guidance rose to $255-260 million after a $1.5 billion notes issuance.
- Inventory roughly doubled year over year to $1.02 billion, and days sales outstanding reached 100.
- Year-to-date adjusted free cash flow conversion of 73% remains below the 80-90% target, even after a strong $506 million quarter.
- Management declined to quantify any pull-forward or discuss 2027, and a CFO transition is pending.
Investors had already begun to reprice the story. Sentiment improved meaningfully, from -0.245 to -0.082. It remains slightly negative, which suggests the stock's rally was not built on euphoric expectations. Shares rose 29.7% from the $115.45 open after the August report to $149.77. They sit 12.3% above the 200-day moving average and climbed from a quarterly low of $113.00 to a 52-week high of $166.15 on October 23. The stock entered the report roughly 10% below that peak, so some of the enthusiasm had already been taken off the table. The Earnings Whispers trend signals are mostly positive, though sequential growth reads only neutral.
The bottom line is that CDW produced a genuine acceleration quarter and a third straight guidance raise, backed by broad end-market demand and real cost discipline. Still, the growth is increasingly hardware-heavy, price-driven and margin-dilutive. It is also funded by a more leveraged, working-capital-intensive balance sheet. Investors who have already bid the shares up nearly 30% will need evidence that this demand wave is durable rather than pulled forward, and management left that question unanswered.
Read our earnings preview for CDW Corporation: https://www.earningswhispers.com/article/CDW/21686
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 2 hours | |
| 4 hours | |
| 10 hours | |
| 11 hours | |
| 11 hours | |
| Oct-30 | |
| Oct-27 | |
| Oct-21 | |
| Oct-19 | |
| Oct-15 | |
| Oct-13 | |
| Oct-01 | |
| Sep-28 | |
| Sep-25 |
