Blackstone Secured Lending Faces Dividend Reset Test As Earnings Slide Below Payout
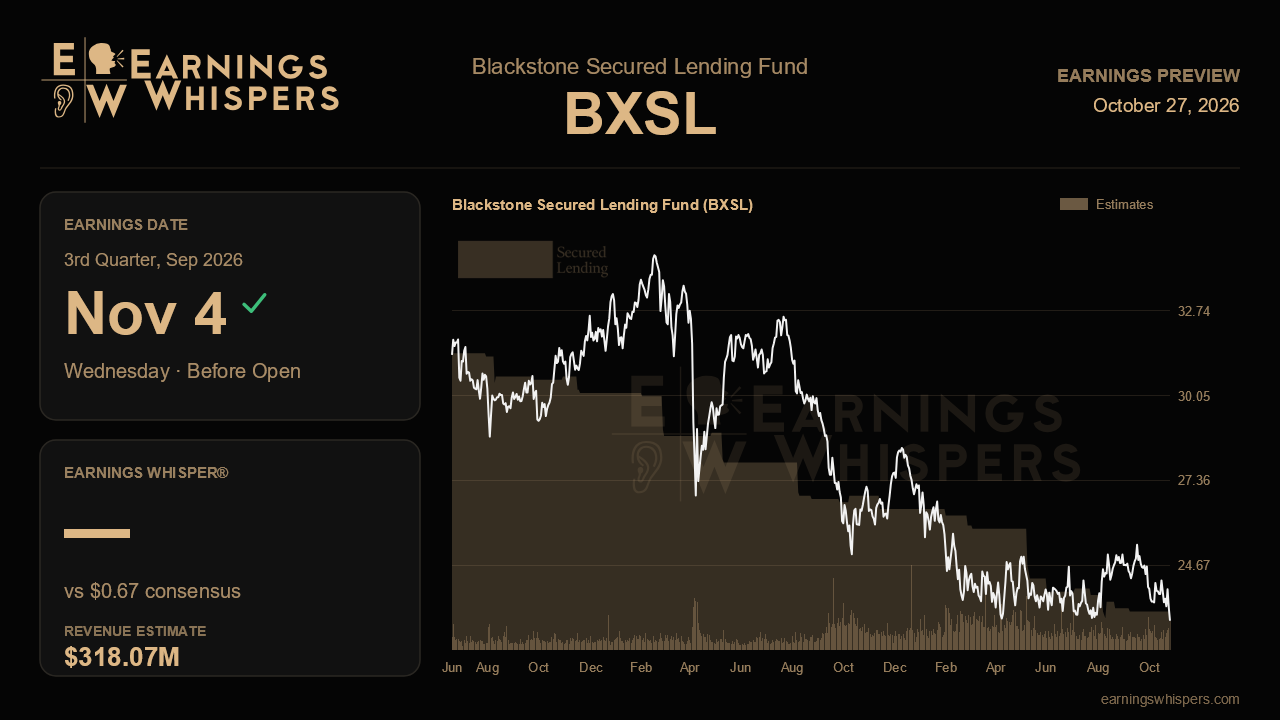
For 28 straight quarters, Blackstone Secured Lending Fund earned more than it paid out. That streak ended last quarter, and management spent the call preparing shareholders for a lower dividend tied to falling base rates. When the business development company reports before the open on November 4, the question is no longer whether the payout comes down. It is how far, how quickly, and whether the portfolio underneath can stop shedding value while the reset happens.
The Street is bracing for a meaningful step down. Consensus calls for earnings of $0.67 per share, well below the $0.75 in net investment income reported last quarter and the $0.82 earned a year ago, an expected decline of roughly 18%. Revenue is projected at $318.1 million, down about 11% from a year earlier but only modestly below last quarter's $320.5 million. That gap is worth noticing. A nearly flat top line paired with a sharp drop in per-share earnings suggests analysts expect heavier pressure from expenses or financing costs, or that the estimate is not measured on exactly the same basis as reported net investment income. Either way, a $0.67 figure would sit a full dime below the current $0.77 dividend, which makes a formal cut look less like a possibility and more like the base case. The company has not offered explicit numerical guidance, so the size of any new dividend, and whether management frames it as a floor, may matter more than the earnings figure itself.
The trajectory last quarter explains the anxiety. Net investment income has fallen every quarter for a year, and coverage slid from 106% to roughly 97%, with the shortfall funded by drawing on spillover income that has dwindled to $1.77 per share. Net asset value has dropped about 6% over the same stretch to $25.53, with the overall portfolio mark sliding to 95.2 and the weakest tenth of holdings marked at 70. Management attributed about half of last quarter's markdowns to spread widening rather than borrower distress. If spreads have stabilized, NAV should hold up better this time. A further decline driven by company-specific write-downs would challenge the argument that credit trouble is contained.
There are genuine offsets to test. Non-accruals improved to 1.8% of fair value after two restructurings cleared, and no new problem loans were added. Repayments topped $700 million last quarter, with repaid assets marked around 94, which pulls value back toward par as they exit. New loans are coming with wider spreads and lower leverage, PIK income has fallen about 20% since late last year, and interest coverage edged up to 2.1x. Confirmation of those trends, plus any new non-accruals staying absent despite loan-to-value ratios creeping toward 52%, would support the view that this is an earnings reset rather than a credit unwind. Shareholders should also look for activation of the unused $250 million buyback, which management hinted could come in the second half as repayment capacity builds. With shares near 90% of last reported NAV, repurchases would be accretive.
The market has not been forgiving. The stock is down 2.8% since the last report, trailing the S&P 500 by about two points, and at $22.91 it sits just above its post-earnings low of $22.82 and well under its 200-day average of $24.21. Sentiment has warmed from clearly bearish ahead of last quarter to roughly neutral, which hints that much of the dividend pain may already be priced in.
The central issue is whether management can pair a credible, sustainable new dividend with a stabilizing NAV. A cut that lands near the $0.67 earnings run rate alongside steady marks and buyback action would let the stock reset on firmer ground. Another leg down in book value would suggest the decline in earnings power still has further to run.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 5 hours | |
| Oct-15 | |
| Aug-13 | |
| Aug-06 | |
| Jul-16 | |
| Jun-08 | |
| Jun-05 | |
| May-07 | |
| May-07 | |
| Apr-22 |
A Moment of Truth: Which Private-Credit Funds Believe Their Own Balance Sheets?
BXSL
The Wall Street Journal
|
| Apr-20 | |
| Mar-24 | |
| Mar-24 | |
| Mar-18 | |
| Mar-14 |
