Blackstone Secured Lending Edges Past NII Estimates, But A Dividend Reset To $0.60 Defines The Quarter
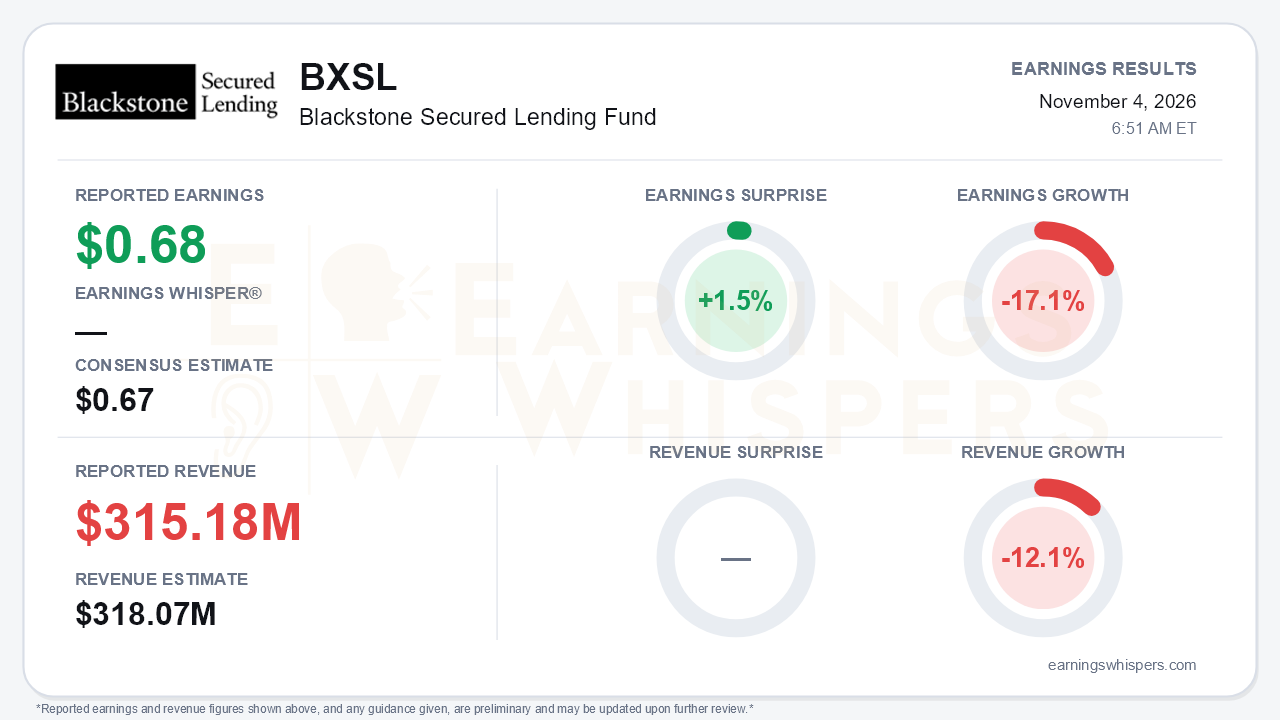
Blackstone Secured Lending Fund (NYSE: BXSL) reported third-quarter net investment income of $0.68 per share. That beat the $0.67 consensus by 1.5%, but it was down 17.1% from a year ago. Revenue of $315.18 million missed the $318.07 million consensus by 0.9% and fell 12.1% year over year. The penny beat is the least important number in the report. The central development is that management made the long-telegraphed dividend reset concrete. The $0.77 quarterly payout holds for the fourth quarter and then drops to $0.60 beginning in the first quarter of 2027, roughly a 9.5% yield on NAV. The press release mentions only the $0.77 declaration and a 10.7% annualized NII yield on NAV. The cut emerged on the call.
The earnings trajectory explains why the reset was unavoidable. NII per share has declined in four straight quarters, from $0.80 in Q4 2025 to $0.77, $0.75 and now $0.68. Management attributed the latest step down to a smaller incentive-fee lookback benefit. With the $0.77 dividend running well ahead of current earnings, undistributed earnings have been drawn down from $1.80 per share in Q1 to $1.77 in Q2 and $1.68 now. The cushion has funded a bridge, which management had flagged as temporary on the Q1 and Q2 calls. That bridge now has an end date. NAV per share continued to erode, falling to $25.25 from $25.53 in Q2 and $26.92 at the end of 2025. About $1 per share of realized losses was tied to the Medallia restructuring.
Beneath the income pressure, the credit picture improved more than the headline suggests. Last-twelve-month portfolio EBITDA growth accelerated to about 10% from 7% in Q2, and interest coverage has held above 2x for five quarters. PIK income fell to 5.8% of the total from 6.6% in Q2 and more than 8% in Q4 2025. Software, about 19% of fair value, strengthened: coverage rose to 2.3x and weighted EBITDA topped $290 million. Non-accruals at cost dropped to 2.8% from 3.6% in Q2 and 4.7% in Q1. The quality of that improvement deserves scrutiny, though. Much of it reflects Medallia exiting non-accrual through a restructuring that crystallized losses. Meanwhile, three new names were added, pushing non-accruals at fair value up to 2.1% from 1.8%. Credit is healing at the borrower level, but the bad loans did not disappear without cost.
The bigger structural problem is a shrinking earning base and a rising cost of funding. The portfolio has contracted to $12.9 billion from $14.2 billion at the end of 2025. New fundings were just under $250 million against more than $550 million of repayments, versus $1 billion of fundings in Q4. Leverage slipped to 1.22x from 1.28x. Second-half M&A proved slower than the 'very constructive' backdrop management described in Q2, with higher rates and the election weighing on activity. The Fed's resumption of rate hikes should lift floating-rate income. However, management expects that benefit to be offset by refinancing about $3.2 billion of 2020-21 fixed-rate notes carrying a 2.97% coupon, with $650 million maturing in Q1 2027. All-in debt cost has already climbed to 5.14% from 4.90% in Q1.
The forward catalysts are real but back-end loaded. M&A advisors' financing requests are up roughly 30% from two to three months ago, and management expects deal flow to reaccelerate in the first half of 2027. New investments are yielding about 9% versus mid-to-high 8s on repayments, with spreads 25-50 basis points wider than a year ago. The revolver was upsized to about $2.5 billion and extended to 2031 at S+153. The Audax sale of Genuine Cable Group to Rexel produced a roughly $10.5 million unrealized equity gain. Management said it is open to joint ventures, M&A or equity issuance to rebuild scale. With shares trading below NAV, though, issuance is a harder lever to pull, and no buybacks were executed despite the discount. With 28% of assets maturing in 2027-28, BXSL needs origination to recover simply to hold its portfolio steady.
Investor sentiment shifted meaningfully into the report, moving from -0.22 after the prior quarter to +0.12. That suggests the market had largely absorbed the dividend risk and was warming to the credit improvement. Price action has been less forgiving. At $23.22 ahead of the release, shares were down 1.4% since the open after the August report. They sat 3.7% below the $24.12 200-day moving average, 9% below the September 17 high of $25.52, and just 1.8% above the October 26 low. The Earnings Whispers price, momentum and AVWAP trend readings remain negative, consistent with a stock that has drifted toward the bottom of its range.
The bottom line is that BXSL delivered a nominal beat inside a clearly decelerating earnings stream, and the quarter's defining event is the 22% dividend reset. Borrower fundamentals, PIK and cost-basis non-accruals are moving in the right direction, and management's tone was more confident than during the stressed first half. Bears still have legitimate ammunition: four straight quarters of NII decline, ongoing NAV erosion, rising fair-value non-accruals, a shrinking portfolio and a funding-cost headwind that neutralizes higher rates. The credible path forward depends on a 1H27 origination rebound that has not yet shown up in the numbers.
Read our earnings preview for Blackstone Secured Lending Fund: https://www.earningswhispers.com/article/BXSL/21684
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| 14 hours | |
| Oct-28 | |
| Oct-27 | |
| Oct-15 | |
| Aug-13 | |
| Aug-06 | |
| Jul-16 | |
| Jun-08 | |
| Jun-05 | |
| May-07 | |
| May-07 | |
| Apr-22 |
A Moment of Truth: Which Private-Credit Funds Believe Their Own Balance Sheets?
BXSL
The Wall Street Journal
|
| Apr-20 | |
| Mar-24 |
