Peabody Needs Centurion And PRB Recovery To Deliver Its Promised Swing Back To Profit
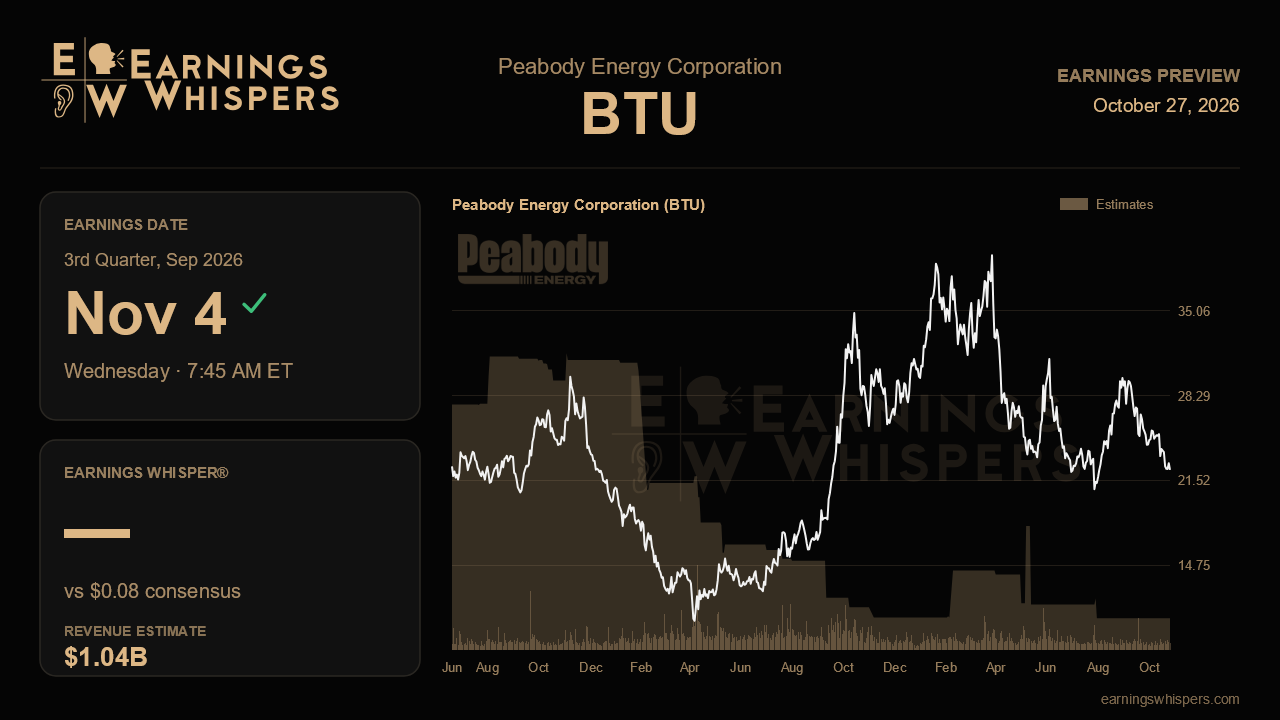
Peabody Energy heads into its third-quarter report with a problem that pricing alone has not been able to fix. Seaborne coal markets have been about as friendly as a producer could ask for, yet consolidated adjusted EBITDA has fallen for three straight quarters, bottoming at just $24 million last quarter, a figure management itself said was nowhere near what the platform should earn. The report due before the open on November 4 will show whether that was the low point or simply another step down.
Wall Street is betting on a turn. Consensus calls for earnings of $0.08 per share on revenue of roughly $1.04 billion. That would be a sharp reversal from last quarter's loss of $0.74 and from the $0.58 loss in the same period a year ago, which is why the expected growth rate looks so dramatic at nearly 114%. The top line tells a quieter story: revenue is expected to rise only about 3% from a year earlier. In other words, the Street is not forecasting a volume boom. It is forecasting that costs come down and production problems stop eating the benefit of higher prices.
The biggest swing factor is Centurion, the new metallurgical coal mine that was supposed to anchor Peabody's growth. Its full-year sales target has already been cut from 3.5 million tonnes to 2.5 million, and management's earlier assurance that the trouble was mostly a second-quarter issue did not hold up. For the third quarter, the company guided to only 0.5 to 0.7 million tonnes, about 150,000 of which comes from continuous miner coal, while a rock-faulting zone spanning roughly a fifth of the longwall face was expected to persist through the period. Hitting the top of that range, and offering credible evidence that the faulting is behind the longwall, would validate management's insistence that the mine can still reach 4.7 million tonnes at competitive costs. Landing at the bottom, or disclosing new geological or equipment problems, would further strain credibility after repeated slippage.
Costs in the seaborne met segment are the second test. Per-tonne costs climbed from an original target near $113 to $142 in the first quarter and $155 in the second. Without meaningful improvement here, the strong benchmark pricing of recent months will keep leaking away. The US thermal business offers a cleaner opportunity. After a wet, extended shoulder season held Powder River Basin shipments to 16.4 million tonnes at $14 per tonne, management guided to 22 million tonnes at about $12. That was the one guidance item that moved in the right direction, so a miss there would be hard to excuse. Diesel is a lingering headwind, with every $10 per barrel move worth roughly $6 million of quarterly EBITDA.
The bright spot remains seaborne thermal, which earned $52 million at a 23% margin last quarter on realized prices near $96 per tonne. Sustaining that contribution matters, especially because first-half shareholder returns exceeded free cash flow and leaned on the $350 million restricted cash release. Updates on the rare earth grant and germanium work add optionality but will not move near-term numbers.
Expectations have warmed modestly. Sentiment has edged into slightly bullish territory from mildly bearish before the last report, and the shares are up about 4% since then, a touch ahead of the S&P 500. Still, at $22.36 the stock sits well below its 200-day moving average of $28.35 and near the lower end of its post-earnings range, suggesting the market remains skeptical. The verdict hinges on whether Centurion and the PRB finally convert strong coal prices into earnings, proving last quarter was a trough rather than a new baseline.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| Oct-20 | |
| Sep-26 | |
| Sep-16 | |
| Aug-13 | |
| Aug-11 | |
| Jul-29 | |
| Jul-29 | |
| Jul-29 | |
| Jul-27 | |
| Jul-15 | |
| Jul-09 | |
| Jul-07 | |
| Jul-07 | |
| Jun-30 |
