Peabody's Seaborne Pricing Rescues EBITDA, But Another Centurion Setback Drives A GAAP Miss And Broad Volume Cuts
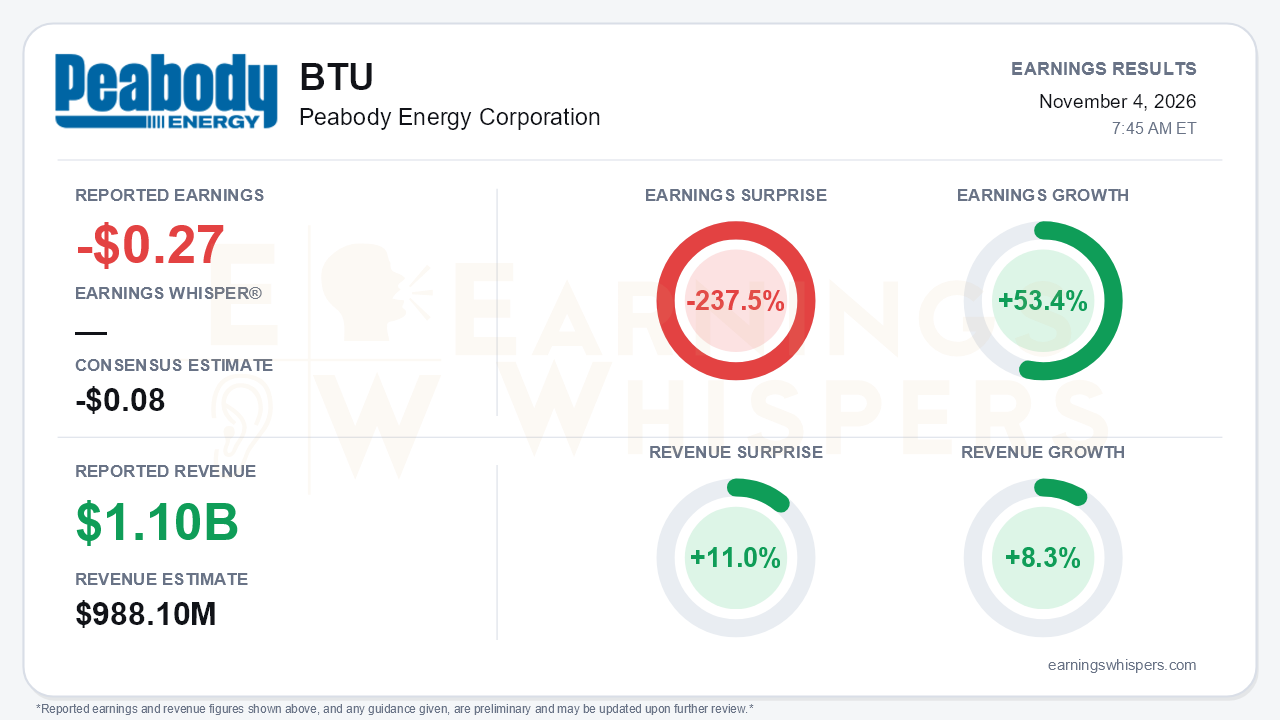
Peabody Energy (NYSE: BTU) reported a third-quarter loss of $0.27 per share, well short of the consensus estimate for a $0.08 loss, a 237.5% negative surprise. Revenue of $1.096 billion beat the $988.1 million consensus by 11.0% and grew 8.3% year over year. The loss also narrowed sharply from $0.58 a year earlier, which registers as 53.4% earnings growth. The central tension is clear. Strong seaborne coal prices are rebuilding Peabody's earnings power faster than expected, while Centurion, the mine meant to carry the growth story, keeps moving the goalposts.
The operating recovery was real. Adjusted EBITDA reached $97.5 million, up from $24.0 million in the second quarter, and all four segments turned positive. Seaborne Thermal led the improvement, with EBITDA up 26% sequentially and 60% year over year to $65.5 million. Realized export prices topped $100 a ton, and margin per ton rose to $21.05. Seaborne Metallurgical swung to $5.2 million of positive EBITDA as realized pricing rose nearly $17 a ton.
The quality of the quarter deserves scrutiny, however:
- **Thin met margins.** The met segment's margin was just $2.38 a ton, because costs of $162.45 ran above company expectations on Centurion's faulted conditions.
- **Weak cash generation.** Operating cash flow was negative $1.4 million.
- **Shrinking cash balance.** Cash fell to $434 million from $575 million at year-end.
- **Noise in the GAAP figure.** The loss included a $12.9 million other operating loss, a $3.3 million induced-conversion charge, and higher interest expense tied to debt-discount amortization. These were partly offset by a $7.2 million derivative mark-to-market gain and pension credits.
Centurion is where the story weakened. The mine shipped 0.58 million tons and hit its third-quarter target. Late in the quarter, however, the longwall ran into multiple complex faults across the panel, and October production was only about 45,000 tons. Fourth-quarter sales guidance is now 0.3 to 0.5 million tons. The credibility problem is cumulative:
- Last year's outlook called for 3.5 million tons from Centurion in 2026.
- That was cut to 2.5 million tons in the first quarter.
- In the second quarter, management targeted 1.5 to 2.0 million tons for the second half and said the faulting would be cleared in the third quarter.
- A consistent run rate is now deferred until after the next longwall move in the third quarter of 2027.
Management withheld 2027 guidance but said it is "100% confident" Centurion will reach full capacity. It has identified engineering fixes: a base-lift power upgrade costing $1.5 to $2 million and a two-stage flipper costing $5 to $10 million. The tone has shifted from describing a mine in its production phase to defending its long-term capacity.
The guidance revisions were broad and mostly negative:
- **Metallurgical:** full-year volume cut by 0.6 million tons, with costs raised about $15 a ton.
- **Powder River Basin:** volume cut by roughly 7.5 million tons and costs raised $1 a ton, on weak U.S. coal burn and a customer outage. Management had called the prior PRB midpoint achievable just one quarter earlier.
- **Other U.S. Thermal:** volume cut by 0.2 million tons.
- **Seaborne Thermal:** export volume raised by 0.2 million tons, the only increase.
- **Capital spending:** reduced by $40 million, largely by deferring Centurion North development. That helps cash flow but signals a slower ramp.
The brighter part of the outlook is seaborne thermal, where fourth-quarter costs are guided to $46 to $51 a ton on 3.6 to 3.8 million tons of volume.
The catalyst list is longer than the near-term numbers suggest:
- **Met coal market:** premium hard coking coal averaged $248 a ton in the quarter, up 35% year over year. Chinese supply cuts of roughly 70 million tons are expected to keep seaborne met supply tight into 2027.
- **China demand:** China has committed to importing at least 11 million tons of U.S.-origin coal, mostly coking coal, in 2027 and 2028.
- **Centurion customers:** the mine delivered its first cargo to an Indian public-sector steelmaker.
- **Other options:** a germanium offtake and processing deal is described as nearing completion, the R3 solar joint venture could earn success fees from 2027, and EPA regulatory rollbacks are under way. Mine-mouth generation for Wyoming data centers remains early-stage.
Bears have legitimate ammunition as well. Data-center demand has not yet produced meaningful coal purchases. Wilpinyong export volume is expected to fall 0.5 to 0.7 million tons in 2027.
The market setup is unforgiving. At $20.66 heading into the report, shares were 3.5% below the open after the prior earnings release, 26.2% below the 200-day moving average of $27.98, and 32.1% below the August 31 inter-earnings high of $30.41. The stock sat just 3.0% above the 52-week low of $20.06, set the day after last quarter's report. Investor sentiment improved modestly, from slightly negative to slightly positive. That is a small shift, not a vote of conviction. The Earnings Whispers trend signals remain mostly negative, with price, momentum, and AVWAP readings all weak.
The bottom line is that Peabody's pricing leverage is working, and seaborne thermal is carrying more of the load than expected. But the quarter's most important development is another Centurion reset, with steady output now pushed into late 2027 and no 2027 guidance offered. Until the mine delivers on a guided number, strong benchmark prices are likely to be weighed against eroding execution credibility and thin cash generation.
Read our earnings preview for Peabody Energy Corporation: https://www.earningswhispers.com/article/BTU/21682
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Oct-27 | |
| Oct-20 | |
| Sep-26 | |
| Sep-16 | |
| Aug-13 | |
| Aug-11 | |
| Jul-29 | |
| Jul-29 | |
| Jul-29 | |
| Jul-27 | |
| Jul-15 |
