Emerson's Fiscal Finale Tests Whether Semiconductor And Power Strength Can Carry Into 2027
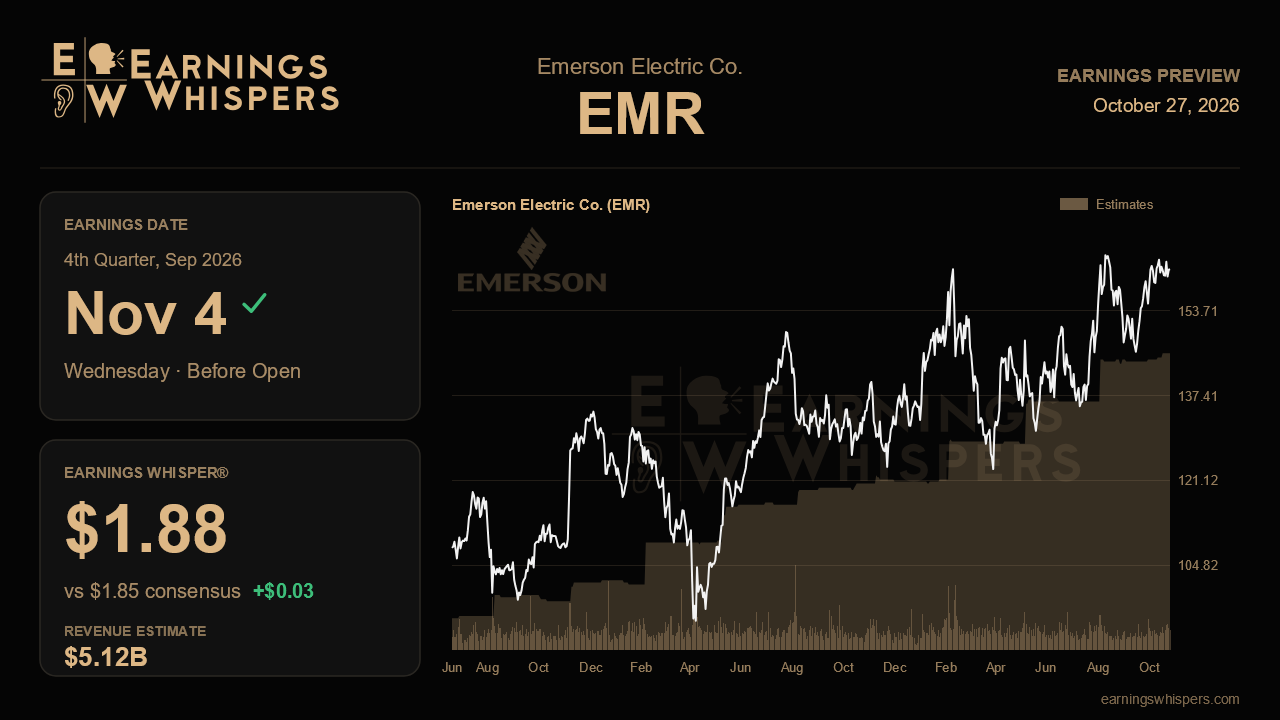
Emerson heads into its fiscal fourth-quarter report with a rare combination: a guidance figure that already matches the Street almost to the penny, and a stock that has drifted toward the top of its post-earnings range on growing optimism. That leaves little room for a simple beat to move the needle. The real question on November 4 is whether the reacceleration Emerson showed last quarter, powered by semiconductor and power customers, is durable enough to support a confident first look at fiscal 2027.
Analysts expect adjusted earnings of $1.85 per share on revenue of about $5.12 billion, which would represent roughly 14% earnings growth and 5.5% sales growth from the year-ago quarter's $1.62 and $4.86 billion. Management's own outlook calls for about $1.85 on $5.10 billion, so consensus sits squarely on top of guidance, with only a sliver of extra revenue baked in. The math also ties out with the full-year target of roughly $6.55, implying the fourth quarter has to deliver about what the first three quarters' $4.71 leaves behind. The earnings whisper of $1.88 sits modestly above consensus, a hint that some investors expect Emerson to repeat its habit of clearing the top of its range, as it did when third-quarter earnings of $1.71 exceeded guidance.
That third-quarter report changed the tone of the story. After a second quarter dominated by Middle East disruption, underlying sales growth jumped to 6% from barely half a percent, orders rose 7% across every group, and segment EBITDA margin expanded 140 basis points to 28.5%. Growth verticals climbed 27%, with semiconductor up 53% and power up 37%, while test and measurement revenue rose 23%. Management raised its full-year outlook for sales, earnings, free cash flow and several segments, and the project funnel swelled by $1.2 billion to $12.4 billion, including $3.0 billion in power and $2.2 billion in LNG. Validating that narrative this quarter means another solid orders print, continued strength in test and measurement toward the raised 14% growth target, and evidence that wins such as the 2.1 gigawatt CFE Mexico retrofit and the Hualong-1 nuclear valve award are converting the funnel into backlog rather than sitting as future promise.
The risks are known but not resolved. Management expected roughly another $25 million Middle East revenue hit in the fourth quarter, with the Strait of Hormuz effectively closed and customer capacity around 75%, and did not see that turning into a tailwind until perhaps the second half of fiscal 2027. China was still down 3%, though improving, Europe slipped 1% on weak automotive demand, and safety and productivity grew just 2%. Software and systems margin also dipped on renewal and project mix. A wider Middle East impact, a stall in China's sequential recovery or further margin slippage in software would challenge the idea that the second-quarter shock is fully absorbed.
Expectations have clearly warmed. Sentiment readings have climbed to solidly bullish from roughly neutral heading into the prior report, and the stock has gained 2.8% since then while the S&P 500 fell 1.4%. At $161.70, shares trade about 10% above their 200-day moving average and within 3% of the post-earnings high of $166.35, so a convincing outlook could push the stock toward a breakout, while a merely in-line quarter may not be enough to get it there.
Because this report closes the fiscal year, it should also bring Emerson's initial view of fiscal 2027, just as last year's fourth-quarter report delivered the first $6.35 to $6.55 range that management later lifted twice. That outlook is the central issue. If Emerson frames 2027 around sustained orders momentum in power, LNG and semiconductor test, with the Middle East as an eventual upside rather than a lingering drag, the beat-and-raise narrative stays intact. A cautious initial range would suggest the past quarter's acceleration was more catch-up than trend.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-20 | |
| Oct-16 | |
| Oct-14 | |
| Oct-14 | |
| Oct-14 | |
| Oct-13 | |
| Oct-09 | |
| Oct-08 | |
| Oct-07 | |
| Oct-02 | |
| Oct-01 | |
| Oct-01 | |
| Sep-30 | |
| Sep-28 |
