Emerson Falls Short Of The Whisper, But 14% Order Growth And A $7.25 Outlook Strengthen The Fiscal 2027 Case
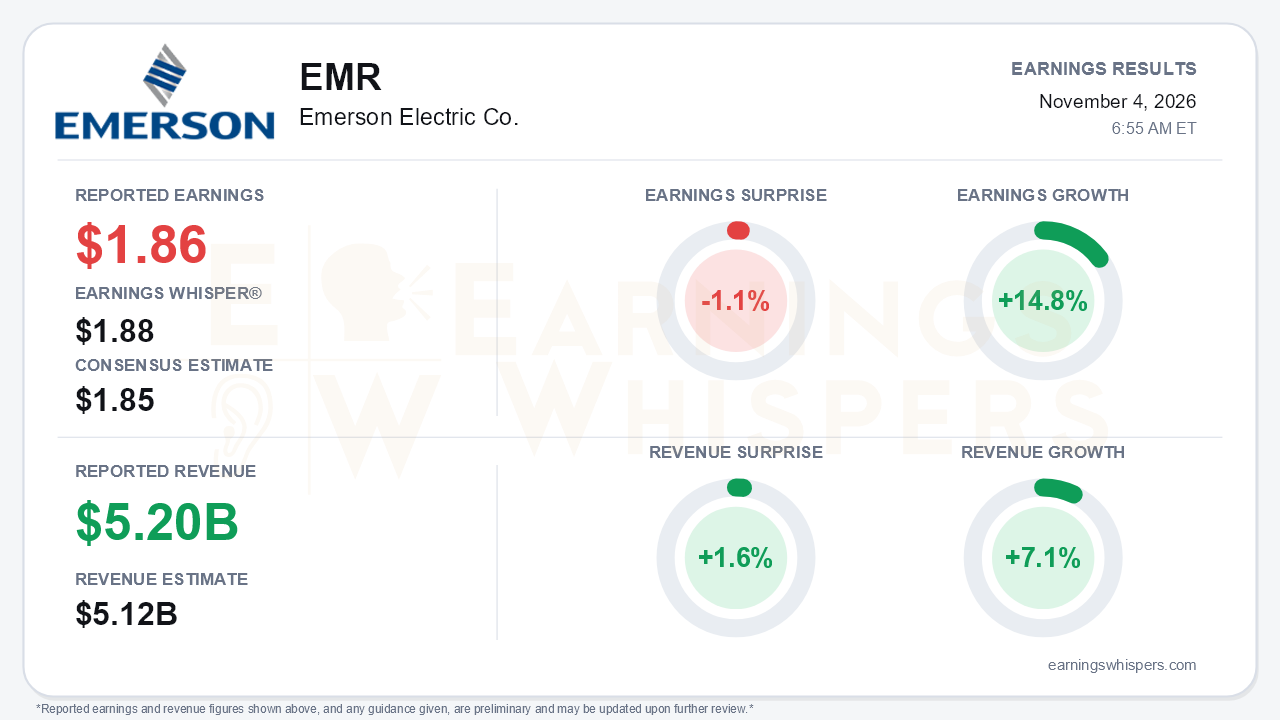
Emerson's fiscal fourth quarter produced a narrow earnings miss alongside a much stronger forward signal. Adjusted EPS of $1.86 edged past the $1.85 consensus but fell short of the $1.88 Earnings Whisper, a 1.1% shortfall against the number investors actually wanted. Revenue of $5.201 billion beat consensus by 1.6%. Earnings grew 14.8% year over year on 7.1% revenue growth, well ahead of the full-year pace of 10% adjusted EPS growth and 4% underlying sales growth. The more important number was not on the income statement. Underlying orders rose 14%, accelerating from 7% in the third quarter and 5% in the second. That is the central tension: the quarter barely cleared the bar, but the demand picture improved sharply.
The operating results were stronger than the earnings surprise implies. Total adjusted segment EBITA margin expanded 160 basis points to 29.1%, above management's 28.5% guide. Software & Systems carried the quarter, with 14% underlying growth and adjusted EBITA margin rising to 32.3% from 27.4%. Control Systems & Software reached 33.1%. GAAP EPS rose to $1.33 from $1.07. Two items held the adjusted figure to roughly the guided ~$1.85. First, the income tax line rose to $253 million from $152 million despite only moderately higher pretax earnings. Second, the call pointed to corporate costs running about $45 million above plan because of an impairment and other one-off items. Adjusted corporate and other expense rose to $81 million from $34 million. Investors should also note that GAAP results include IEEPA tariff refunds. Management excludes these from adjusted EPS, a $0.12 benefit for the full year, so the adjusted figures are not flattered by them.
The call strengthened the growth story, though the gains were concentrated. Software & Systems orders grew 18%, Middle East orders 42%, semiconductor 59%, and Ovation 26%. Growth verticals rose 25% in sales, including a 68% jump in LNG. The project funnel climbed to $13 billion from $12.4 billion last quarter and $11.1 billion in the first quarter. Emerson won about $575 million in the quarter, including a Qatar ethylene cracker and LNG Canada Phase 2. Backlog reached $8.2 billion, up 11% from a year earlier versus 7% growth last quarter. The breadth has limits. Intelligent Devices grew only 4% underlying and Safety & Productivity 2%. Europe managed just 1% in the quarter and declined 1% for the year. Management assumes no recovery in Europe or China.
Guidance for fiscal 2027 calls for:
- roughly 5% underlying growth;
- a 29% segment margin, up 80 basis points;
- adjusted EPS of about $7.25, up 10%;
- free cash flow of $3.8-$3.9 billion.
Capital return is the clearest upgrade. Buybacks rise to about $2.5 billion from $1 billion in fiscal 2026, with $1.5 billion in the first quarter alone, and the dividend increases 7% to $0.595. Earnings Whispers characterizes the outlook as above estimates. Still, a 5% growth guide against 14% order growth looks deliberately cautious, and bears have some legitimate ammunition:
- The share of backlog shippable within 12 months fell to about 70% from 75%, so the new orders are longer-dated.
- Software & Systems is guided to 7-8% growth after 14% in the fourth quarter.
- Management models a semiconductor slowdown in the second half of fiscal 2027.
- Pricing is expected to normalize to about 2%, while memory and electronics costs are inflating.
- First-quarter margin is guided to 28%, below the full-year target, reflecting mix and startup costs.
- About $25 million of incremental IT and AI spending is planned.
- Fiscal 2026 free cash flow of $3.535 billion landed at the low end of guidance and below the roughly $3.6 billion figure cited last quarter.
- The Middle East outlook assumes the regional conflict does not escalate.
The market setup explains why a penny beat over consensus may not have been enough. Shares entered the report at $166.39, up 5.8% since the open after the August report and about 13% above the 200-day moving average. The stock sat 2.8% below a 52-week high of $171.25 set on October 29 and more than 15% above its September low. Investor sentiment became meaningfully more positive, rising from roughly neutral at 0.04 to 0.23. That is constructive, not euphoric. Earnings Whispers trend signals were mostly positive heading into the print, consistent with a stock that had already priced in a solid quarter. With shares near their highs, the whisper shortfall matters more than it otherwise would.
The bottom line is that Emerson delivered an in-line-to-slightly-light earnings quarter wrapped around a materially better demand story. Accelerating orders, a growing funnel, higher margins, and a much larger buyback give fiscal 2027 guidance a credible foundation, and arguably leave room for upside. The miss against the whisper, longer-dated backlog, weak Europe and China, and a softer first-quarter margin argue that the payoff from the order surge will arrive gradually rather than immediately.
Read our earnings preview for Emerson Electric Co.: https://www.earningswhispers.com/article/EMR/21696
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Oct-27 | |
| Oct-20 | |
| Oct-16 | |
| Oct-14 | |
| Oct-14 | |
| Oct-14 | |
| Oct-13 | |
| Oct-09 | |
| Oct-08 | |
| Oct-07 | |
| Oct-02 |
