Dine Brands Needs Applebee's To Stop Sliding As Company-Owned Bet Squeezes Cash
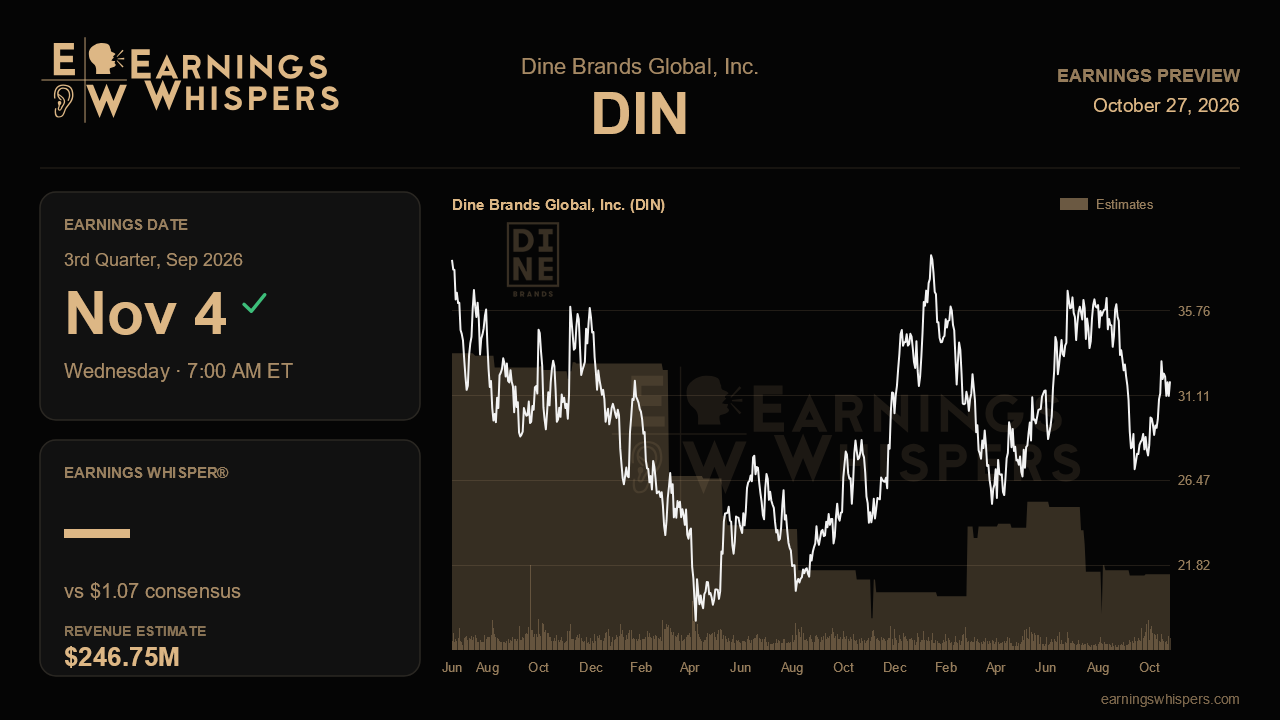
Dine Brands heads into its third-quarter report with two brands moving in opposite directions and a balance of cash flow that has thinned considerably. IHOP has climbed from negative comparable sales a year ago to a 1.5% gain last quarter, while Applebee's, the larger profit engine, slipped to a 1.8% decline. Layer on a company-owned restaurant base that nearly doubled in six months and first-half adjusted free cash flow of just $3.7 million versus $48.7 million a year earlier, and the November 4 release becomes less about the headline numbers and more about whether management's turnaround spending is starting to pay for itself.
The Street is looking for earnings of $1.07 a share on revenue of $246.8 million, which would mean growth of roughly 47% and 14%, respectively, from the year-ago quarter's $0.73 and $216.2 million. Those are big jumps, but context matters. Much of the revenue lift reflects the 48 Applebee's units acquired in June, which swell company restaurant sales without carrying franchise-level margins. The EPS bar also sits below last quarter's $1.16, so analysts are already allowing for some sequential softening. Management reaffirmed full-year guidance last quarter but steered toward the lower end, a defensive posture that leaves little cushion if Applebee's keeps sagging.
Applebee's is the swing factor. Its comps decelerated from 3.1% to 1.9% to negative 1.8% over three reported quarters, partly because of a tough April comparison against last year's Sizzlin' Skillets promotion, and management pointed to sequential improvement in May and June. If that was a calendar quirk, third-quarter comps should drift back toward flat or positive. A second negative quarter would suggest the problem is the value-seeking consumer, whom management flagged as squeezed by gas prices and menu inflation. Off-premise sales are worth watching too; that growth has faded from 9% to 1.5%, and further erosion would remove a key support. Meanwhile the operational scorecard, including higher Google ratings, more manager table visits and mid-single-digit lifts from remodels, needs to begin showing up in traffic, not just guest reviews.
On the bullish side, IHOP's run of outperformance against the casual dining benchmark and the strength of the Dubai Chocolate Pancakes promotion give it a chance to post a fourth straight quarter of beating peers. Dual-brand conversions, averaging about twice single-brand sales, are the cleanest growth story here. Management targeted 80 by year-end from 45 open at midyear, so a meaningful jump in the count this quarter would validate the pace; a stall would raise doubts.
Margins are where the pressure concentrates. Beef pushed Applebee's commodity inflation to 8.2% last quarter, general and administrative expense climbed on severance and acquisition costs, and the company-owned portfolio, which lost about $10 million in EBITDA last year, now sits at 136 restaurants. Annualized cost savings of more than $12 million help, but adjusted EBITDA has already slipped below year-ago levels. Evidence that capital spending and franchisee incentives are peaking, letting free cash flow recover, would ease concerns about the new $100 million buyback authorization.
Sentiment is decidedly bearish and essentially unchanged from the prior quarter, and the stock has slipped about 2% since the last report, roughly in line with a weaker market. At $31.89 it sits just above its 200-day average and near the middle of a wide $26.73 to $37.23 range, signaling indecision rather than conviction. That leaves room for a relief move if results surprise. Ultimately the report hinges on one question: did Applebee's stabilize after its spring stumble? If it did, IHOP's momentum and dual-brand growth can carry the story; if not, the heavier company-owned footprint looks less like an investment and more like a burden.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 6 hours | |
| Oct-14 | |
| Oct-12 | |
| Sep-21 | |
| Sep-15 | |
| Sep-15 | |
| Sep-14 | |
| Sep-09 | |
| Sep-04 | |
| Sep-04 | |
| Aug-31 | |
| Aug-20 | |
| Aug-05 | |
| Aug-05 | |
| Aug-05 |
