Dine Brands Misses Badly, Pins Guidance To The Low End As A Rejected Takeover Bid Takes Center Stage
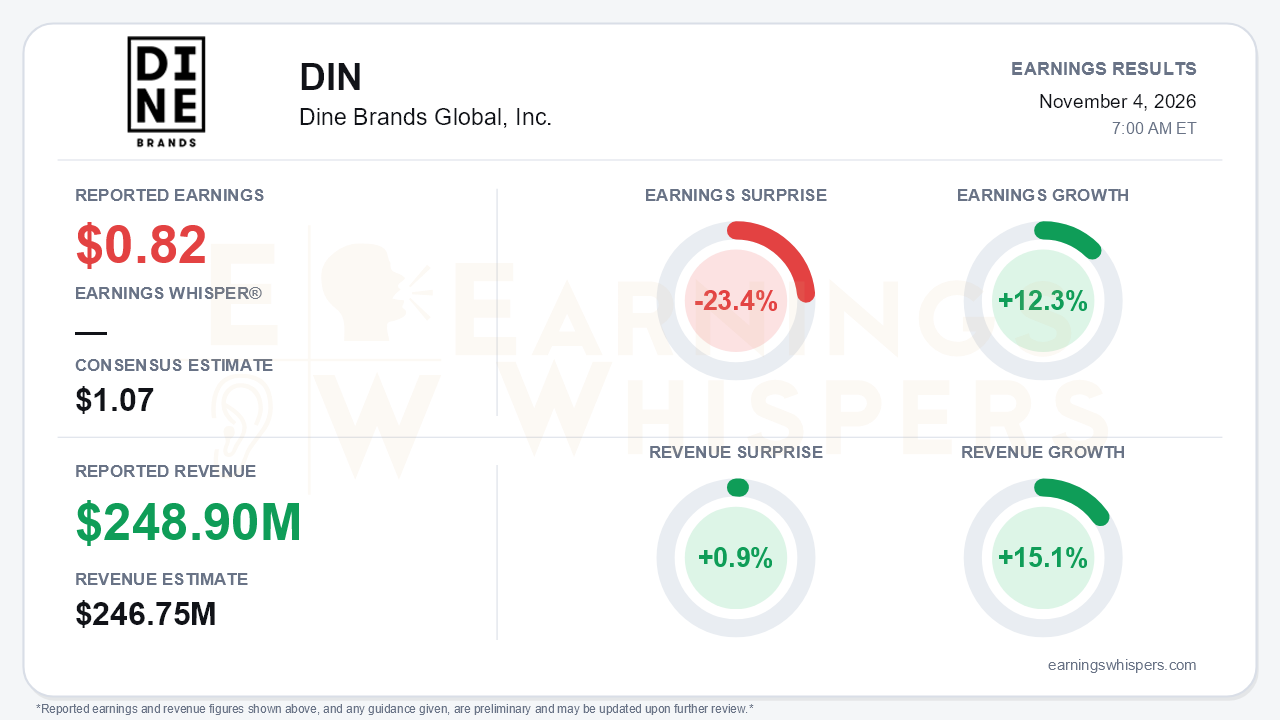
Dine Brands Global (NYSE: DIN) delivered a third quarter that looks better in the year-over-year columns than against expectations. Adjusted earnings of $0.82 per share rose 12.3% from a year ago but missed the $1.07 consensus by 23.4%. Revenue of $248.9 million beat estimates by 0.9% and grew 15.1%. The revenue beat and the EPS growth both rest on mechanics rather than organic strength, and that is the central tension. Revenue was lifted by a $36.9 million jump in company-owned restaurant sales after Applebee's acquisitions. Per-share earnings were flattered by a diluted share count that fell from 14.4 million to 12.2 million. On top of that, the quarter was overshadowed by an unsolicited takeover offer that the board rejected as inadequate, followed by adoption of a stockholder rights plan.
The quality of the quarter deserves scrutiny. Adjusted net income actually slipped to $10.1 million from $10.5 million. GAAP EPS fell to $0.37 from $0.48, and pretax income dropped to $6.7 million from $10.0 million. Adjusted EBITDA was flat at $49.0 million, extending a run of year-over-year declines or stagnation:
- Q1: $50.8 million vs. $54.7 million
- Q2: $54 million vs. $56 million
- Q3: $49.0 million, unchanged
Gross profit was essentially unchanged at $84.7 million despite $33 million of added revenue. The reason is the company-owned business. It generated $64.4 million in sales against $66.4 million in restaurant expenses, so it is losing money at the restaurant level. Meanwhile, the high-margin franchise base is shrinking. Royalty and fee revenue fell to $91.7 million, total franchise revenue dropped about 1.5%, and rental income slid on closures and sublease exits. Cash generation is the bigger concern. Nine-month adjusted free cash flow was just $12.8 million versus $68.2 million a year ago, while the company still spent $35.9 million repurchasing stock.
The call offered genuine operating progress, though it was uneven:
- **Applebee's comps:** swung to +0.9% from -1.8% in the second quarter.
- **IHOP comps:** decelerated to +0.8% from +1.5%. IHOP did post its seventh straight quarter of traffic outperformance versus the industry, and its off-premise comp accelerated to +5.6% from +3.5%, with catering up 44%.
- **Traffic:** negative at both brands, so the comp gains lean on pricing and mix. Applebee's 2-for-$25 trade-up rate rose to 68.5% from 61%.
- **Costs:** Applebee's faces 5.4% commodity inflation, partly offset by annualized supply-chain savings that climbed to $22 million from $12 million in Q2.
- **Investment programs:** Applebee's completed 107 remodels year to date, beating its 100 target. Dual-brand units rose to 60 from 45 in Q2, and management called the 2027 pipeline the strongest in the CEO's six years. However, the expected sales lift from conversions was framed at 1.5-2x, down from 1.5-2.5x earlier.
Guidance is where the erosion is clearest. The adjusted EBITDA target of $220-230 million has drifted lower each quarter, from maintained to "maybe toward the lower end" to now explicitly the low end. Hitting even $220 million implies roughly $66 million of fourth-quarter EBITDA. That compares with $49 million in Q3 and $154 million through nine months. The stretch looks harder because management said Applebee's began the fourth quarter soft, after a weak September promotion and two dark TV weeks in August. The company-owned segment is still expected to post a Q4 EBIT loss, undercutting the breakeven goal set earlier in the year. Management is now pivoting to refranchising, citing inbound franchisee interest and saying there is no reason to take back more units. That is a sensible retreat, but it is a retreat. The NFL partnership was also de-emphasized after weaker returns.
The forward catalysts are now largely corporate:
- **Takeover interest:** the rejected bid establishes that outside capital sees value in the asset-light franchise model, even if the board wants more.
- **Refinancing:** the $500 million Series 2023 notes become callable at par in December. That matters for a company carrying about $1.19 billion in long-term debt, rising interest expense, and a $293 million stockholders' deficit.
Investor sentiment was essentially unchanged and remains negative, near -0.35. Skepticism toward the fundamentals has not eased even as the share price climbed. Shares closed at $35.31 before the report, up 8.3% since the open after the August release and 11.6% above the 200-day moving average of $31.64. The stock rallied 32% from its September 15 low of $26.73 to an October 28 high of $37.76, then entered earnings about 6.5% below that peak. Sequential growth and AVWAP readings are positive, while price and momentum readings sit at neutral. That pattern fits a stock carried by event-driven interest rather than improving estimates.
The bottom line is that Dine Brands' operating story is stabilizing at the margins, while its financial story keeps weakening. Comps turned positive, remodels and dual-brand openings are ahead of plan, and supply savings are compounding. But a 23.4% EPS miss, flat EBITDA, collapsing free cash flow, and guidance pinned to a demanding low end give bears legitimate ammunition. With sentiment still negative and the stock near the upper part of its recent range, the setup now depends heavily on whether takeover interest and the December refinancing can outweigh a fourth quarter that has already started soft.
Read our earnings preview for Dine Brands Global, Inc.: https://www.earningswhispers.com/article/DIN/21695
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 4 hours | |
| 14 hours | |
| 15 hours | |
| 15 hours | |
| Nov-02 | |
| Nov-02 | |
| Oct-30 | |
| Oct-30 | |
| Oct-30 | |
| Oct-29 | |
| Oct-27 | |
| Oct-14 | |
| Oct-12 | |
| Sep-21 | |
| Sep-15 |
