Freshpet Must Prove Record Margins And Raised Outlook Can Survive A Tough Third-Quarter Comparison
Freshpet heads into its third-quarter report with an unusual mismatch between what management has been saying and what Wall Street has penciled in. Last quarter the fresh pet food maker delivered its fastest sales growth in more than a year, its best adjusted gross margin since early 2020, and a third straight increase to its full-year sales outlook. Yet the consensus forecast for this quarter implies a sharp slowdown in revenue growth and a meaningful drop in earnings. The report on November 4 should reveal which of those two stories is closer to the truth.
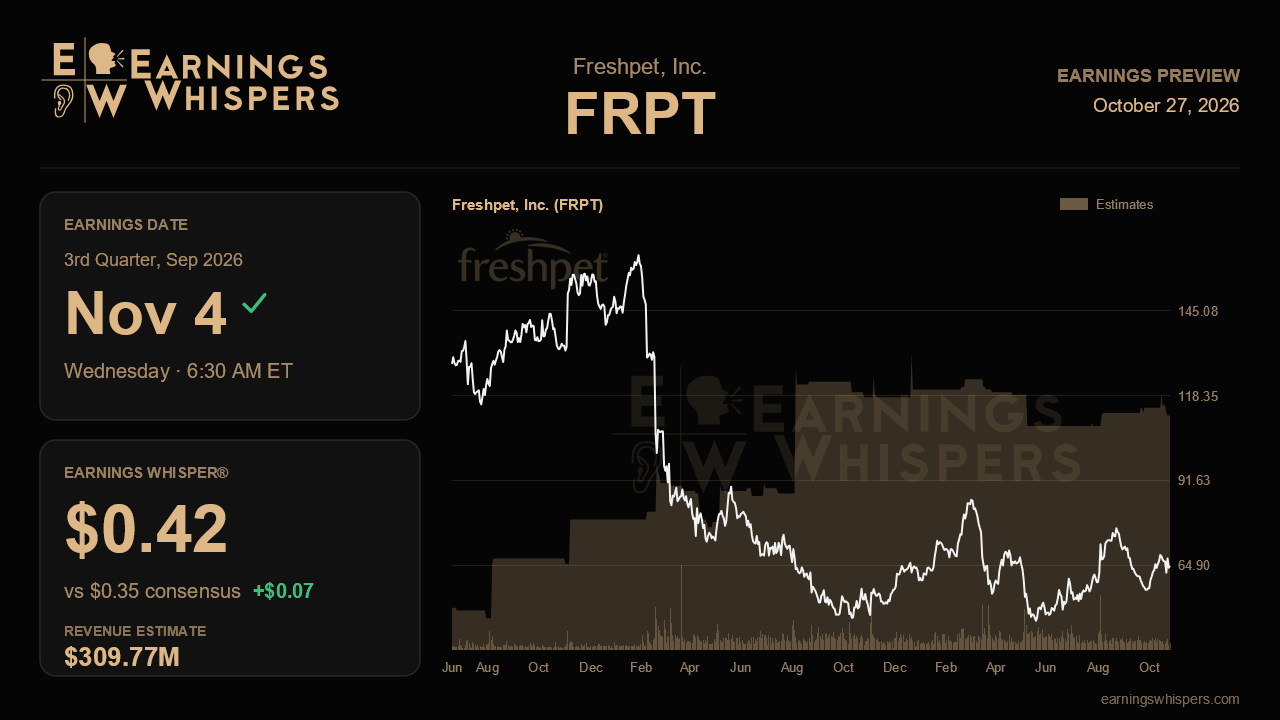
Analysts expect earnings of $0.35 per share on revenue of about $309.8 million. That would mean sales up roughly 7.2% from the year-ago $288.8 million, less than half the 15.5% pace of the second quarter, while earnings would fall about 24% from $0.46. The Earnings Whisper sits at $0.42, a notable seven cents above consensus, suggesting that the more engaged corners of the market think the published estimates undershoot what the company can deliver. Management's updated full-year revenue range of $1.21 billion to $1.23 billion translates to growth of 10% to 12%, and the Street's $1.21 billion sits right at the bottom of it. In other words, analysts are not buying the raise wholesale.
Some caution is warranted, and management itself supplied the reasons. Executives flagged that the third quarter laps roughly two points of growth from last year's club store expansion and a July 4 ordering shift, so a deceleration was always coming. They also added about $8 million to their logistics cost assumption as fuel prices and tight trucking capacity pushed freight to 6.9% of sales from 5.7% a year earlier. And household penetration growth is flattening, which means the business increasingly depends on existing customers buying more. Buy rate already accounted for most of recent growth, so evidence that heavy users, digital shoppers and multipack buyers are still expanding their baskets will matter more than usual. Digital orders, which jumped 41% last quarter to nearly 17% of sales, are a useful barometer here.
The margin story is where validation could be most convincing. Management lifted its 2026 gross margin improvement target to 100 to 150 basis points and raised its 2027 floor to at least 49%, attributing the gains mostly to plant efficiency rather than new technology. The new bag manufacturing lines, now running at three sites, are expected to contribute only about 25 basis points this year but more than 100 basis points once optimized in 2027. A third-quarter gross margin that holds near the high 40s despite freight pressure would support both the raised EBITDA guide of $210 million to $220 million and the 20% to 22% EBITDA margin target for next year. A slide back toward the first quarter's 46.9% would raise doubts. Early commentary on Tractor Supply's rollout toward 700 stores, the Homestyle Creations Beef and Healthy Mixers launches, and the planned fourth-quarter staffing additions will also shape the outlook.
Sentiment has warmed considerably, swinging from solidly bearish before the last report to modestly bullish now, but the stock has not followed. Shares are down 2.8% since the second-quarter release, slightly lagging the S&P 500, and at $64.75 trade just above the 200-day moving average and well below the post-earnings high of $77.13. The entire trading range has shifted higher than the prior quarter's $46 to $64 band, yet the fade from the highs shows investors remain skeptical about durability.
The central question is whether Freshpet can show that the slowdown this quarter is purely a function of the calendar rather than fading demand, while keeping margins near record levels as freight costs climb. Clearing the low bar on sales and defending the gross margin would leave the full-year guide looking achievable or better; a miss on either front would suggest the second quarter was a peak rather than a new baseline.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 6 hours | |
| Oct-24 | |
| Oct-19 | |
| Oct-14 | |
| Oct-01 | |
| Aug-27 | |
| Aug-05 | |
| Aug-05 | |
| Aug-05 | |
| Jul-15 | |
| Jun-25 | |
| Jun-24 | |
| May-21 | |
| May-19 | |
| May-07 |
