Freshpet Posts Record 50% Gross Margin And Raises Guidance Again, But Slowing Sales And A Softer 2027 Margin Outlook Temper The Beat
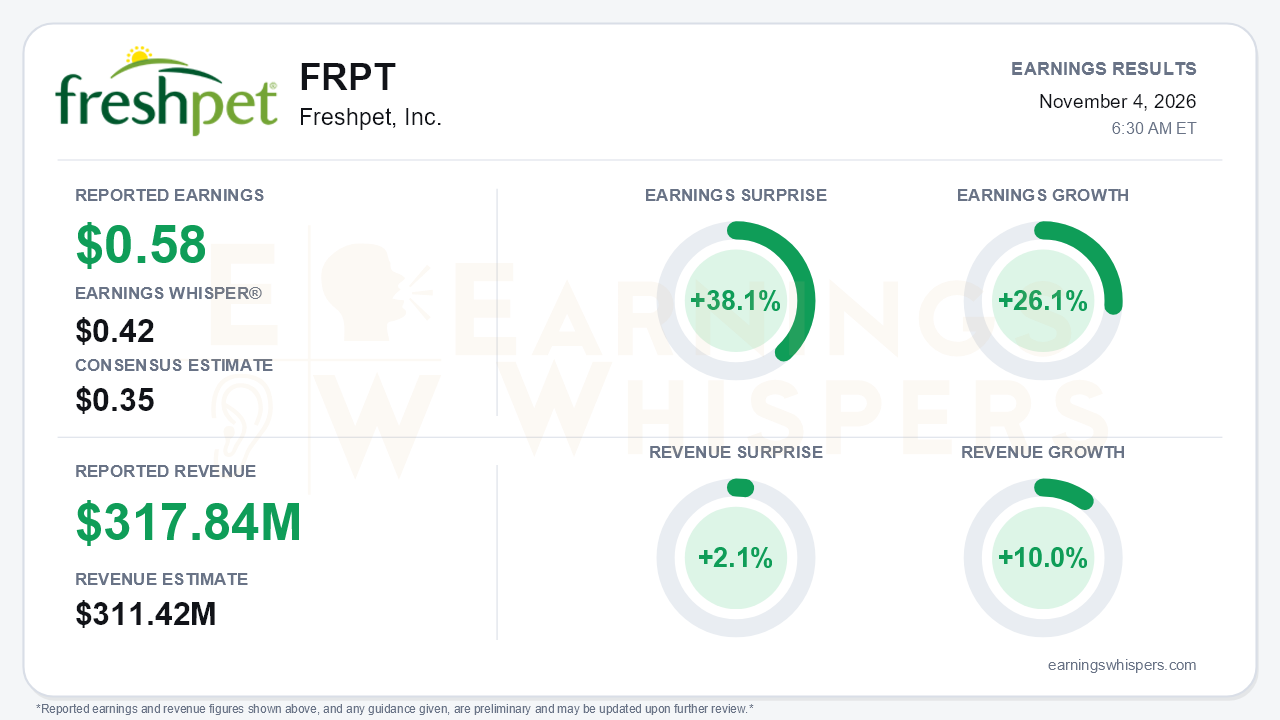
Freshpet delivered a decisive earnings beat in the third quarter. It earned $0.58 per share against a $0.35 consensus and a $0.42 Earnings Whisper number, a 38.1% surprise. Revenue of $317.84 million topped the $311.42 million consensus by 2.1%. Earnings grew 26.1% year over year and revenue rose 10.0%. Management raised full-year 2026 guidance for the third straight quarter. The engine of the beat was margin, not volume. Adjusted gross margin reached 50.0%, the company's best in more than seven years. Yet beneath the record profitability, top-line growth slowed for a second consecutive quarter, and management lowered its 2027 margin expectations. That is the central tension.
The quality of the margin story is strong. GAAP gross margin climbed to 44.5% from 39.5%. Adjusted gross margin rose to 50.0% from 46.0% a year ago and 48.6% in the second quarter. The press release credits better plant leverage, reduced quality costs and lower input costs. Adjusted EBITDA increased to $64.5 million from $54.6 million, lifting the margin to 20.3% from 18.9%. GAAP net income fell to $29.7 million from $101.7 million. That decline does not signal weakness: the prior-year quarter included a $77.9 million deferred tax benefit, while this quarter carried normal tax expense. Spending is the weaker spot. Adjusted SG&A rose to 29.6% of sales from 27.1%, driven by logistics costs and variable compensation. Logistics alone reached 7.1% of sales, up from 6.9% in Q2 and 6.3% in Q1.
The deceleration deserves scrutiny. Reported sales growth slowed to 10% from 15.5% in the second quarter and 13.1% in the first, with the increase driven entirely by 10% volume gains. Management attributed the gap versus 12.7% Nielsen consumption growth to two factors: a difficult club-channel comparison and a major customer running leaner inventory. That suggests underlying demand held up better than shipments did. However, the call also acknowledged a wide implied fourth-quarter sales range, including the possibility of flat or down sequential sales. Other operating metrics were healthier:
- E-commerce grew 35% and reached 16.9% of sales.
- Store count topped 31,000.
- Total distribution points rose 14%.
- Homestyle Creations passed $100 million in annual retail sales.
Guidance is where the story splits. Full-year 2026 sales growth was raised to 12%-13% from 10%-12%. The adjusted EBITDA range was narrowed upward to $215-$220 million, and expected gross margin expansion was lifted to roughly 150 basis points. The benefit from new bag technology was raised to about 35 basis points this year, with substantially all of the 100-basis-point annualized benefit now expected in 2027. Confidence in a 2027 adjusted gross margin of at least 49% was also raised. Against that, management now describes beef and packaging inflation as structural and expects 2027 adjusted EBITDA margin in the lower half of its 20%-22% range. It had reiterated that range without qualification last quarter. Incremental logistics costs were raised to $10-$12 million from $8 million, and fourth-quarter gross margin will step down sequentially on planned downtime. Selective 2027 price increases and productivity programs are the offsets. Competitive entry into fresh pet food remains a risk.
Cash generation is a quieter but meaningful catalyst. Operating improvements unlocked over $100 million of capacity from the existing footprint, roughly the equivalent of a new line. That allowed 2026 capital spending to be trimmed to $125-$150 million from about $150 million. Nine-month free cash flow reached $65.3 million versus $10.3 million a year ago. The company has repurchased $102.3 million of stock under its $150 million authorization.
Investor expectations shifted materially heading into the report. Earnings Whispers sentiment moved from -0.367 after the prior report to +0.073, a meaningful swing from clearly negative to modestly positive. The stock's path was volatile. Shares hit $77.13 in late August, then slid to $56.00 by late September, before recovering to $69.60. That is up 4.5% from the opening price after the August report and about 8.9% above the 200-day moving average of $63.90. Shares still sit nearly 10% below the inter-earnings high. The Earnings Whispers trend signals are broadly positive, consistent with the recovery off the September low.
The bottom line is that Freshpet produced a high-quality profitability beat, a third consecutive guidance raise and sharply better cash generation. However, the growth narrative is less clean than the headline surprise implies. Shipments are decelerating and lagging consumption, logistics costs keep climbing, and management has lowered its sights on 2027 EBITDA margins because of inflation it now calls structural. Bulls can point to record margins and expanding capacity. Bears have legitimate ammunition in the slowing top line and the softer 2027 margin outlook.
Read our earnings preview for Freshpet, Inc.: https://www.earningswhispers.com/article/FRPT/21702
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 4 hours | |
| 11 hours | |
| 11 hours | |
| Oct-27 | |
| Oct-24 | |
| Oct-19 | |
| Oct-14 | |
| Oct-01 | |
| Aug-27 | |
| Aug-05 | |
| Aug-05 | |
| Aug-05 | |
| Jul-15 | |
| Jun-25 | |
| Jun-24 |
