Flutter's First Report Under New CEO Tests Whether US Reinvestment Is Buying Real Growth
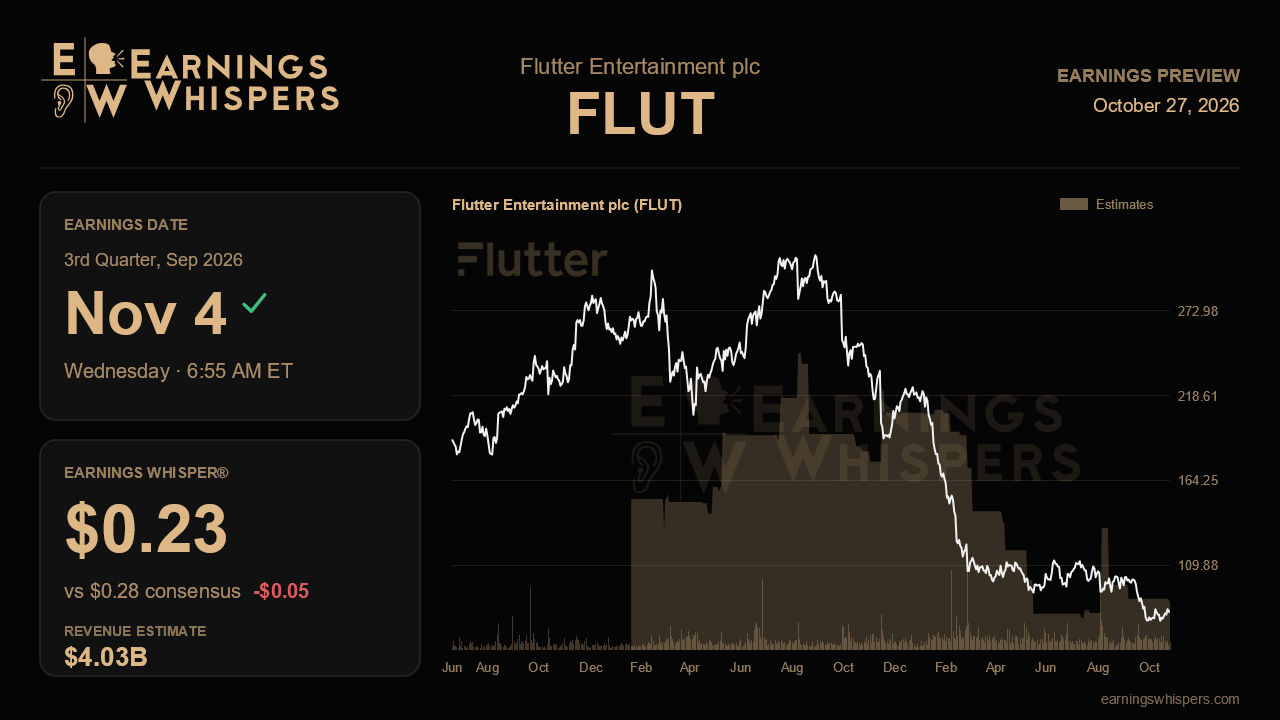
Three months ago Flutter Entertainment told investors it would trade near-term profit for long-term share in the US, cutting its full-year outlook to fund a heavier dose of customer generosity just as its chief executive prepared to step aside. The third-quarter report on November 4, before the opening bell, is the first real scorecard for that bet. It is also the first set of numbers under Dan Taylor, who took the helm at the end of September. The market has already rendered a harsh preliminary verdict, and the question now is whether the operating evidence justifies the pain.
Wall Street expects non-GAAP earnings of $0.28 a share on revenue of about $4.03 billion, which would be roughly 6% revenue growth from a year ago. That is modest expansion, not a rebound, and it implies a sequential step down from the $4.33 billion reported last quarter as the delayed NFL start shifts betting activity later. The profit comparison is stark: the year-ago quarter produced $1.25 a share, so earnings are set to fall sharply even with the top line growing. The whisper number of $0.23 sits noticeably below consensus, suggesting the more informed expectations bar is lower than the published one and that a modest shortfall versus the official estimate may already be anticipated.
The guidance math deserves attention. Management lowered its 2026 revenue target by about $395 million to roughly $17.91 billion and trimmed adjusted EBITDA guidance to about $2.655 billion. Yet full-year revenue consensus still sits near $18.20 billion, comfortably above the company's own outlook. Either analysts are betting on a beat that management has not promised, or estimates have not fully caught up with the cut. A reaffirmed $17.91 billion would not by itself be a disappointment, but it would leave the Street needing to come down, and any further trim would land on a stock that has little cushion left.
Operationally, the US business is the whole story. Revenue there fell 6% in the second quarter after growing 6% in the first, and management assumed a flat US market in the second half after only about 5% growth in the first half. The roughly $270 million of incremental generosity and marketing spend is supposed to show up as rising average monthly players and recycled stakes. Validation would mean clear active-player growth during the opening weeks of football, early traction from the national one-app rollout and expanded rewards program, and evidence that the crypto.com integration is broadening the Predicts catalog as promised. A challenge would be higher spending without visible engagement gains, or management walking back the roughly $500 million fourth-quarter US EBITDA target. Outside the US, the bar is to sustain the strength in Southeast Europe iGaming, Italy and the UK while showing Brazil's organic decline is stabilizing. Progress on the market-making business, now targeted at about $50 million for the year, and the expanded cost programs would help offset US pressure and slow the climb in leverage, which reached 4.3 times.
Sentiment remains bearish, though marginally less so than before the last report, and the shares tell a grimmer story. The stock has dropped about 18% since the prior release, trailing the S&P 500 by more than 16 points, and at roughly $80 it sits far below its 200-day moving average near $110 and close to the bottom of its post-earnings range. That positioning lowers the bar for relief, but it also signals deep skepticism about the reinvestment thesis.
Ultimately, this report hinges on one question: is Flutter's generosity buying durable US customer growth, or simply subsidizing a soft market? If the new CEO can show players responding and hold the reset guidance, the turnaround narrative survives. If not, the guidance cut may look like a first step rather than a reset.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-27 | |
| Oct-26 | |
| Oct-23 | |
| Oct-22 | |
| Oct-21 | |
| Oct-16 | |
| Oct-15 | |
| Oct-15 | |
| Oct-14 | |
| Oct-14 |
Fanatics CEO Warns $7 Billion Betting Ad War Looms as Kalshi, Polymarket Join Fight
FLUT
Benzinga Prediction Markets
|
| Oct-09 | |
| Oct-07 | |
| Oct-07 | |
| Oct-07 |
