Flutter Swings To An Adjusted Loss And Cuts Guidance A Third Time As FanDuel's Progress Gets Buried Under Brazil, Bad Bounces And Leverage
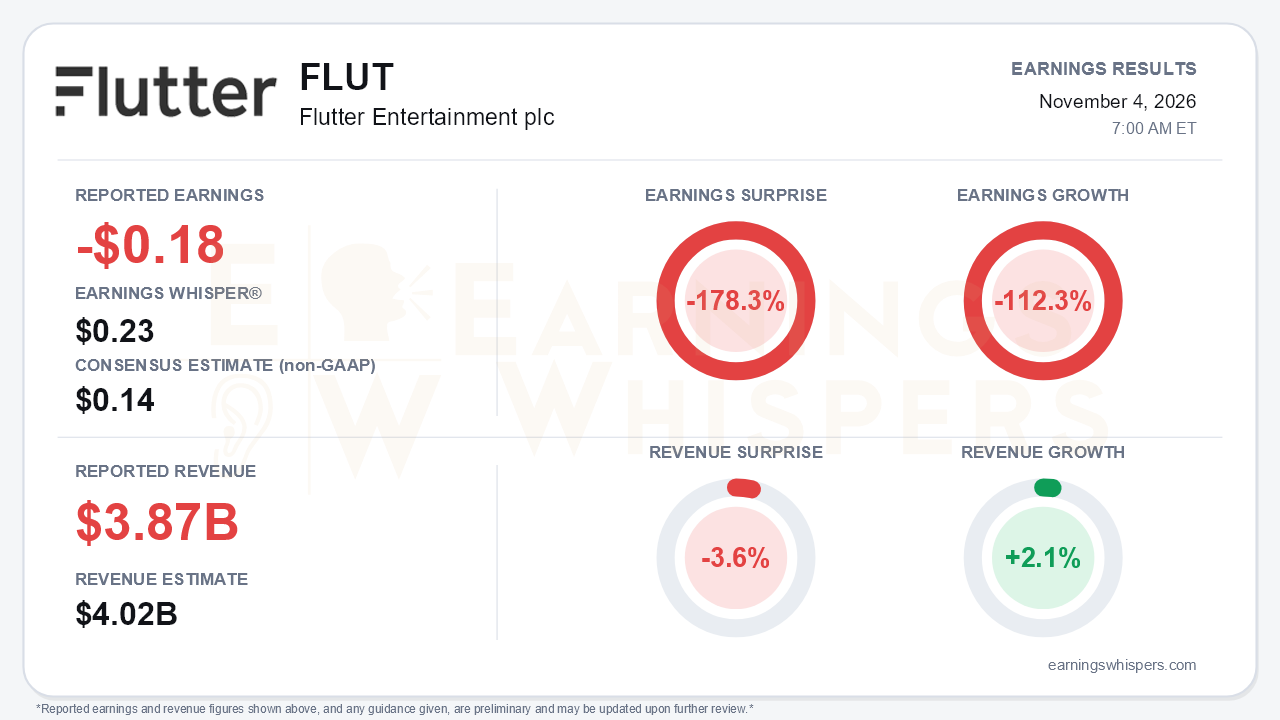
Flutter Entertainment's third quarter missed expectations on both lines. The company posted an adjusted loss of $0.18 per share against a consensus estimate of $0.14 and an Earnings Whisper number of $0.23, a 178.3% miss. A year earlier it earned $1.64 per share on an adjusted basis, so adjusted earnings fell 112.3% from profit to loss. Revenue rose just 2.1% to $3.874 billion, 3.6% short of the $4.02 billion consensus. The headline also came with Flutter's third consecutive cut to full-year guidance. The revenue midpoint has now slid from $18.3 billion at Q1 to $17.61 billion, and the adjusted EBITDA midpoint from $2.865 billion to $2.495 billion. The reductions roughly matched where estimates had already drifted. Even so, a steady pattern of downgrades is the central problem: under-promising has not yet become a habit at Flutter.
The quality of the miss deserves scrutiny, because a meaningful share of it was luck rather than erosion.
- **Sports results:** Customer-friendly results cost the International segment about $131 million of revenue and $86 million of adjusted EBITDA. The US gave up another $38 million and $27 million.
- **UK gaming duty:** The increase from 21% to 40% pushed International cost of sales up 490 basis points, which drove the segment's 14% EBITDA decline to $435 million.
- **Deliberate US spending:** US adjusted EBITDA collapsed to $3 million from $51 million. That reflects choices, including prediction-market investment, the Alberta launch, World Cup spending and promotions raised to 6.0% of handle.
Group adjusted EBITDA fell 25% to $360 million. On a GAAP basis, the loss widened to $4.90 per share. That figure includes an $873 million Brazil impairment after the government's provisional ban on online betting and a $105 million provision tied to an Australian class action.
Beneath the noise, US sportsbook trends genuinely improved. Handle grew 13% despite one fewer week of NFL and college football. Bet count rose 15%, player frequency climbed 4%, and FanDuel regained market share in August and September. On the call, management pointed to strong retention of a 2.3 million-customer World Cup cohort. The cost of that momentum is margin. Net revenue margin slipped 60 basis points to 6.8%, and management expects promotional intensity to hold into 2027, leaving US net revenue margin broadly flat next year. That pushes out the margin expansion bulls had been modeling. US iGaming is also cooling: revenue growth moderated to 8% on competition and maturing states, even as players grew 24% and Alberta captured a 23% share in its first quarter.
Prediction markets are both the clearest catalyst and the most expensive risk. FanDuel Predicts was rebuilt on Crypto.com and the One App. Management said October actives reached roughly 140,000, up from 66,000 average monthly players in Q3, and October volume nearly tripled versus July. Market-making is on track for about $50 million of revenue this year. The bill is steep, though. The prediction-market EBITDA loss is running near $200 million for 2026, and management expects similar or higher investment in 2027. Competitors in the space are also inflating category media costs, which management said rose more than 60% year over year in September. Internationally, the story is cleaner. Italy share rose to 32%, UKI and Southern Europe grew 4% and 13%, and management guided 2027 International EBITDA growth to the high end of its 5-10% range, supported by a new $500 million savings program through 2029.
The capital-allocation shift may matter most to holders. Leverage has climbed to 4.6x from 3.7x at year-end, against a 2.0-2.5x target, and the buyback is paused "for the foreseeable future." The refinancing that pushes maturities to 2032 helps. Free cash flow excluding player funds improved only in the sense that the quarterly burn narrowed to $91 million.
The market was already skeptical heading into the report.
- Shares closed at $83.74 the day before the release, 14.3% below the open following the August report.
- The stock sat 21% below its $106.01 200-day moving average.
- Shares had fallen from a September high of $104.84 to a 52-week low of $72.56 in mid-October. They had recovered about 15% from that low but remained near the bottom third of the quarter's range.
Investor sentiment stayed negative and weakened modestly, from -0.34 to -0.39. Momentum and AVWAP readings remain negative as well.
The bottom line is that new CEO Dan Taylor inherited a business whose operating engine is better than its income statement suggests, with US sportsbook share recovering, International execution strong and a credible prediction-market foothold. But the quarter turned a growth-and-buyback story into a deleveraging-and-reinvestment story. Bears have legitimate ammunition in three straight guidance cuts, flat US margins into 2027 and 4.6x leverage. Until Flutter delivers a quarter that holds its numbers, operational wins are likely to struggle to outweigh the credibility deficit.
Read our earnings preview for Flutter Entertainment plc: https://www.earningswhispers.com/article/FLUT/21701
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 8 hours | |
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Oct-27 | |
| Oct-27 | |
| Oct-26 | |
| Oct-23 | |
| Oct-22 | |
| Oct-21 | |
| Oct-16 | |
| Oct-15 |
