Flowco's Revenue Surge Meets A Margin Test As Lube Oil And Fuel Costs Bite
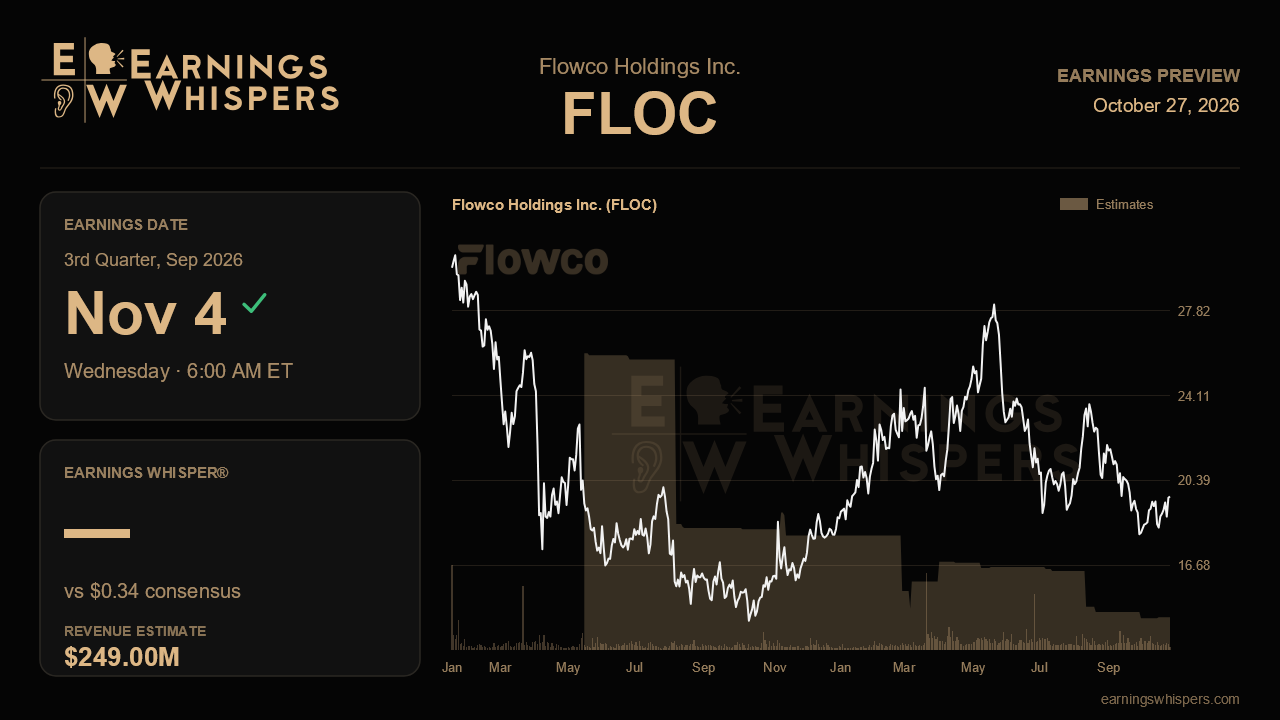
Flowco heads into its third-quarter report with a split personality. The top line has climbed every quarter for a year, the Valiant acquisition is outrunning its own plan and the balance sheet has rarely looked better. Yet the stock has slid about 12% since the last report, trailing the S&P 500 by more than 11 percentage points. The likely reason is the one new blemish management disclosed last quarter: rising lube oil, fuel and maintenance costs that the company largely cannot pass along to customers. This report is the first real look at how deep that bite goes.
Wall Street expects earnings of $0.34 per share on revenue of $249.0 million. That revenue figure would represent growth of roughly 41% from the $176.9 million posted a year ago, largely reflecting Valiant, and about 6% above the $235.9 million reported last quarter. Per-share profit, by contrast, is projected to fall about 42% from last year's $0.59 and to edge below the prior quarter's $0.36. That divergence tells the story. Volume is not the concern; what each incremental dollar of revenue is worth is.
Management's own framework points the same way. The company guided third-quarter adjusted EBITDA to $92 million to $98 million, a midpoint of $95 million that is only modestly above the $93.9 million delivered in the second quarter. Set against consensus revenue, that midpoint implies a margin around 38%, down from roughly 40% last quarter, 40.8% in the first quarter and 42.4% at the end of fiscal 2025. In other words, the Street appears to have already accepted another step down in profitability. A result near the top of the EBITDA range would suggest the cost squeeze is more manageable than feared, while a print toward the low end on in-line revenue would confirm that margin erosion is becoming a trend rather than a blip.
The Production Solutions segment is where that verdict will be rendered. Its margin fell about 229 basis points in the second quarter after a 125 basis point decline in the first, driven by Valiant's lower-margin mix plus the new cost inflation. Management signaled those pressures would persist into this quarter, so investors should look for stabilization rather than recovery, along with any sign of pricing actions or contract changes that could restore pass-through. The natural gas technologies segment needs to show that weaker vapor recovery unit system sales were lumpy rather than structural; management pointed to in-basin power demand and new Permian gas takeaway as tailwinds, and a rebound from the 6% sequential dip would lend that argument credibility.
On the growth side, the catalysts introduced last quarter deserve concrete follow-through. Management described early cross-selling wins on Valiant jobs, engagement with major operators on early-life lift, and international prospects through its Middle East and Latin America partnerships. Named wins or measurable revenue contributions would help justify the reaffirmed target of about $52 million in Valiant EBITDA for the year. Continued free cash flow conversion above 50%, which has held for five straight quarters, would also support the dividend increase, the special payout and any appetite for further acquisitions.
Sentiment has drifted more negative, with readings moving from 33.1% bearish to 37.2% bearish, and the stock at $19.69 sits below its 200-day moving average of $21.86 and closer to the bottom of its post-earnings range of $17.46 to $24.00. That range has shifted noticeably lower than the prior quarter's band, which topped out above $28. The bar, then, is not especially high. The central question is whether Flowco can show that its margin compression has found a floor while Valiant-driven growth keeps compounding. If it can, the market's recent skepticism may look overdone; if margins slip again, the growth story will keep getting discounted.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-30 | |
| Oct-27 | |
| Oct-14 | |
| Oct-02 | |
| Aug-11 | |
| Aug-11 | |
| Aug-11 | |
| Aug-10 | |
| Aug-10 | |
| Jul-30 | |
| Jul-30 | |
| Jul-21 | |
| Jun-10 | |
| May-06 | |
| May-01 |
