Flowco Doubles The Consensus EPS Estimate With A Record Quarter, But A One-Time Rental Release And A Lower Q4 Guide Complicate The Beat
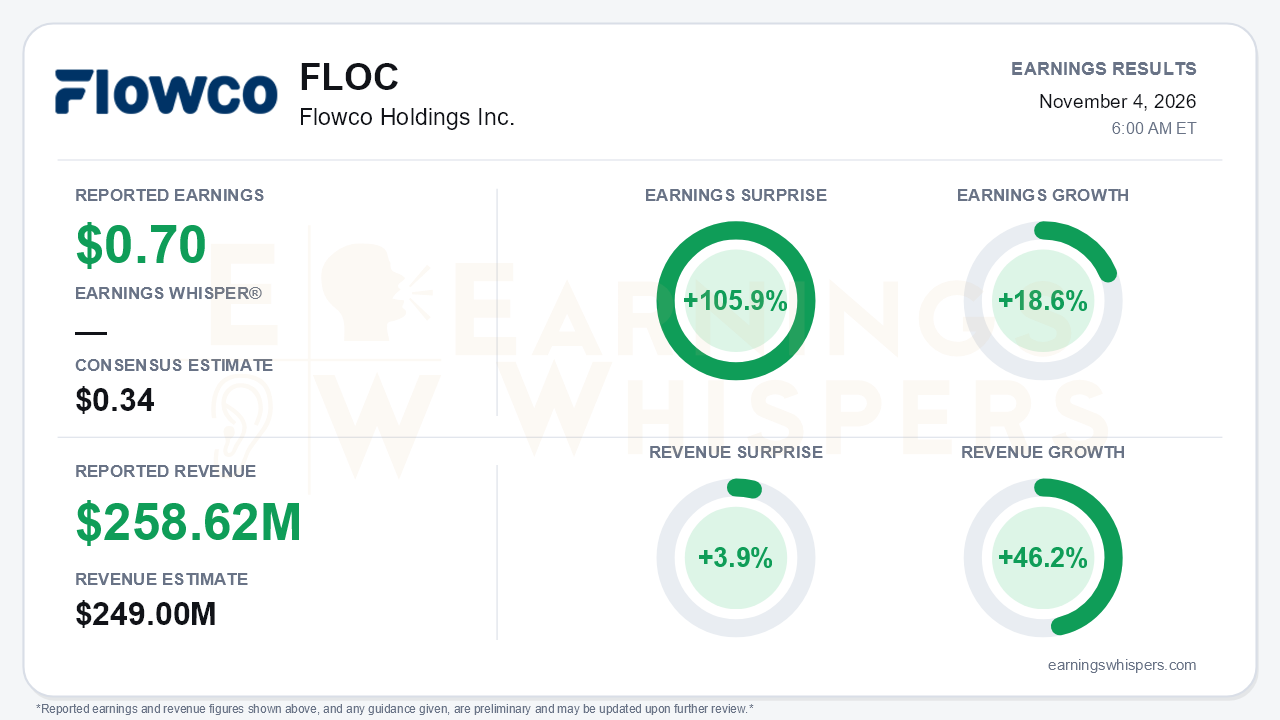
Flowco Holdings (NYSE: FLOC) delivered the strongest quarter in its short public history. The company reported earnings of $0.70 per share against a $0.34 consensus, a 105.9% surprise. Revenue of $258.6 million beat the $249.0 million estimate by 3.9% and grew 46.2% year over year. Adjusted EBITDA reached a record $103.9 million, well above the $92–98 million range management had guided three months earlier. Earnings grew a more modest 18.6% year over year, and that gap between revenue and earnings growth matters. Acquisition-driven scale is adding revenue faster than it is adding per-share profit. Part of this quarter's upside also came from an event that will not repeat. That is the central tension: a genuinely strong operating quarter sits on top of a fourth-quarter outlook that steps down.
The quality of the beat deserves scrutiny. Roughly $9 million of third-quarter revenue was accelerated rental revenue. A major oil customer returned high-pressure gas lift surface equipment early. That release drove much of Production Solutions' 209-basis-point sequential margin gain, because it lifted the share of high-margin Surface Equipment revenue in the mix. Margins have also drifted over the year. Consolidated adjusted EBITDA margin was 40.2%, roughly flat with the second quarter's 39.8% but down from 43.4% a year ago and 42.4% in the fourth quarter of 2025. Natural Gas Technologies is the clearest example. Segment revenue jumped 23.1% sequentially to $80.0 million, and segment EBITDA hit a post-IPO high. However, segment margin fell 413 basis points to 38.6%, versus 49.3% a year earlier, as lower-margin Natural Gas Systems sales grew in the mix. On a GAAP basis, diluted EPS was $0.40, compared with $0.32 a year ago and $0.28 last quarter. That is real improvement, but it is less dramatic than the normalized figure.
Cash flow was the cleanest part of the report. Operating cash flow was $103.1 million, and free cash flow reached a record $72.4 million, about 70% of adjusted EBITDA. That compares with roughly $50–63 million in each of the prior three quarters. Management cautioned that conversion should normalize toward about 50%. It also said 2027 capital spending should be similar to or slightly below 2026 levels, even after adding Valiant and Lifting Solutions. The board increased the buyback authorization by $150 million to $200 million, a signal that management sees the shares as undervalued. The balance sheet now carries more leverage. Long-term debt rose to $363 million from $168 million at year-end. Revolver borrowings stood at $355.7 million after the Lifting Solutions close, leaving about $365 million of availability.
The call preserved a credible growth story, and management's tone was notably more confident. International work moved from "early innings" partnerships to firm orders:
- 20 ESP systems and roughly 250 progressing cavity pumps bound for Venezuela;
- 20 ESPs ordered by a multinational operator in Iraq;
- Lifting Solutions' Oman operations running ahead of plan.
Lifting Solutions closed October 2 for $112 million, about 5x management's expected 2027 adjusted EBITDA of roughly $23 million. The deal adds rod lift and PCP capability, makes Canada the company's second-largest geography, and lifts international exposure to roughly 10% of revenue. Valiant's cross-selling produced a significant ESP award from a large independent operator, which could become one of Flowco's biggest ESP customers. A planned consolidation of the 4,500-plus surface equipment and vapor recovery compression fleets offers a potential margin lever.
Bears have legitimate ammunition, however. Fourth-quarter adjusted EBITDA guidance of $93–99 million is below the third quarter's $104 million, despite a full quarter of Lifting Solutions. That implies softer organic results from seasonality and the equipment release. The returned gas lift units create a $1–3 million fourth-quarter EBITDA drag. Management expects to redeploy them to four to seven customers at similar rates, but fleet levels are not expected to recover until mid-2027. Other watch items include lengthening engine lead times for the compression fleet, a Venezuela environment management itself called fluid, and integration risk from a second 2026 acquisition while the M&A pipeline remains active.
The market was not positioned for a quarter this strong. Investor sentiment entered the report negative and slipped slightly further, from -0.33 to -0.37. Shares closed at $19.26 the day before the release. That is 14.3% below the $22.47 open after the August report, 11.9% under the 200-day moving average of $21.87, and nearly 20% off the $24.00 inter-earnings high set August 17. The stock had recovered about 10% from its October 15 low of $17.46. The Earnings Whispers trend readings are mostly negative on price and AVWAP, while sequential growth stands out as positive, which reflects the divide between operating momentum and stock behavior.
The bottom line is that Flowco's third quarter was a real beat on revenue, cash flow and EBITDA, not just an accounting win. Even so, it was flattered by roughly $9 million of non-recurring rental revenue and followed by a sequentially lower guide. The investment debate now centers on three questions: whether international orders and Lifting Solutions can offset slower organic growth and margin mix pressure, how quickly the returned gas lift fleet is redeployed, and whether strong cash generation keeps funding both acquisitions and buybacks without straining the balance sheet.
Read our earnings preview for Flowco Holdings Inc.: https://www.earningswhispers.com/article/FLOC/21700
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Nov-02 | |
| Oct-30 | |
| Oct-27 | |
| Oct-14 | |
| Oct-02 | |
| Aug-11 | |
| Aug-11 | |
| Aug-11 | |
| Aug-10 | |
| Aug-10 | |
| Jul-30 | |
| Jul-30 | |
| Jul-21 |
