CS Disco's Rally Puts Its Raised Outlook And AI Ambitions To The Test
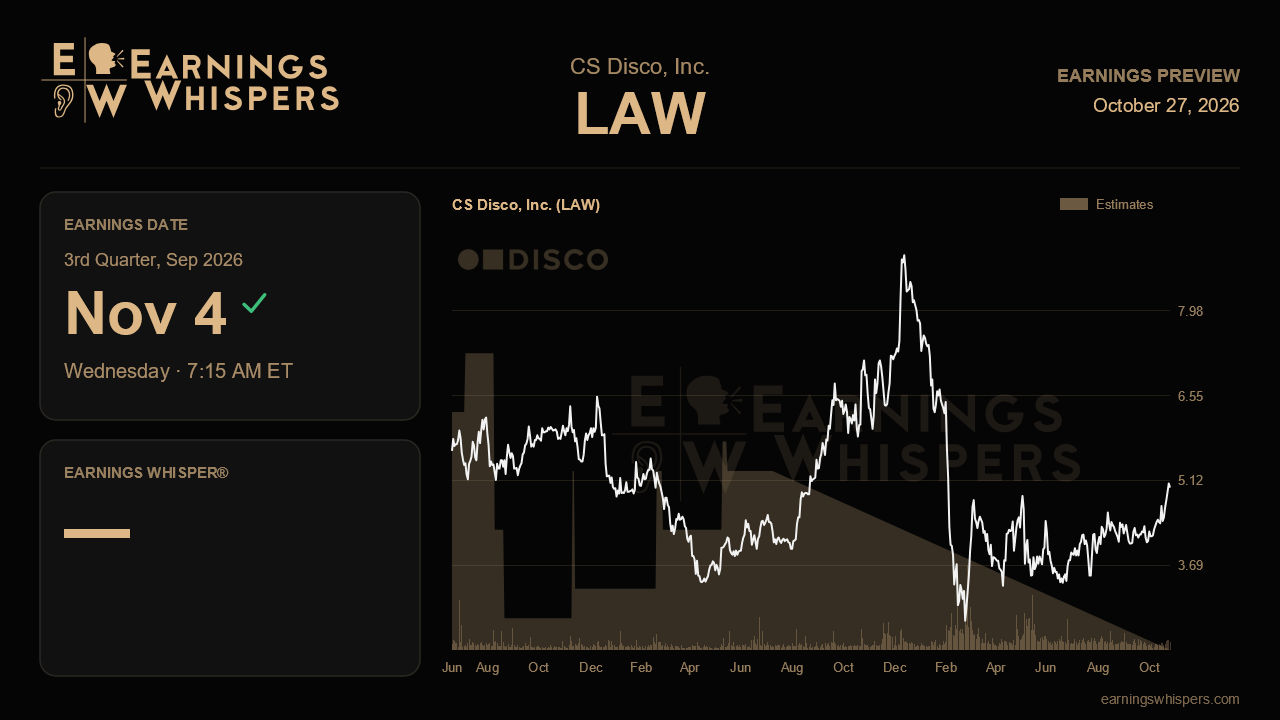
CS Disco heads into its third-quarter report with a stock that has already run ahead of the story. Shares have climbed nearly 30% since the last report while the S&P 500 slipped, as investors rewarded a third straight increase to the full-year revenue outlook and a markedly bolder product pitch. The open question for the quarter is whether the legal software company can show that the confidence it voiced about the second half is turning into visible acceleration, or whether steady low-double-digit growth and persistent losses are all the rally has to stand on.
The revenue bar sits squarely on management's own guidance. The company guided third-quarter revenue to $43.75 million to $45.75 million, and the Street's $44.72 million estimate lands almost exactly at the midpoint. For the full year, consensus of $175.26 million is just shy of the middle of the raised $172 million to $179 million range. That positioning matters. Analysts have accepted the higher outlook without leaning into it, so a result near the top of the quarterly range, along with another nudge to annual guidance, is the kind of outcome that would reinforce the bull case. Measured against the $40.9 million reported a year ago, the consensus figure implies growth of roughly 9%, a slowdown from the 13% pace of the second quarter. If Disco simply matches estimates, the narrative of durable growth starts to look more like gentle deceleration, which is not what a 30% rally is pricing in.
The last call offered several specific claims that this report can verify. Management said adoption of the Disco Platform had already reached its year-end target by June, well ahead of plan. That is encouraging, but it carries a known side effect: customers moving to the platform may pay lower ingest fees, a drag management has flagged twice while calling it immaterial so far. A quarter in which platform momentum continues without denting usage revenue would validate the migration strategy. Equally important is AutoReview, which bounced from a soft first quarter to a revenue record in the second. A second consecutive strong showing would suggest the first-quarter wobble, when some customers reverted to traditional review, was noise rather than a sign of reluctance toward AI-driven review. Continued growth in customers spending more than $100,000 annually, which reached 354 last quarter and account for about three-quarters of revenue, would confirm that larger accounts keep expanding.
Profitability is the softer part of the picture. Adjusted EBITDA was negative $3.4 million last quarter, slightly worse than a year earlier, and the company trimmed the top of its full-year EBITDA range to reflect added research spending on its new Unified Litigation Solution. Gross margin has been stuck around 76%. Investors will want to see that the incremental R&D is contained and that operating cash flow, which improved sharply to roughly breakeven in the second quarter, does not slide back. Any update on the Unified Litigation Solution pilot, which pairs a case's evidence record with the full body of U.S. case law, would also help, though management has been clear it contributes no revenue this year and has not set pricing or timing. Competitive noise from broader legal AI players adds weight to any sign that customers are paying up for Disco's tools.
Sentiment has barely moved, slipping to 21.5% bullish from 22.7% a quarter ago, which suggests the stock's climb reflects price momentum more than a surge of optimism. Technically, shares at $5.00 sit comfortably above the 200-day average near $4.27 and within about 2% of the post-earnings high of $5.11, so the report could decide whether the stock breaks out or stalls at resistance.
Ultimately, the quarter hinges on whether Disco can deliver revenue toward the upper half of its range while holding losses in check. A beat-and-raise would show that the confidence management expressed is grounded in demand. An in-line print paired with slower growth and wider losses would leave a richly rewarded stock leaning heavily on a product that will not pay off until later.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-14 | |
| Sep-23 | |
| Aug-20 | |
| Aug-05 | |
| Aug-05 | |
| Aug-05 | |
| Aug-05 | |
| Aug-04 | |
| Aug-03 | |
| Jul-23 | |
| Jul-15 | |
| Jun-16 | |
| May-07 | |
| May-06 |
