CS Disco Hits EBITDA Breakeven A Quarter Early And Posts Its Fastest Growth In Four Years, But Software Growth Remains Stuck Near 13%
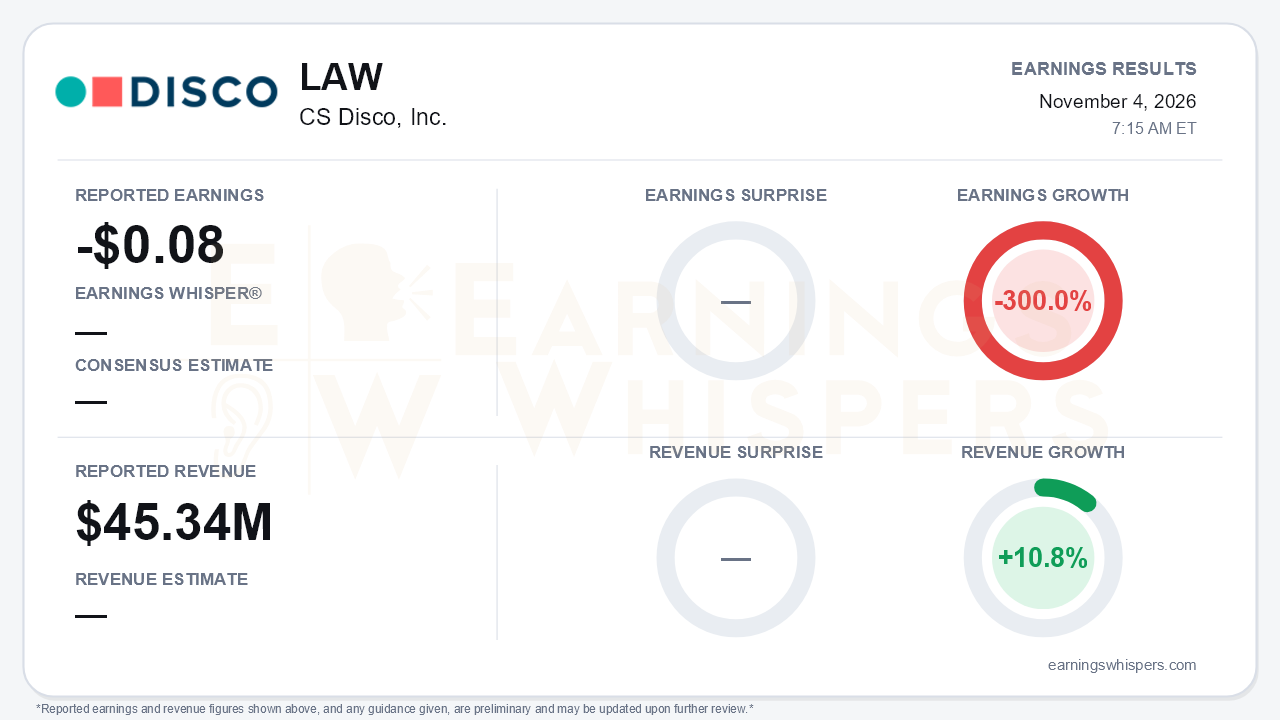
CS Disco (NYSE: LAW) delivered the milestone it had been promising, a quarter ahead of schedule. Adjusted EBITDA came in at a positive $0.1 million in the September quarter. The company had guided to a loss of $1.75 million to $0.25 million, posted a $3.4 million loss in Q2, and recorded a $0.3 million loss a year earlier. Revenue rose 10.8% year over year to $45.34 million, or 15% excluding a $1.3 million contingent-matter recognition in the prior-year quarter. Management called that adjusted rate the best in four years, and it extends a sequence of 11%, 14% and 13% over the prior three quarters. The company reported a loss of $0.08 per share. No consensus EPS or revenue estimate was available, so company guidance is the most relevant yardstick. Earnings Whispers' normalized figures show earnings down 300.0% year over year. That reading contrasts with the GAAP statements, where the net loss narrowed to $5.0 million ($0.08 per share) from $13.7 million ($0.22). The central tension is that the profitability and total-revenue story improved materially, while the core software engine did not speed up.
The quality of the quarter deserves some scrutiny. The GAAP loss narrowed sharply, but the prior-year quarter carried $7.0 million of stockholder-litigation expense that did not recur. Stock-based compensation also fell to $4.7 million from $6.1 million. On a non-GAAP basis, the operating loss improved more modestly, to $0.9 million from $1.3 million. Margin progress was genuine:
- Non-GAAP gross margin reached 77%, up from 75% in Q1 and 76% in Q2.
- Non-GAAP G&A fell to 17% of revenue from 19%.
On the call, however, an analyst questioned whether higher capitalized R&D tied to the unified litigation solution flattered adjusted EBITDA. The cash-flow statement lends that concern some weight, with year-to-date capitalized software and equipment spending of $4.2 million versus $2.5 million a year ago. Cash and short-term investments fell to $96.8 million from $101.4 million in Q2 and $114.6 million at year-end. Year-to-date operating cash burn of $15.8 million was essentially unchanged from last year, and receivables climbed to $32.4 million from $25.6 million.
The mix beneath the headline also matters. Software revenue grew 10%, or 13% adjusted, to $38.6 million. That landed at the midpoint of guidance, not the high end. Software growth has now run at 14%, 12%, 13% and 13% over four quarters. Services, which grew 21%, did much of the work in pushing total revenue to the top of its range. Generative AI revenue is still growing quickly, but it is moderating off a larger base: from more than 600% in Q4 FY25, to more than 3x in Q2, to more than 200% in Q3.
The forward-looking catalysts are where the call built its case:
- **DISCO Platform:** Revenue is more than 10x Q1 levels and already ahead of its full-year internal target. Large matters on the Platform tripled in the quarter, and as of October 1 it became the default commercial model for all new and renewal contracts.
- **Auto review:** Revenue grew more than 4x year over year, and one corporate customer mandated it for all outside counsel.
- **Advanced Research:** The newly launched agentic tool reached 97% of Cecilia Q&A usage in October.
- **Unified litigation pilot:** A second cohort that includes four AmLaw 50 firms has joined, with a third planned by year-end.
- **Large customers:** Customers above $100,000 grew 15% to 374 and now represent 78% of trailing revenue.
CEO Eric Friedrichsen's framing shifted from DISCO being able to grow 20%-plus over time to being more confident than ever that the core business alone can get there. Bears have legitimate ammunition, though. The Platform shift reduces one-time ingest fees, which could weigh on near-term revenue. Analysts also flagged price commoditization in AI first-pass review from AI-native competitors.
Guidance was in line overall but nudged favorably. Full-year revenue guidance narrowed to $176.1-$178.1 million. Its $177.1 million midpoint is the fourth consecutive increase and now sits above the original high end. The adjusted EBITDA midpoint improved to a loss of $6.05 million, and Q4 is guided to breakeven to $1.5 million positive. The full-year software range, however, narrowed to $149.5-$150.5 million with an unchanged midpoint near $150 million. That suggests management sees no near-term software acceleration either.
The market setup is more demanding than it was three months ago. Shares closed at $5.17 ahead of the report, up 33.9% from the $3.86 open after the August release and 49.4% above the inter-earnings low of $3.46 set that same day. The stock sat 22.7% above its 200-day moving average and within 3.6% of its October 30 quarter high. The Earnings Whispers trend signals are uniformly positive, consistent with that run. Investor sentiment, by contrast, remained positive but softened modestly, slipping to 0.18 from 0.23. That suggests some cooling of enthusiasm even as the price climbed.
The bottom line is that DISCO cleared its most visible hurdle early, lifted revenue guidance again and offered a credible product narrative around the Platform and agentic AI. The 20%-plus ambition, however, still rests on software growth that has yet to break out of the low teens. With the stock entering the report near its highs, the burden now shifts to evidence that Platform adoption translates into faster software growth rather than just a better margin profile.
Read our earnings preview for CS Disco, Inc.: https://www.earningswhispers.com/article/LAW/21713
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Oct-27 | |
| Oct-14 | |
| Sep-23 | |
| Aug-20 | |
| Aug-05 | |
| Aug-05 | |
| Aug-05 | |
| Aug-05 | |
| Aug-04 | |
| Aug-03 | |
| Jul-23 |
