Medline's Margin Repair Test: Can Faster Sales Outrun Fire, Quality And Retail Costs?
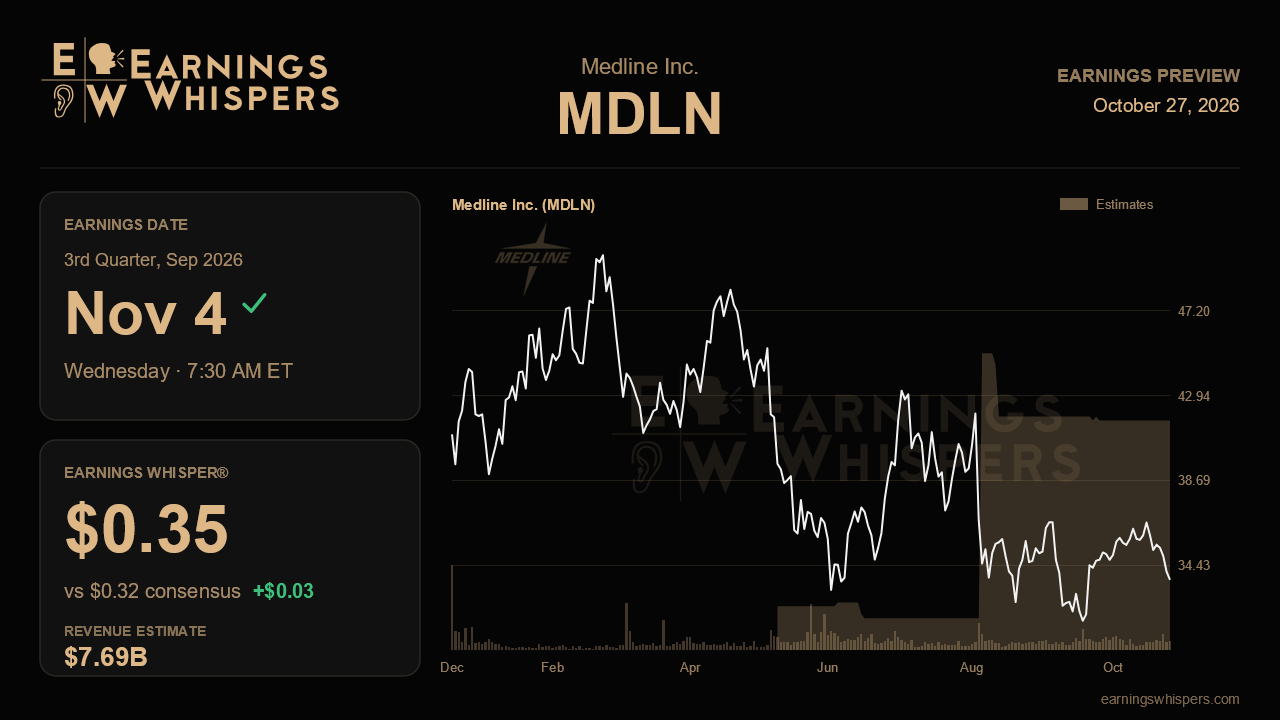
Medline enters its third-quarter report with a split personality. Demand has rarely looked better: sales growth accelerated for a second straight quarter, management lifted its full-year organic sales outlook again, and new customer signings are running ahead of plan. Yet the same report that delivered those gains also cut annual adjusted EBITDA guidance by roughly $200 million. The cut reflected a distribution center fire, an FDA-driven quality overhaul, softness in retail and spending that ran ahead of demand. When the company reports before the open on November 4, the question is whether the margin damage has stopped spreading.
The Street is looking for earnings of $0.32 per share on revenue of about $7.69 billion. That revenue figure is essentially flat with the $7.69 billion posted last quarter. The earnings estimate sits well below the $0.47 reported then, which suggests analysts have built in a meaningful dose of the second-half cost pressure management flagged. The Earnings Whisper of $0.35 sits a few cents above consensus. That points to a modestly higher informal bar, though not one that demands a blowout.
The framework for judging the quarter comes from management's own revised outlook: organic sales growth of 9% to 10% for the year and adjusted EBITDA of $3.3 billion to $3.4 billion. On the top line, validation means supply chain solutions holding growth in the mid-teens after reaching 16% last quarter. It also means continued progress toward the $1 billion signing goal, where the company had banked $650 million at midyear, including a new prime vendor agreement with Alina Health. Revenue that merely matches last quarter would raise questions about whether the momentum that justified two guidance increases is sustainable. It would also renew attention on the extra capacity Medline built to serve that demand.
The more consequential evidence sits in the cost lines. Management said it expected another $50 million to $100 million of fire-related costs in the second half. It also cautioned that some lease and labor inefficiencies at the rapidly assembled Northern California facilities would linger. Wipes production at Waukegan was offline longer than planned, and quality remediation carries its own expense. Medline Brand margins had already slipped from the mid-20s toward the low 20s. Supply chain solutions was guided to roughly 5% EBITDA margins for the year. Stabilization in either segment would support the idea that last quarter's reset was a one-time catch-up. Further slippage would revive the worry that the roughly half of the cost increase management called permanent is larger than advertised. Investors should also watch whether the $140 million tariff relief holds and whether the roughly $70 million Middle East inflation estimate changes.
The market has not been forgiving. Shares are down nearly 10% since the last report, trailing the S&P 500 by more than eight percentage points. At $33.69, the stock trades well below its 200-day moving average near $39.86. It sits closer to the bottom of its post-earnings range of $31.49 to $37.98 and below last quarter's low of $32.82. Sentiment has nonetheless swung sharply, from clearly bearish heading into the prior report to firmly bullish now. That combination suggests some believe the bad news is priced in, although sentiment offers no guarantee of the outcome.
Ultimately this report hinges on whether management reaffirms the reduced EBITDA range without new charges and whether it can describe a credible path to recovering margins. A reiterated outlook, steady segment margins and on-track signings would let the growth story reassert itself. Another reduction, particularly one tied to the internal issues management said made up about three quarters of the problem, would suggest Medline's operational growing pains run deeper than investors were told.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-15 | |
| Oct-12 | |
| Oct-06 | |
| Oct-06 | |
| Oct-02 | |
| Sep-28 | |
| Sep-24 | |
| Sep-08 | |
| Sep-03 | |
| Aug-21 | |
| Aug-19 | |
| Aug-17 | |
| Aug-12 | |
| Aug-10 |
