Medline Beats On Sales And EPS, But Tariff Refunds Flatter The Quarter As Margin Pressure Pushes Its Growth Algorithm To 2028
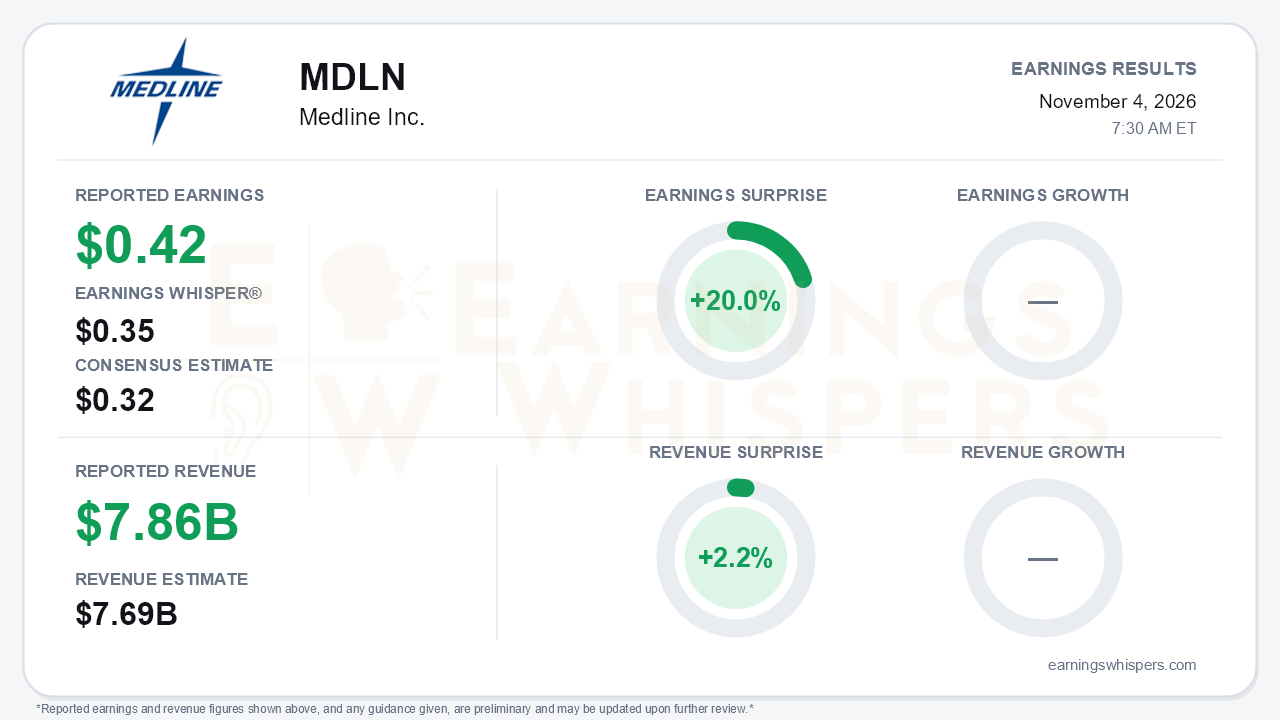
Medline (NASDAQ: MDLN) cleared the bar comfortably on the headline. Earnings of $0.42 per share topped the $0.32 consensus by 20.0% and beat the $0.35 Earnings Whisper number. Revenue of $7.856 billion beat the $7.69 billion consensus by 2.2%. The per-share figures need context: Earnings Whispers' normalized $0.42 differs from the company's own adjusted diluted EPS of $0.44 and from GAAP diluted EPS of just $0.22. Management also raised full-year organic sales guidance for a third straight quarter, to 10.0%-10.5%. Yet the quality of the beat deserves scrutiny. The top line keeps getting stronger while the margin story keeps getting weaker, and that is the central tension of this report.
Net sales rose 10.4%, with organic growth of 10.5%. That is a modest deceleration from roughly 12% in the second quarter, but still robust, driven by existing-customer growth and the ramp of 2025 contract signings. Beneath the sales line, profitability eroded:
- Gross margin fell to 24.5% from 26.4% a year ago.
- Operating income dropped 12.9%.
- GAAP net income slipped 1.2%, and net income attributable to Medline Inc. fell 39.4% once noncontrolling interests were deducted.
- Adjusted EBITDA grew 11.8% to $960 million, but that included $81 million of net IEEPA tariff refund benefits. Strip that out and adjusted EBITDA was roughly flat year over year.
- The adjusted figures also add back $122 million of LIFO inventory charges tied to inflation.
The headline masks an underlying business that is growing volume much faster than earnings power.
The segment split shows where the strain sits:
- **Medline Brand:** sales rose 6.6%, and its adjusted EBITDA margin expanded to 25.9%. However, the tariff refunds were booked entirely in this segment.
- **Supply Chain Solutions:** sales jumped 13.9%, but adjusted EBITDA fell 10.2% as margin compressed to 4.4% from 5.5%.
On the call, management cut the Supply Chain Solutions margin outlook to the mid-4% range from the 4.9%-5% it guided just one quarter earlier. It cited heavier first-year rebates on new business, less favorable renewal economics, and higher operating expenses. Middle East-related inflation is now treated as non-transitory, with the 2026 cost estimate raised to $80 million from $70 million and diesel near $6.25 versus about $5 in the second quarter. Full-year adjusted EBITDA guidance of $3.3-$3.4 billion was merely reaffirmed after being cut on the prior call, and that range excludes the tariff refunds.
The most consequential disclosure was forward-looking. Management's preliminary 2027 framework calls for high-single-digit sales growth but only low-to-mid single-digit adjusted EBITDA growth. That pushes the return to EBITDA growth at or above sales growth out to 2028. Additional headwinds include:
- rising quality spending;
- an exit from a roughly $60 million home care bed line under FDA engagement;
- multi-year quality assessments across more than 30 sites that could surface further issues;
- provider-reported softness in surgical volumes.
Bears have legitimate ammunition here. Growth is being bought at the expense of margin, and the timeline for that to reverse just slipped a year.
The offsets are real, though:
- Free cash flow reached $1.8 billion through nine months, versus $920 million at the half.
- Net leverage fell to 2.5x from 2.9x last quarter.
- The company authorized its first-ever $1 billion buyback and prepaid $750 million of term debt.
- A restructuring program carries a $20-$30 million fourth-quarter charge in exchange for $80-$90 million in annualized savings, mostly landing in 2027.
- A larger-than-usual price increase in the first quarter of 2027 should recapture part of the inflation.
- Commercial momentum looks intact. Lab and diagnostics growth accelerated to 14% from 12% in Q2 and 1% in Q1, new customer signings remain on track for the $1 billion goal, the Canadian prime vendor rollout is underway, and new distribution centers in Dallas-Fort Worth, Southern California and Michigan, plus the rebuilt Tracy facility, add capacity.
The market had already priced in plenty of skepticism. Shares at $34.09 were down 8.6% from the open after the August report and sat 13.9% below the 200-day moving average of $39.57. The stock set a 52-week low of $31.37 on October 30 before bouncing 8.7% into the print. Investor sentiment deteriorated meaningfully over the quarter, falling from -0.19 to -0.50, which signals low expectations heading into the release. The Earnings Whispers AVWAP trend remains negative and momentum is neutral, consistent with a stock that has been under steady pressure rather than one already repairing.
The bottom line is that Medline delivered a clean beat and another guidance raise on sales, but the earnings quality is weaker than the headline suggests. Tariff refunds propped up adjusted EBITDA, Supply Chain Solutions margins are sliding, and management has now conceded that profit growth will lag sales through 2027. Strong cash generation, deleveraging and a new buyback give the stock support with sentiment this depressed. Still, the debate has shifted from whether Medline can grow to when that growth will translate into margin, and the answer just moved further out.
Read our earnings preview for Medline Inc.: https://www.earningswhispers.com/article/MDLN/21716
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 4 hours | |
| 4 hours | |
| 6 hours | |
| 13 hours | |
| 13 hours | |
| Nov-02 | |
| Oct-27 | |
| Oct-15 | |
| Oct-12 | |
| Oct-06 | |
| Oct-06 | |
| Oct-02 | |
| Sep-28 | |
| Sep-24 | |
| Sep-08 |
