Owens Corning Must Prove Its Recovery Survives A Roofing Hangover And Rising Costs
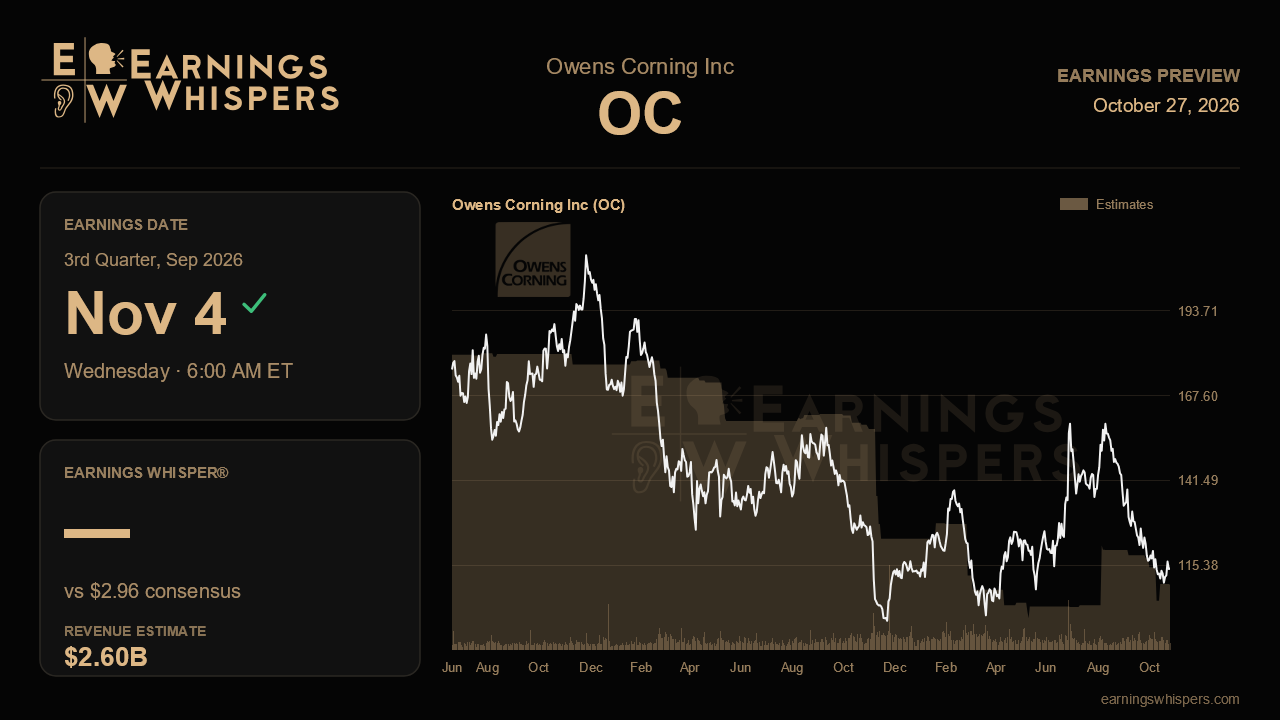
Owens Corning heads into its third-quarter report with a credibility problem that has nothing to do with its last set of numbers. The building materials maker delivered a 24% adjusted EBITDA margin and $3.93 a share in the second quarter, and management spoke openly about the earnings power of a reshaped company. The stock has since fallen 23.3%, trailing the S&P 500 by nearly 22 percentage points. The market is treating that quarter as a peak rather than a turn, and this report is the first real chance to settle the argument.
The bar has been set low. Analysts expect earnings of $2.96 a share, down 19.4% from a year ago, on revenue of $2.60 billion, a 3.1% decline. Management guided to revenue of $2.60 billion to $2.70 billion. When that range was issued the Street sat at the top of it, and estimates have since drifted to the bottom. Consensus now assumes the company merely clears the floor of its own outlook. Management's 20% to 22% enterprise EBITDA margin guide, applied to that revenue figure, points to EBITDA in the low-to-mid $500 million range. That makes any result near the upper end of either range a meaningful upside surprise.
Roofing is the main reason for the expected step down, and management told investors this was coming. Distributors bought heavily ahead of a June price increase. That pulled volume into the second quarter and left the channel carrying more inventory. The company guided roofing revenue down mid-to-high single digits and industry shipments down high single digits, with segment margin slipping about 400 basis points to roughly 30%. If the decline comes in as described, it should read as timing rather than a demand problem. The bigger concern would be fourth-quarter commentary suggesting distributors are still working down stock, because that would turn a one-quarter hangover into a longer volume drought.
Insulation is where the recovery story either holds or cracks. After several quarters of declines, segment revenue grew 4% in the second quarter. Management guided to mid-single-digit growth, citing data centers, commercial work and a European rebound it had been flagging for a year. Delivering that growth would show the improvement was more than a single good quarter. Margin also matters. Insulation earned 22% last quarter against a 24% long-term target, held back by inflation and residential pricing, so progress toward that goal would carry weight. Investors should also look for updates on the Nephi, Utah restart planned for the fourth quarter and the Kansas City commercial line due next year.
Costs are the swing factor running through every segment. Price still trailed costs in all three businesses heading into the quarter. Management also expected roughly $40 million of net inflation tied to the Iran conflict as higher-cost inventory flows through. In Doors, $135 million of synergies have been captured and another $75 million of structural savings are starting to show up. However, the segment's 11% margin last quarter was helped by tariff refunds that will not repeat, so a clean margin near that level would be encouraging.
Sentiment has cooled slightly, with bullish readings easing to 15.8% from 17.3%. The shares sit at $114.26, well below the 200-day moving average and only about 5% above the post-earnings low of $108.98. That positioning suggests much of the expected roofing slump is already priced in. The central question is whether price increases can finally catch up to inflation and whether insulation can carry the load while roofing digests its pull-forward. Without a narrowing price/cost gap, the new Owens Corning will look a lot like the old one.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-14 | |
| Oct-07 | |
| Sep-17 | |
| Sep-16 | |
| Aug-05 | |
| Aug-05 | |
| Aug-05 | |
| Aug-05 | |
| Jul-29 | |
| Jul-15 | |
| Jun-29 | |
| Jun-29 |
Construction-Products Supplier Carlisle Made Unsolicited Offers for Rival
OC +15.26%
The Wall Street Journal
|
| Jun-18 | |
| May-06 |
