Nomad Foods Faces First Real Test Of Its Promised Second-Half Margin Rebound
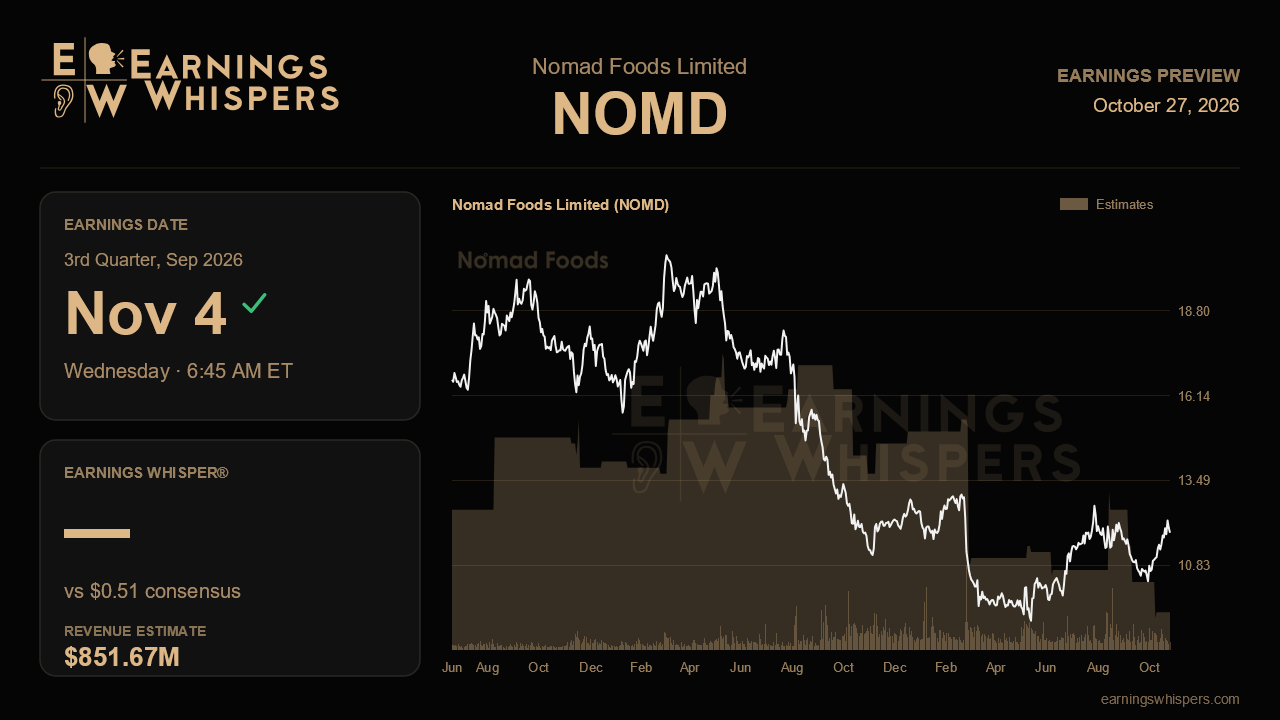
Nomad Foods enters its third-quarter report with a story that sounds better than its numbers. Last quarter management declared the German and French retailer disputes fully resolved, said gross margin had returned to growth as pricing took hold, and pointed to private-label rivals finally raising fish prices by 20% to 32%. Yet Wall Street still expects a smaller, less profitable quarter than a year ago. The November 4 release, due before the open, is where the turnaround narrative has to start appearing in the income statement rather than just on the conference call.
Consensus calls for earnings of $0.51 per share on revenue of $851.7 million, down 10.5% and 3.2% respectively from last year's $0.57 and $879.5 million. That is still contraction, but the sequential picture matters more here. Second-quarter EPS was $0.45 on $841.3 million in sales, so analysts are modeling a meaningful step up in profitability on only modestly higher revenue. That is exactly the second-half margin recovery management laid out earlier in the year. Full-year guidance of $1.59 to $1.76 per share was reaffirmed, and the $1.63 consensus sits near the bottom of that range. The Street, in other words, believes the plan but is not paying for the midpoint.
The most important evidence will be on gross margin. Management attributed last quarter's improvement to price increases kicking in, while the €200 million productivity program, including a factory closure and a marketing restructuring, was meant to let Nomad pass on fish cost inflation without widening its price gap to store brands. A clean margin expansion this quarter would validate that combination. A stall would raise awkward questions, because fish and protein inflation is expected to persist into 2027 and management said it was too early to judge how shoppers would react to the new prices. Volume trends are the tell. The frozen category has been healthy, growing 3.4% in value and 1.6% in volume year to date, though the most recent three months showed slight cooling. If Nomad's own volumes held up as private label caught up on price, elasticity fears fade.
Market share is the softer spot. Management conceded share ran below target in the first half and said getting back to neutrality would take more time, declining to offer a date. With retailer disruptions now behind it and competitors' price increases landing in July, the third quarter is the first period where the company has no obvious excuse. Even modest sequential share improvement would suggest the delay is a matter of timing; continued slippage would imply something stickier about brand positioning versus store brands.
Capital allocation adds another layer. Nomad suspended buybacks last quarter to prioritize debt reduction without naming a leverage target, a sharp reversal from its earlier enthusiasm for repurchasing stock at a single-digit earnings multiple. Any clarity on cash generation and deleveraging pace, particularly in light of the multi-year plan management promised to present at its October investor day, would help investors judge how long shareholder returns stay on hold.
The market has leaned in anyway. Shares have climbed 8.4% since the last report while the S&P 500 slipped 1.2%, and at $11.85 the stock sits above its 200-day moving average, though still about 6% below its post-earnings high of $12.56. Sentiment, by contrast, has grown more bearish than it was heading into last quarter, a sign that skeptics remain unconvinced even as the price improves. That leaves a stock that has priced in some recovery and a crowd that doubts it. The verdict will hinge on whether pricing delivers margin gains without costing Nomad more volume and share, because that is the trade-off on which the entire second-half thesis rests.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 5 hours | |
| Oct-21 | |
| Oct-06 | |
| Sep-22 | |
| Sep-15 | |
| Sep-15 | |
| Sep-03 | |
| Aug-17 | |
| Aug-13 | |
| Aug-13 | |
| Aug-13 | |
| Jul-30 | |
| Jul-30 | |
| Jul-30 | |
| Jul-30 |
