Nomad Foods Beats As Organic Growth Returns, But Margin Erosion And Fish Inflation Keep The Recovery Unproven
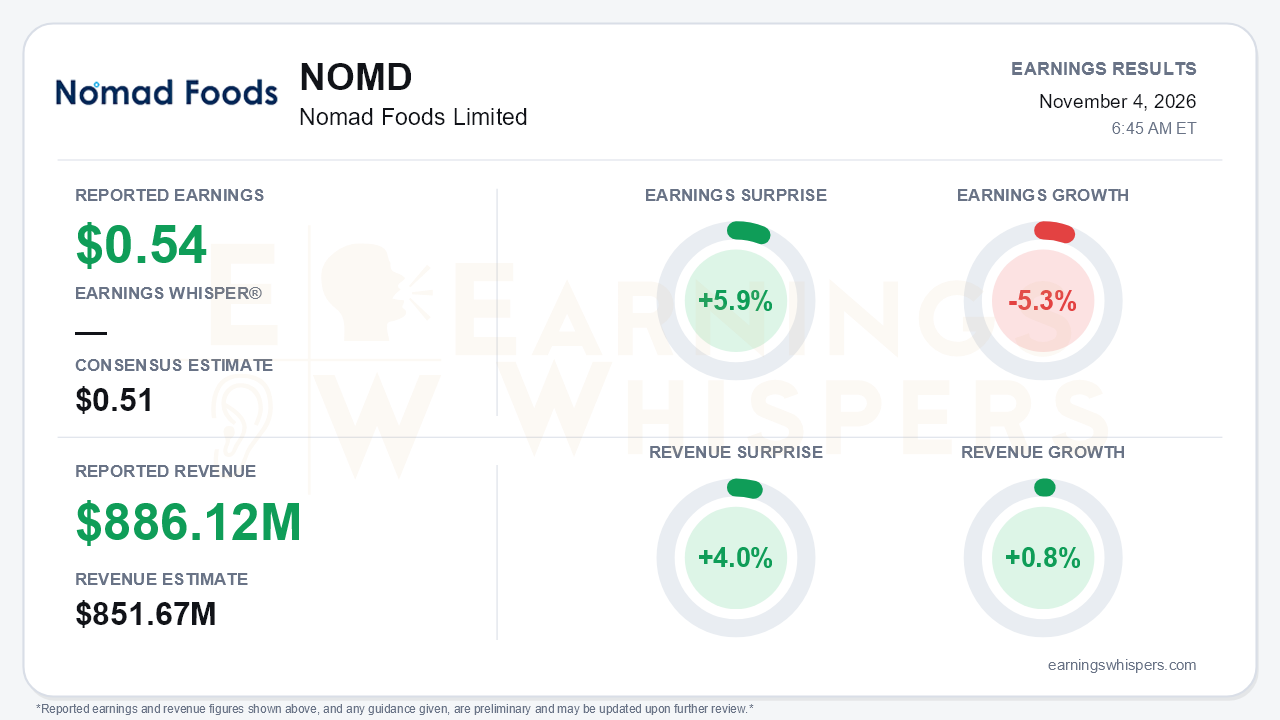
Nomad Foods (NYSE: NOMD) delivered the milestone management has been promising: a return to organic growth. Third-quarter earnings of $0.54 per share beat the $0.51 consensus by 5.9%, and revenue of $886.12 million topped expectations by 4.0%. Profitability did not recover with sales, though. Earnings fell 5.3% year over year while revenue grew just 0.8% in dollar terms, and the company's euro-reported revenue rose 2.3%. The quarter is best read as a top-line inflection without a matching earnings inflection. That is the central tension.
The quality of the beat deserves scrutiny. Organic revenue rose 1.6%, with volume essentially flat at -0.2%, the first flat-volume quarter since 2024, and price/mix adding 1.8%. Those gains did not reach the margin line. Adjusted gross margin fell 110 basis points to 27.0%. Adjusted EBITDA slipped 1.5% to €141 million, and EBITDA margin narrowed to 18.2% from 19.0%. Management attributes much of the pressure to restored incentive compensation, a mid-single-digit EBITDA headwind, and to the reversal of second-quarter timing benefits. Excluding those items, adjusted gross profit grew low-single-digits.
The per-share result also leaned on a smaller share base. Adjusted profit fell 7% to €67 million, but adjusted EPS declined only 4.1% to €0.47 because diluted shares dropped to 140.3 million from 147.9 million. Reported IFRS diluted EPS jumped 21% to €0.47. That increase came largely from exceptional charges shrinking to €3.9 million from €16.9 million, not from operating improvement. Net financing costs also rose, partly because of a €7.6 million loss on debt refinancing.
Cash flow was a cleaner positive. Nine-month operating cash flow rose to €195.6 million from €174.2 million, helped by lower exceptional payments and lower tax paid. Buybacks fell to €23.7 million from €151.4 million, consistent with the buyback suspension disclosed last quarter and the stated priority of deleveraging. Gross borrowings remain above €2.3 billion.
The call preserved a credible stabilization story. Management reaffirmed full-year guidance:
- organic revenue down 2%-3%;
- Adjusted EBITDA down 5%-10%;
- Adjusted EPS of €1.38-€1.53;
- free cash flow conversion of 90% or better.
It also restated the 2027 framework from its October investor day: roughly 7% gross inflation, about 3% savings and 0-2% EBITDA growth. Several new growth levers emerged:
- a first discounter-channel win, with more in the pipeline;
- another small factory closure and lower indirect costs;
- modestly positive restocking orders after cyber attacks hit retailer freezer systems in France, Belgium and other markets.
Bears still have legitimate ammunition. Additional fish inflation means fourth-quarter EBITDA is implied to decline year over year. Management also acknowledged a wide fourth-quarter range because customer reaction to a second off-cycle price increase is uncertain. That echoes the retailer disruptions that hurt the first half. Advertising and promotion spending is down as non-working media is cut. Management said any upside will be reinvested in incentive compensation rather than lifting guidance, which caps flow-through. Category growth has cooled from 3.8% in the first quarter to 2.8% over the trailing three months cited on the second-quarter call. Management has also not set a date for reaching market-share neutrality. The nine-month record still shows volume down 3.5% and adjusted EBITDA down 9%, so one flat-volume quarter does not undo a difficult year.
The market setup is more complicated than the surprise implies. Investor sentiment, measured before the report, grew more negative, falling from -0.14 to -0.29, a meaningful but not extreme shift. Price action told a different story. The stock rose 12.1% since the opening after the August report, to $12.25, and sat 11.4% above its 200-day moving average of $10.99. It entered earnings just 2.5% below its inter-earnings high of $12.56 after a nearly 20% rebound from the October 1 low of $10.25. That rebound came around the investor day that reset expectations. The Earnings Whispers trend readings lean positive on price, sequential growth and AVWAP, with momentum neutral. Shares therefore came into the print having already priced in part of the recovery narrative.
The bottom line is that Nomad delivered the volume stabilization and organic growth that turnaround skeptics doubted, along with a clean beat and better cash generation. Earnings are still shrinking, margins are still compressing, and fourth-quarter fish inflation plus an uncertain price increase leave little cushion. With guidance only reaffirmed, the stock trading near its post-August highs and sentiment souring, this looks like a reaffirmation quarter rather than a proven inflection. The next test is whether pricing and productivity can turn top-line growth into earnings growth as 2027 inflation arrives.
Read our earnings preview for Nomad Foods Limited: https://www.earningswhispers.com/article/NOMD/21721
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 5 hours | |
| 5 hours | |
| Oct-30 | |
| Oct-27 | |
| Oct-21 | |
| Oct-06 | |
| Sep-22 | |
| Sep-15 | |
| Sep-15 | |
| Sep-03 | |
| Aug-17 | |
| Aug-13 | |
| Aug-13 | |
| Aug-13 |
