Performance Food Group's Year Of Acceleration Faces Early Test As Street Drifts To Low End
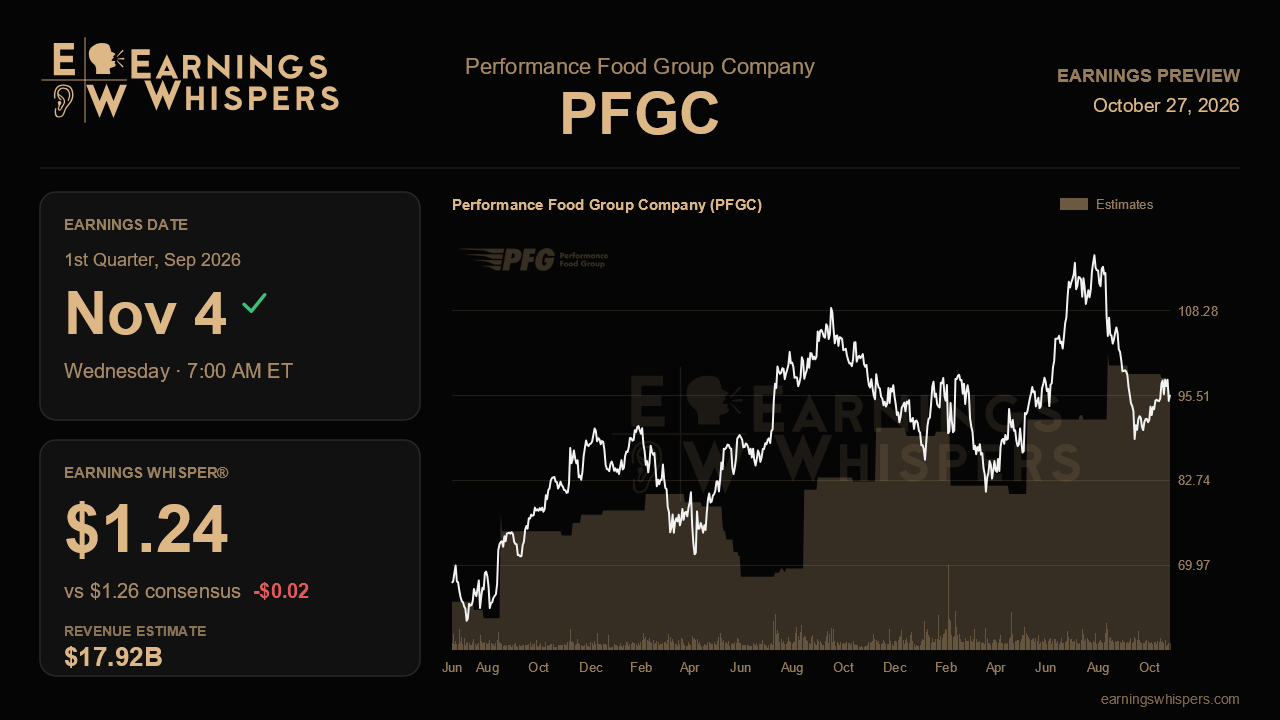
Performance Food Group closed its fiscal year in August sounding more confident than it had in a year, promising that fiscal 2027 would be a year of acceleration as integration costs faded and procurement savings built. The market has not bought the pitch. Shares have fallen 9.6% since that report, trailing the S&P 500 by more than eight percentage points, and the first-quarter results due before the opening bell on November 4 are the first chance to show that the acceleration story is more than a back-half promise.
The bar is modest. Analysts expect earnings of $1.26 a share, up 6.8% from $1.18 a year ago, on revenue of $17.92 billion, a gain of 4.9%. The Earnings Whisper sits a touch lower at $1.24, a small gap but one that hints at some caution in the crowd. More telling is where revenue estimates have landed relative to guidance. Management guided first-quarter sales to $17.90 billion to $18.10 billion, and when that range was issued the Street was sitting at $18.14 billion. Consensus has since slipped to the very bottom of the company's range. For the full year, management's $72.5 billion to $73 billion outlook sat above where analysts had been, so the Street is effectively saying it believes the annual guide but expects the opening quarter to be soft.
That skepticism has a basis. Fiscal 2027 guidance calls for roughly 7.2% sales growth and 12.7% EBITDA growth at the midpoint, yet the first quarter is expected to grow revenue under 5%. The gap depends on things that arrive later: Jersey Mike's onboarding in three of four regions during the second half, a 53rd week that contributes about two points of EBITDA growth, and synergies that ramp over time. Meanwhile, management flagged near-term drags that hit this quarter squarely, including a fuel headwind of about $16 million similar to the fourth quarter, specialty operating cost pressure lingering through the first half, and competitive convenience losses where PFG declined to match prices it considered too low.
The cleanest proof of the thesis would be margin. Gross profit per case rose $0.34 in the fourth quarter, the best of the year after two quarters at $0.20, and that improvement reflected Cheney and Florence integration costs fading and procurement savings kicking in under a target now raised to $120 million to $125 million. Holding gains near that level, despite fuel, would suggest the earnings engine is improving underneath the top line. Independent case growth is the other key gauge. It cooled to 5.8% last quarter from 6.5%, just shy of the company's 6% goal, and a further slide would be hard to blame on comparisons alone. Chain volume, which turned slightly negative as restaurant traffic stayed weak, and convenience organic growth, which is lapping big Loves and Racetrack wins, will show how much ground the company must make up before Jersey Mike's arrives. Investors should also watch below the line, since higher interest and depreciation held fourth-quarter adjusted EPS growth to just 2.6% despite strong gross profit.
Sentiment has swung from 20.5% bullish ahead of the last report to slightly bearish now, and the stock sits at $95.63, below its 200-day average of $97.22 and in the lower third of its post-earnings range between $88.95 and $112.12. That combination suggests expectations have been reset lower, which gives a clean quarter room to be rewarded.
Ultimately, the report hinges on whether PFG can show margin expansion and stable independent volume while absorbing its known first-quarter headwinds. If it does, and reaffirms the annual guide, the acceleration narrative stays intact. If margins slip back toward last year's middle quarters, the market's doubts about a back-loaded year will look justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-14 | |
| Sep-02 | |
| Sep-02 | |
| Aug-27 | |
| Aug-20 | |
| Aug-12 | |
| Aug-12 | |
| Aug-12 | |
| Jul-22 | |
| Jul-07 | |
| May-06 | |
| May-06 | |
| Apr-22 | |
| Feb-24 |
