Performance Food Group Beats On Margin Execution, But Holds Full-Year Guidance As Inflation And Growth Cool
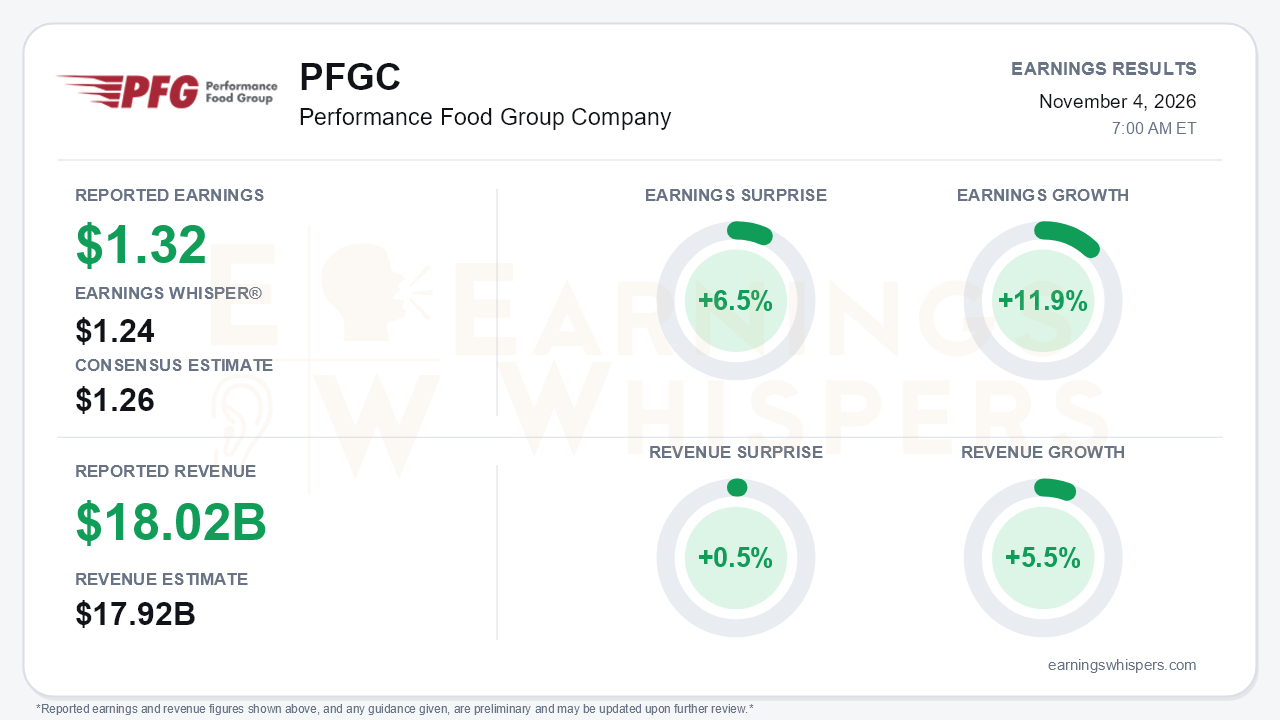
Performance Food Group delivered a clean fiscal first-quarter beat, earning $1.32 per share on an adjusted basis against a $1.26 consensus estimate and a $1.24 Earnings Whisper number. That is a 6.5% surprise and 11.9% year-over-year growth. Revenue of $18.018 billion rose 5.5% and edged past the $17.92 billion consensus by 0.5%. Adjusted EBITDA climbed 10.0% to $528.0 million, at the top of management's $510-530 million guide. EBITDA growth has now accelerated for three straight quarters, from 6.6% in fiscal Q3 to 7.4% in Q4 and 10% now. The central tension is that profit growth is accelerating just as the top-line drivers are cooling. Management reaffirmed its full-year outlook rather than raising it.
The quality of the beat is generally good, with one caveat. Gross profit grew 8.5%, outpacing the 6.9% rise in operating expenses. Gross margin expanded 33 basis points and gross profit per case rose about $0.30. The drivers were vendor rebates, a richer mix toward independent restaurants, and Performance Brands, which are back above 51% of independent cases. GAAP diluted EPS jumped 36.7% to $0.82, which flatters the trend. The prior-year quarter carried $9.9 million of activism and US Foods clean-team fees, and interest expense fell this year. A higher 25.2% tax rate partly offset those benefits. The adjusted 11.9% growth rate is the better gauge.
Beneath the consolidated numbers, the business is increasingly a Foodservice story:
- **Foodservice:** Segment EBITDA rose 13.4%. Independent sales reached a record 43% of the segment, and organic independent cases grew 5.5%.
- **Convenience:** EBITDA rose only 3.8%. Revenue growth is slowing as the Love's and RaceTrac wins are lapped.
- **Specialty:** EBITDA fell 4.8% despite 10.3% sales growth. Management cited tough candy inventory-gain comparisons, competitive pressure, third-party parcel fuel costs, and renegotiated long-term contracts.
The call also showed the independent growth engine cooling gradually. Organic independent case growth has stepped down from 6.5% in fiscal Q3 to 5.8% in Q4 and 5.5% now. Management did note a third consecutive quarter of better penetration into existing accounts, and quarter-to-date trends running slightly ahead of the Q1 exit rate.
The forward picture explains why the guidance stayed put. Foodservice inflation fell to 0.5% from 2.7% in the prior quarter. Management now expects inflation at the bottom of the low-single-digit range, with slight deflation possible, which removes a pricing tailwind. The second-quarter sales guide of $17.0-17.2 billion implies roughly 4% growth, a step down from 5.5% in Q1. Other headwinds include:
- Diesel above $4 per gallon, a net cost of about $16 million in Q1 that management expects to repeat in Q2.
- The full-year tax rate moving up to about 27%.
- Restaurant traffic down about 2%, with pressure on QSR and lower-income consumers, softness in the Southeast, and chain cases slightly negative.
- Net debt at the top of the 2.5-3.5x leverage target.
Free cash flow improved but remained negative at -$143.2 million, versus -$224.1 million a year ago. Against all that, the catalysts are tangible. Procurement savings are now pinned at the upper end of the Investor Day range, about $125 million by the end of fiscal 2028. Jersey Mike's begins onboarding in February across three of four regions, at margins in line with the chain business. Convenience branded food programs grew cases 11%.
Investor expectations had cooled sharply heading into the print. Earnings Whispers sentiment fell from 0.21 after the August report to roughly neutral at -0.03, a meaningful shift from moderately positive to slightly negative. The stock reflected that. Shares closed at $96.51 the day before the report, down 8.8% from the $105.79 open following the prior release. They sat about 13.9% below the inter-earnings high of $112.12, which was set on that August report day. The stock had recovered 8.5% off its mid-September low of $88.95 and entered the print hovering just below its 200-day moving average of $97.38. Momentum and AVWAP readings had turned positive even as the broader price trend remained negative, suggesting stabilization rather than a confirmed recovery.
The bottom line is that PFG showed it can grow earnings faster than sales through procurement, mix, and private-label execution, and the beat was genuine at the operating level. But management chose to reaffirm rather than raise full-year targets, and Q2 guidance implies slower sales growth. With inflation fading, fuel costs elevated, Convenience and Specialty lagging, and leverage at the top of its range, the beat buys credibility more than upside. The next test is whether margin initiatives and Jersey Mike's can offset a softer top line through the back half of fiscal 2027.
Read our earnings preview for Performance Food Group Company: https://www.earningswhispers.com/article/PFGC/21728
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Oct-27 | |
| Oct-14 | |
| Sep-02 | |
| Sep-02 | |
| Aug-27 | |
| Aug-20 | |
| Aug-12 | |
| Aug-12 | |
| Aug-12 | |
| Jul-22 | |
| Jul-07 | |
| May-06 |
