OPENLANE Must Show Off-Lease Supply Can Offset Cooling Dealer Growth After Two Guidance Raises
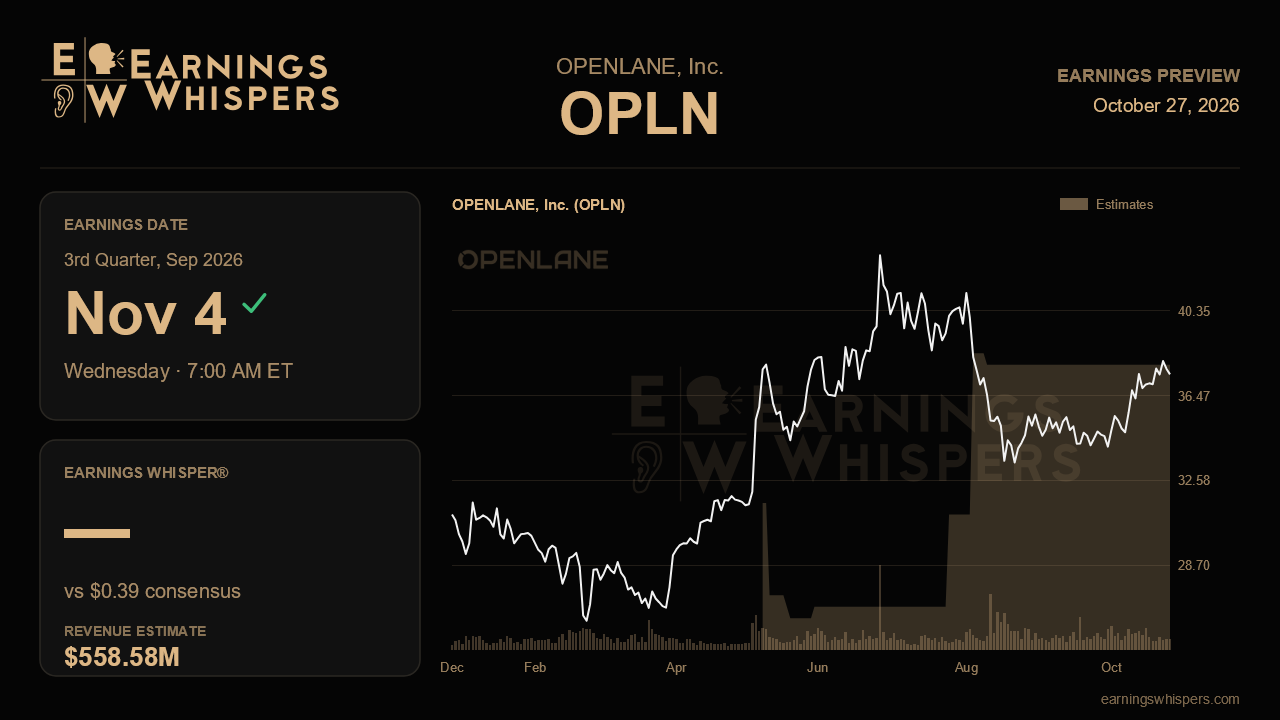
OPENLANE heads into its third-quarter report with an unusual mismatch between its operating story and its stock. Management has raised its full-year outlook in each of the last two quarters, marketplace volume accelerated sharply last quarter, and credit trends at its AFC dealer finance arm improved. Yet the shares have slipped 4.3% since the last report, trailing the S&P 500 by nearly 5 percentage points, and sentiment has cooled noticeably. The quarter now has to answer a simple question: was the second quarter a high-water mark, or the middle of a longer upswing?
The Street is looking for earnings of $0.39 a share on revenue of $558.6 million, essentially flat with the $0.40 and $554.6 million posted last quarter. That is a modest bar on its face. The more revealing comparison is with guidance. OPENLANE lifted its 2026 earnings outlook to $1.40 to $1.50 a share, and consensus sits right at $1.40, the bottom of that range. Adjusted EBITDA guidance has climbed to $385 million to $400 million, but the first half already delivered about $200 million, which implies a second half running somewhat below the second-quarter pace of $103 million. Some of that reflects planned spending, since management said it is adding go-to-market investment, split roughly evenly between operational infrastructure and sales, in the back half of the year. Still, the arithmetic leaves room for upside if volumes hold, and analysts parked at the low end suggest the market is not pricing much of it.
The central operating test is the handoff between two growth engines. Management explicitly warned that US dealer growth, which hit a multi-year best of 31% in units last quarter, will temper in the second half against harder comparisons. The offset is supposed to come from off-lease supply, with US lease maturities expected to rise 20% to 25% in the second half. That inflection has been slower to arrive than hoped, because elevated used-car values have left consumers with equity in their leases, keeping payoffs high and slowing the flow of vehicles down to the open marketplace. Evidence that commercial volumes excluding the new OEM private-label customer are building on last quarter's 14% growth would validate the thesis. Another quarter of stalled waterfall flow and slipping commercial yields would challenge it, particularly as the new OEM customer moves toward lapping its own launch.
Margins are the second swing factor. The marketplace segment expanded its EBITDA margin to 13% despite more than 100 basis points of fuel-driven transport pressure, and management indicated pricing resets lag cost spikes. If that lag has closed, margins could surprise favorably. At AFC, the provision for credit losses improved to 1.17%, but the net finance margin slid to 12.8%, and receivable growth consumed roughly $45 million of cash, pushing trailing free cash flow conversion to 62%, below the 65% to 75% target. A rebound toward that range would ease a quiet but real concern. Canada, where dealer GMV fell 15% on tariff-related comparisons, and early traction for the MyLot inventory tool, now used by more than 800 dealers, round out the secondary checks.
Technically, the stock sits at $37.44, comfortably above its 200-day moving average near $34 and roughly in the middle of its post-earnings range of $33.11 to $42.69, so neither a breakout nor a breakdown is imminent. Bullish sentiment has fallen to 18.9% from 31.6% a quarter ago, a meaningful retreat that lowers the emotional bar.
Ultimately, the report hinges on whether off-lease supply is finally loosening fast enough to carry growth as dealer comparisons stiffen. If it is, a third guidance raise and a move toward the upper half of the range look plausible. If not, the cautious low-end consensus may prove to have been the right call.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-07 | |
| Aug-11 | |
| Aug-11 | |
| Aug-06 | |
| Aug-04 | |
| Aug-04 | |
| Aug-04 | |
| Jul-08 | |
| Jun-22 | |
| Jun-12 | |
| Jun-02 | |
| May-05 | |
| May-05 | |
| Apr-14 |
