OPENLANE Beats On Margins And Commercial Mix, But Slowing Dealer Growth And A Merely Narrowed Outlook Temper The Quarter
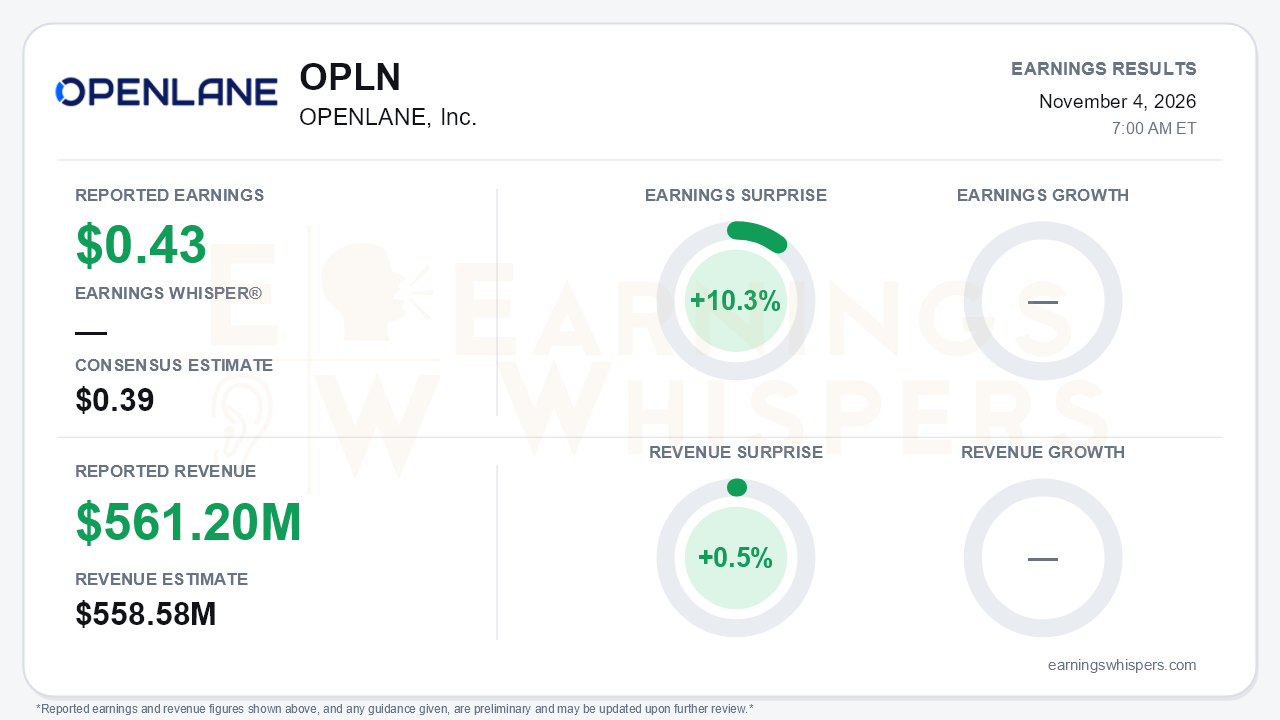
OPENLANE delivered a clean third-quarter beat, but the forward picture is less tidy than the headline suggests. Operating Adjusted EPS of $0.43 topped the $0.39 consensus by 10.3%, up from $0.35 a year ago. Revenue of $561.2 million edged past the $558.58 million estimate by 0.5%. Adjusted EBITDA rose 23% to $107 million, extending a run of improvement from $97 million (+17%) in Q1 and $103 million (+19%) in Q2. The central tension is that profitability is accelerating while top-line momentum is cooling. Revenue growth slowed to 13% from 15% in each of the first two quarters, U.S. dealer volume growth decelerated, and management only narrowed its full-year outlook rather than raising it outright.
The quality of the beat deserves some scrutiny. GAAP net income actually fell to $44.7 million from $47.9 million. Corporate interest expense jumped to $10.0 million from $1.1 million, and income taxes nearly doubled. Even so, GAAP diluted EPS rose to $0.36 from $0.25 because the Series A Preferred Stock no longer siphons off dividends and participating earnings. Weighted diluted shares on a converted basis fell to 125.4 million from 144.0 million. Capital structure and repurchases are doing meaningful work in the per-share figures. Underlying operations still improved: auction and related fees grew 18% to $253.2 million, operating profit rose to $70.4 million from $55.0 million, and operating cash flow climbed 34% to $97 million.
The call showed the mix beneath the headline shifting. Commercial is now the stronger engine. Commercial units rose 46%, or 17% excluding a new OEM program, accelerating from 14% in Q2 and 6% in Q1, as the off-lease inflection builds. U.S. commercial yield recovered to 0.68% from 0.63%, and open-sale commercial units roughly doubled. Marketplace adjusted EBITDA margin expanded 170 basis points year over year, up from 80 basis points in Q2, as the prior quarter's fuel-cost drag faded. Dealer trends moved the other way. U.S. dealer units grew 22%, still well ahead of the industry, according to management, but down from 31% in Q2 and the upper-20s in Q1. Steeper-than-normal used-vehicle price declines are pressuring conversion, a headwind management expects to persist through Q4. Canada deteriorated rather than turning as hoped, with dealer GMV down 17%. Sequentially, auction revenue slipped to $253 million from $259 million, and GMV eased to $10.0 billion from $10.5 billion.
The most important forward-looking development is competitive. Management views the acquisition of a primary digital competitor as a share-capture opportunity and is pulling 2027 sales and operations hiring into Q4. Second-half go-to-market spend is rising to the low double-digit millions from mid-single digits. Bulls can argue this is offense at an opportune moment, and the board added $150 million to the buyback, lifting authorization to $400 million with about $250 million remaining. Bears have legitimate ammunition as well. AFC's loss rate is expected to rise to roughly 1.5% in Q4 from 1.14%, net finance margin compressed 70 basis points, and the investment spend lands just as Q4 faces a tough comparison against an abnormally strong Q4 2025.
Guidance captures the ambiguity. Earnings Whispers characterizes the update as a raise in line with estimates. Technically, both midpoints moved up: adjusted EBITDA narrowed to $390-$400 million from $385-$400 million, and Operating Adjusted EPS to $1.45-$1.52 from $1.40-$1.50. However, the high end of EBITDA guidance was unchanged. That breaks a pattern of clear raises in Q1 and Q2. Against nine-month results of $306.7 million in adjusted EBITDA and $1.18 in Operating Adjusted EPS, the range implies a seasonally softer fourth quarter well below Q3's run rate.
Investors appear to have anticipated a less exuberant setup. Earnings Whispers sentiment fell from 0.32 to 0.06, a meaningful cooling that leaves sentiment only marginally positive. Shares closed the pre-report period at $38.88, essentially flat (-0.6%) from the $39.11 open after the August report. That masks a volatile quarter: the stock spiked to $42.69 the day after the last report, slid to $33.11 within three weeks, and then recovered. It sits 13.6% above its 200-day moving average but 8.9% below the inter-earnings high. Momentum and AVWAP trend readings remain positive, consistent with a stock that has repaired much of its August drawdown.
The bottom line is that OPENLANE's quarter was operationally solid, with accelerating EBITDA, a building commercial off-lease cycle, and strong cash generation. Growth leadership, however, is rotating away from the dealer business that powered the first half. The competitor's exit creates a genuine share opportunity, but the company is paying for it upfront while used-car pricing, Canada, and credit losses lean the wrong way. The narrowed guidance suggests management sees more balance than acceleration into year-end.
Read our earnings preview for OPENLANE, Inc.: https://www.earningswhispers.com/article/OPLN/21727
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Oct-27 | |
| Oct-07 | |
| Aug-11 | |
| Aug-11 | |
| Aug-06 | |
| Aug-04 | |
| Aug-04 | |
| Aug-04 | |
| Jul-08 | |
| Jun-22 | |
| Jun-12 | |
| Jun-02 |
