Perrigo's Rally Meets Its Test As Q3 Must Prove The OTC Demand Turn Is Real
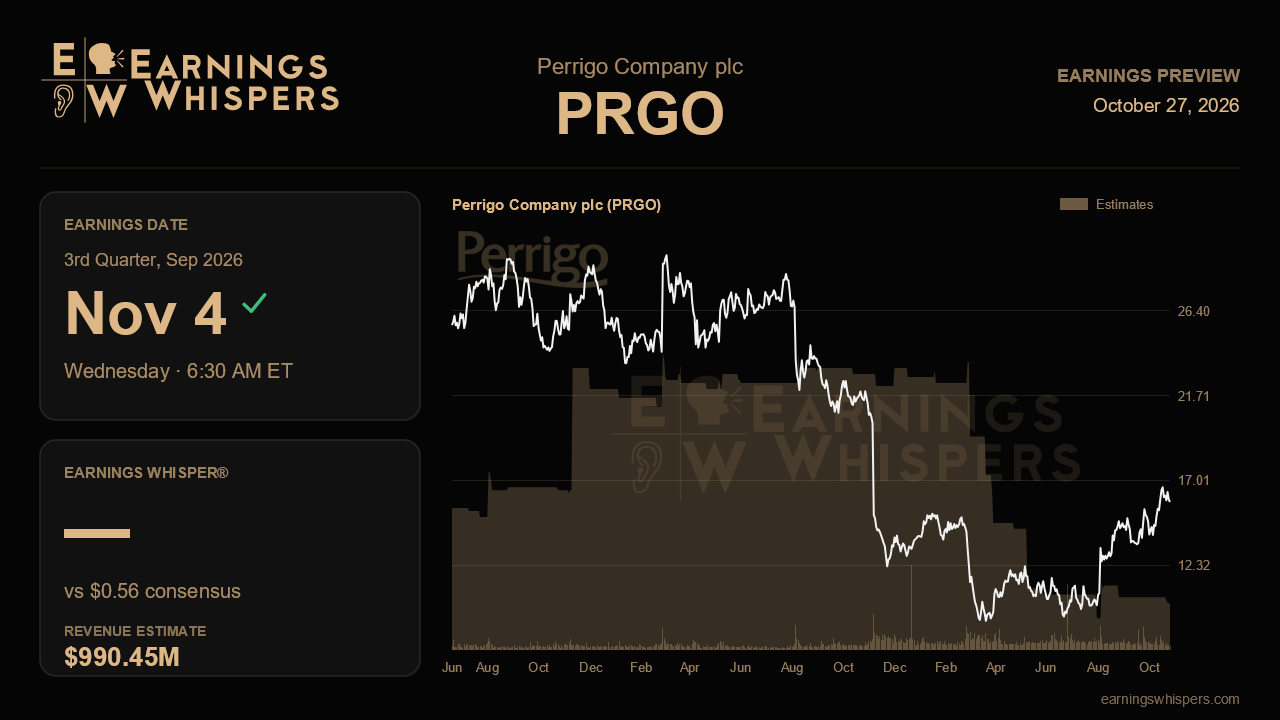
Perrigo heads into its third-quarter report with a stock that has already priced in a fair amount of hope. Shares have climbed about 25% since the last report while the S&P 500 slipped, a gap of nearly 27 percentage points, and the reason is easy to identify: management said US over-the-counter volumes in its categories finally turned positive in the four weeks ended July 19. The November 4 release, due before the open, is the first full-quarter look at whether that green shoot grew into a trend or was a brief bright spot in a long stretch of category weakness.
The bar itself is low on paper. Analysts expect earnings of $0.56 a share on revenue of about $990.5 million, which would mean a 30% drop in EPS and a 5.1% revenue decline from a year ago, when Perrigo earned $0.80 on $1.04 billion. That is still a contraction quarter, not a recovery quarter. Management reaffirmed full-year guidance of $2.00 to $2.30 a share on revenue of $4.02 billion to $4.19 billion, and the Street's $2.09 and $4.11 billion sit in the lower half of the range. Analysts, in other words, are taking management at its word without leaning into the upside, which leaves room for a modest beat but also signals skepticism about how much the back half can improve.
That skepticism has a basis. Last quarter's earnings beat leaned on roughly $10 million of tariff recovery and about $6 million of benefit tied to the CEO transition, which is precisely why guidance was held rather than raised. Those items will not repeat, so the third quarter has to stand on operations. The most important line to watch is gross margin. Core gross margin fell 250 basis points to 37.0% in the second quarter, a sharper decline than in the first, largely because of plant under-absorption. Management has flagged roughly 60 cents of full-year under-absorption pressure, and with 44 cents absorbed in the first half, the remaining drag should be lighter. If margins stop deteriorating at the same pace, that would validate the idea that the worst is behind the company. Another steep decline would undercut it.
The demand story needs corroboration on several fronts. Perrigo has been gaining share in US store brand OTC and in Europe, adding another 60 basis points in early July, and a positive category backdrop should finally let those gains show up in reported sales rather than just offset market declines. Infant formula, which swung to an improvement of about $60 million in operating income in the second quarter partly on contract timing, needs to show that its recovery is durable rather than lumpy. In Europe, retailer destocking cost about 1.8% of core sales last quarter; signs that the headwind is fading would be a meaningful positive. Progress on the $80 million to $100 million savings program targeted for 2027 would also help explain how margins rebuild.
Governance adds a layer the numbers alone cannot resolve. Interim CEO Albert Manzone set a confident, execution-focused tone, but the dividend and broader capital allocation are under quarterly review, and any update on leadership or the payout could move the stock as much as the results. Debt fell to $3.3 billion after the $359 million Dermacosmetics sale, which gives management more flexibility in that decision.
Sentiment has softened from 58.3% bearish to 41.9% bearish, still negative but noticeably less gloomy. The stock trades well above its 200-day average near $12.44 and about 6% below its post-earnings high of $16.79, so it has room to run but is not pressing a breakout. The verdict hinges on one question: did the July volume turn carry through the quarter strongly enough to slow margin erosion without help from one-time items? A yes keeps the recovery narrative intact; a no would make the recent rally look premature.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-29 | |
| Oct-29 | |
| Oct-27 | |
| Oct-21 | |
| Aug-27 | |
| Aug-05 | |
| Aug-05 | |
| Aug-05 | |
| Jul-30 | |
| Jul-29 | |
| Jul-22 | |
| Jun-30 | |
| Jun-08 | |
| Jun-08 | |
| May-26 |
