Perrigo's Tax-Aided Beat Masks Its First Core Guidance Cut Of The Year As The Infant Formula Exit Reshapes The Story
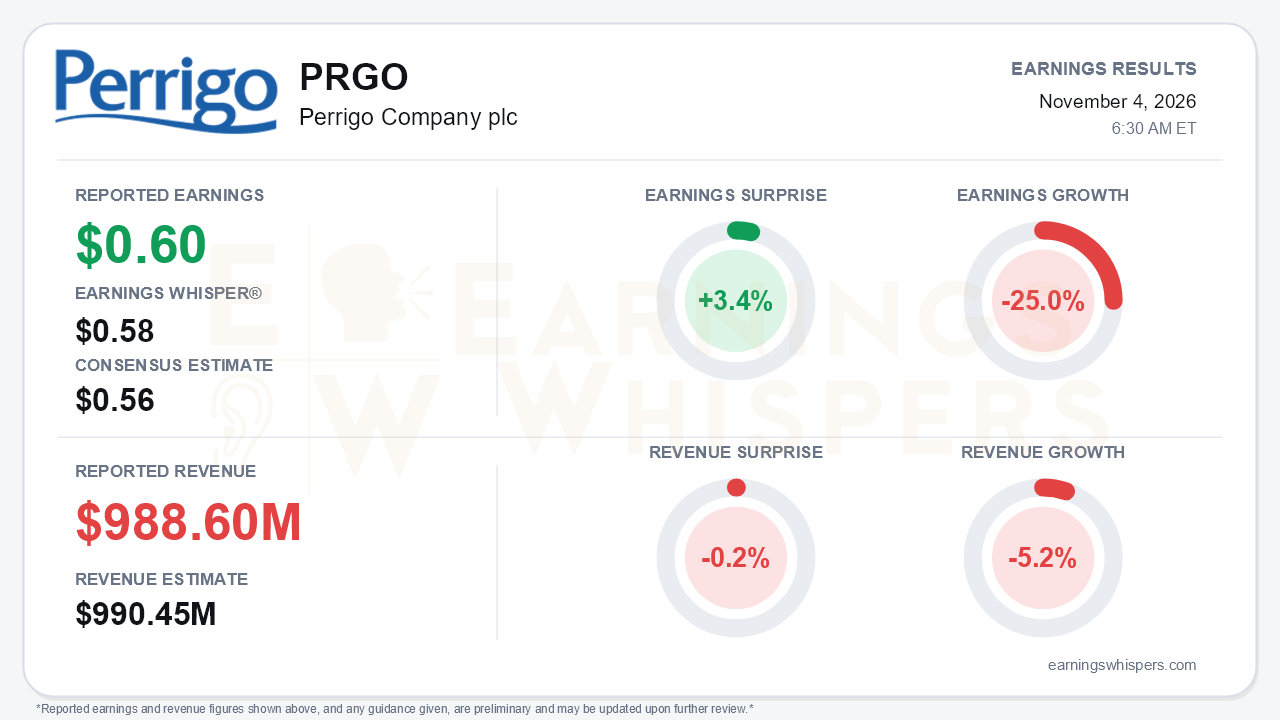
Perrigo (NYSE: PRGO) beat on the headline, but the quarter's real news was a core guidance cut. Adjusted EPS of $0.60 topped the $0.56 consensus by 3.4% and edged past the $0.58 Earnings Whisper. Revenue of $988.6 million came in 0.2% below consensus. Earnings still fell 25.0% year over year and revenue declined 5.2%. On a GAAP basis, continuing operations swung to a $(0.10) per-share loss from a $0.09 profit, weighed down by $41 million of unusual litigation charges. The central tension is that the go-forward business improved sequentially for a third straight quarter while management lowered every core full-year target. That cut ends a streak of three reaffirmations of the same outlook.
The quality of the beat deserves scrutiny. Core adjusted EPS of $0.61 fell 9.0%, and the company says a 3.5% adjusted tax rate added about $0.10. A further $4.5 million came from recovering previously paid tariffs. Without those two items, the core result looks materially weaker. Margins point the same way. Core adjusted gross margin fell 140 basis points to 37.9%, and core adjusted operating margin dropped 210 basis points to 14.3%. The causes were lower volumes, unfavorable mix, production variances and heavier advertising spending. Self Care segment operating income fell 19.4% and Specialty Care fell 24.2%. The All In comparison looks worse still. It absorbed roughly $0.12 of planned under-absorption in Infant Formula, a segment that swung to an operating loss from $15 million a year earlier.
The sequential story is genuinely better. The core net sales decline narrowed from 8.3% in Q1 to 3.1% in Q2 and 1.7% in Q3, with organic sales down just 1.1%. Core adjusted operating margin climbed from 12.8% to 13.4% to 14.3% over the same span. Share gains continued:
- U.S. store brand OTC volume rose 2% and gained 30 basis points of share.
- Key European brands grew value sales 6.5% and gained 80 basis points of share.
U.S. category volume returned to modest growth, and e-commerce now accounts for 22% of U.S. volume. Cost savings from the operational enhancement program reached $42 million year to date, on track for $60 to $80 million in 2026. Those trends are the credible part of the turnaround narrative.
The guidance, however, gives bears legitimate ammunition. Core targets came down across the board:
- Organic sales: now -2.7% to -3.8%, versus -3.5% to +0.5%.
- Adjusted EPS: now $2.15–$2.35, versus $2.25–$2.55.
- Operating margin: now 14%–15%, versus 15%–16%.
- Gross margin: now 37.5%–38.5%, versus 39%–40%.
The EPS cut would have been deeper without the tax-rate assumption falling to about 14% from roughly 18%. Management blamed retailers that declined to build cough/cold inventory after two soft seasons, together with European softness, for roughly two points of headwind. Lower contract manufacturing cost about another point. The second-half acceleration promised since late 2025 has not fully arrived. The All In outlook rose to $2.25–$2.45 from $2.00–$2.30, but that increase largely reflects removing Infant Formula rather than better operations.
The Infant Formula sale is the genuinely new catalyst. Total consideration is up to $175 million, but only $40 million is upfront cash, and the deal will trigger a $275 to $375 million impairment in Q4. The strategic logic is stronger than the price. The sale removes a cash-consuming unit, avoids a previously flagged roughly $240 million network investment, and lifts the margin mix. Several risks remain:
- Year-end net leverage is guided to about 4x, no better than 2025, on $3.3 billion of debt.
- The dividend is still assessed quarterly.
- The Oral Care review is unresolved.
- The CEO is still serving on an interim basis.
The interim CEO avoided 2027 commentary, a sharp contrast with his predecessor's earlier framing of 2027 as a meaningful growth year. Instead he flagged tax normalization, the roll-off of tariff recoveries and inflation as headwinds.
The market setup is more complicated than the surprise implies. Shares rallied 24.4% from $12.62 after the August report to $15.70 ahead of this release. That leaves the stock about 26% above its 200-day moving average and only 6.5% below its October 19 inter-earnings high of $16.79. Investor sentiment remained negative but improved meaningfully, rising from -0.58 to -0.47. Price and AVWAP trend readings are positive, but sequential growth and momentum readings are only neutral. In short, the stock entered the report pricing in a recovery that the lowered guidance now pushes further out.
The bottom line is that Perrigo delivered a modest, tax-assisted beat and real sequential progress in its core business. It also cut core guidance for the first time this year and offered no 2027 roadmap. The Infant Formula exit simplifies the portfolio and improves the margin mix. Even so, leverage is stuck near 4x, Q3 earnings leaned on a temporarily low tax rate and one-time tariff recoveries, and leadership is still interim. After a near-25% run, the stock has less room for a recovery that keeps slipping to the next season.
Read our earnings preview for Perrigo Company plc: https://www.earningswhispers.com/article/PRGO/21731
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Oct-30 | |
| Oct-29 | |
| Oct-29 | |
| Oct-27 | |
| Oct-21 | |
| Aug-27 | |
| Aug-05 | |
| Aug-05 | |
| Aug-05 | |
| Jul-30 | |
| Jul-29 | |
| Jul-22 |
