CPI Card Group's Back-Half PayTech Ramp Faces Its First Real Test As Prepaid Lags
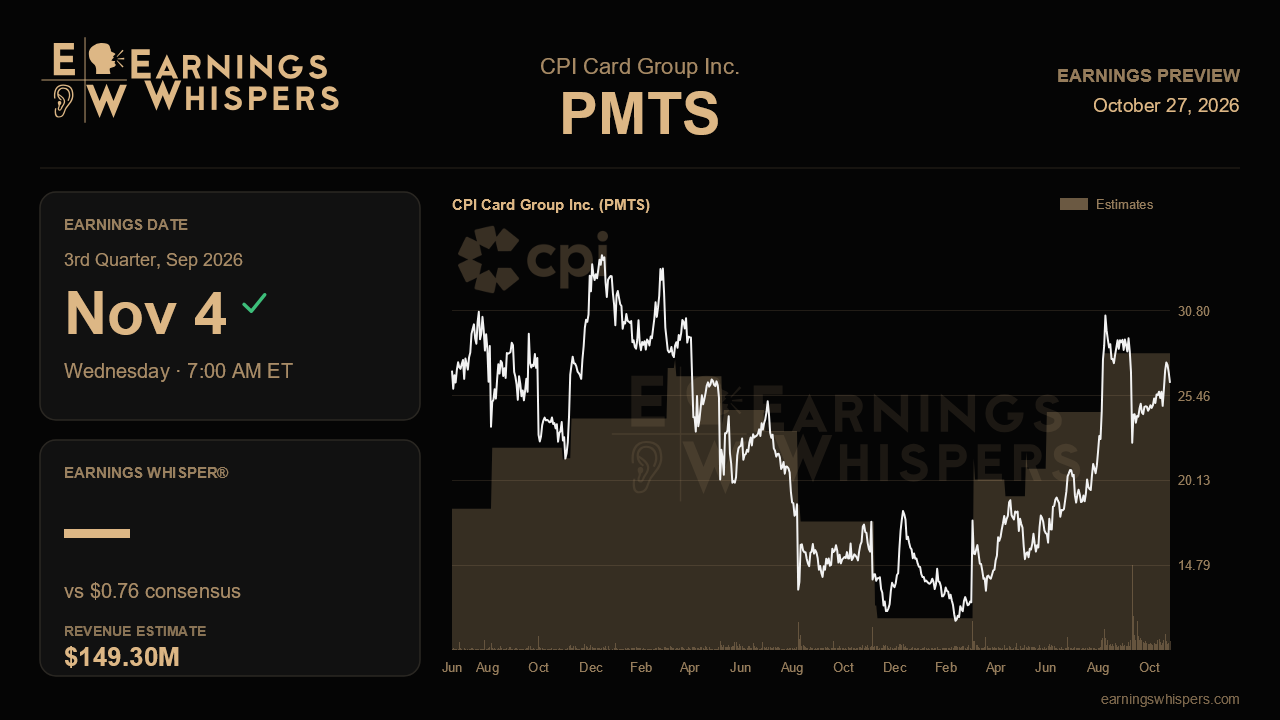
CPI Card Group heads into its third-quarter report with a claim to prove. Last quarter, management raised its revenue and free cash flow targets and lifted its Integrated PayTech growth goal to roughly 20% for 2026. Yet that business grew only 1% to 4% in the first half, and adjusted EBITDA guidance did not budge. The November 4 release, due before the open, is the first quarter in which the promised back-half acceleration has to start showing up in the numbers.
The Street is looking for earnings of $0.76 a share on revenue of $149.3 million. That revenue figure is essentially flat with the $149.2 million posted last quarter and implies 8.2% growth from a year ago. That is a clear step down from the 15% pace in the second quarter and the 20% pace in the first. The earnings estimate is far more ambitious, pointing to about 62% growth from $0.47. Part of that reflects an easier comparison, since the year-ago quarter absorbed roughly $1.6 million of tariff costs that have since turned into refunds. Still, a profit jump of that size sits awkwardly beside an EBITDA outlook that calls for only low-to-mid single-digit growth for the year. That gap makes the bottom line the more fragile part of the setup.
On the top line, expectations look reasonable. Management recently widened its 2026 revenue range to $584.3 million to $611.5 million, and the full-year consensus of $598.5 million sits almost exactly at the midpoint. With roughly $296 million booked in the first half, the Street is effectively modeling a modest rise in the back half. That leaves room for an upside surprise if Secure Card Solutions keeps its momentum. The segment grew 17% last quarter and 25% over the first half, and it remains the clearest engine in the business.
The more telling details will sit beneath the headline numbers. Investors should look for Integrated PayTech growth to inflect sharply, helped by the TRISM instant-issuance acquisition. TRISM closed in late June and is expected to add $3 million to $4 million of second-half revenue at gross margins above 50%. Signs that Card at Once is accelerating, along with early cross-selling into TRISM's network of about 3,000 financial institutions, would support the 20% target. Another quarter of low single-digit PayTech growth would make that goal look like a stretch. Prepaid is the other swing factor. Management shifted its language from expecting full-year growth to warning of choppiness through late 2026. Because prepaid packaging carries the company's richest margins, any further slippage would weigh on gross margin, which benefited from tariff refunds last quarter. Updates on the Carta retail pilot and on prepaid share gains with program managers would add texture.
Cash flow deserves a look too. First-half free cash flow reached a record $36 million, so the raised $45 million to $50 million full-year target requires relatively little from the second half. Confirmation of that range, plus continued progress on leverage from 2.7 times, would reinforce the improving balance sheet story.
The market has already rewarded the narrative. Shares are up about 9% since the last report, roughly 10 points ahead of the S&P 500, and at $26.26 trade well above their 200-day average near $19. The stock remains closer to the middle of its post-earnings range than to the $31.25 high, however, and sentiment is still about as bearish as it was a quarter ago. That mix suggests skepticism has not fully lifted. Ultimately, this report hinges on whether PayTech acceleration and Secure Card strength can outrun prepaid weakness enough to deliver the earnings leap the Street expects. If they cannot, the flat EBITDA guidance will look like the more honest signal.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-21 | |
| Sep-29 | |
| Sep-22 | |
| Sep-14 | |
| Sep-11 | |
| Sep-10 | |
| Aug-26 | |
| Aug-08 | |
| Aug-06 | |
| Jul-23 | |
| Jul-01 | |
| May-05 | |
| Apr-21 | |
| Apr-20 |
