CPI Card Group Misses On EPS As Investment Spending Offsets A Revenue Beat And A Second Straight Guidance Raise
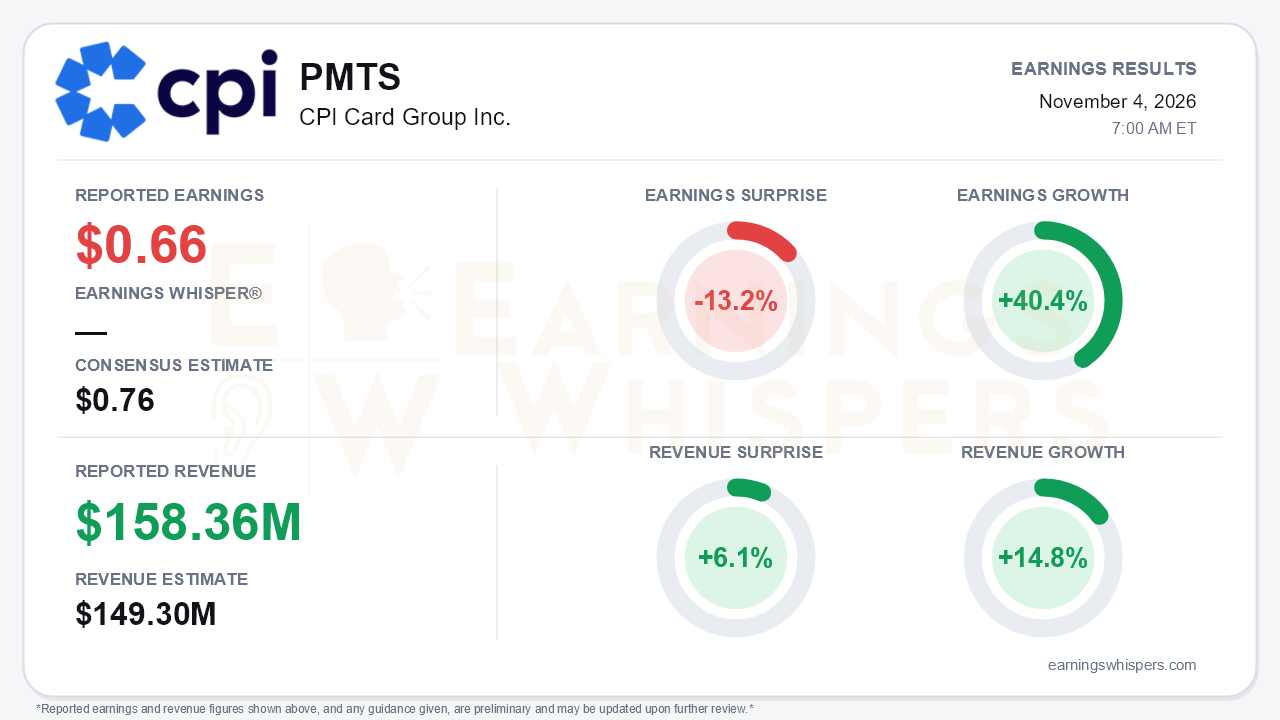
CPI Card Group (NASDAQ: PMTS) delivered a record top line but missed on earnings. The company reported earnings of $0.66 per share, 13.2% below the $0.76 consensus, while revenue of $158.36 million beat the $149.3 million estimate by 6.1%. Growth was still strong: earnings rose 40.4% year over year and revenue grew 14.8%. On a GAAP basis, diluted EPS was $0.41, up from $0.19, and net income more than doubled to $5.0 million. That is the central tension. Demand, mix and cash generation all improved, but CPI is spending heavily enough that the extra revenue is not reaching the bottom line, and the full-year profit outlook did not move.
The revenue quality was good. All three segments grew double digits: Secure Card rose 13% to $111.9 million on contactless volumes, Prepaid rose 15% to $26.9 million, and Integrated Paytech rose 20% to $23.5 million with help from the TRISM acquisition and Card@Once. Gross profit jumped 23% and gross margin widened 200 basis points to 31.7%. Prepaid margin expanded 340 basis points to 34%. The leak came below gross profit. SG&A climbed to $34.6 million from $28.0 million, and corporate operating losses widened to $18.2 million from $14.1 million. That increase included about $1.0 million of costs tied to the secondary offering, higher restructuring charges and nearly double the stock compensation. Integrated Paytech, the high-margin growth engine, grew revenue 20% but saw operating income fall 12%. Its segment operating margin dropped to 30.8% from 42.2%. As a result, Adjusted EBITDA margin improved only modestly, to 17.3% from 17.0%, despite the gross-margin gain.
The call showed sequential momentum that management clearly wanted to highlight:
- Prepaid swung from a 17% decline in the first quarter to 15% growth.
- Integrated Paytech accelerated from 1% and 4% growth in the first two quarters to 20%, and management guided fourth-quarter segment growth to more than double that rate.
- Adjusted EBITDA growth of 17% compared with 9% in Q1 and 7% in Q2.
- Arroweye has now produced more than 30 customer wins, including Navy Federal Credit Union, a top-15 issuer that is new to CPI.
- A BankJoy partnership extends push provisioning to more than 85 community banks and credit unions.
Management's tone was noticeably more confident, with repeated references to record and stronger-than-expected results.
The guidance carries the bears' best argument. CPI raised full-year revenue growth to low double digits, the high end of its prior range, and lifted free cash flow guidance to $50-55 million from $45-50 million. Adjusted EBITDA growth, however, stayed at low-to-mid single digits, unchanged since March. Year-to-date Adjusted EBITDA is already up 11%. Holding that annual range therefore implies a soft fourth quarter, likely below the prior year's level, although management did not frame it that way. Management pointed to three pressures on the fourth quarter:
- Prepaid revenue is expected to normalize to about $20 million from $27 million, creating unfavorable mix.
- Digital and technology investment will continue.
- Part of the Integrated Paytech acceleration rests on an easy comparison with a soft fourth quarter of 2025.
Open-loop prepaid was also described as choppy this year.
Cash flow is the sturdier part of the story, with one caveat. Nine-month free cash flow reached a record $46.1 million versus $6.1 million a year ago. The caveat is that much of that swing came from working capital, including an inventory release that replaced last year's inventory build, and that benefit may not repeat. Even so, CPI has repaid debt: senior notes fell to $238.5 million from $265 million, and net leverage dropped to 2.6x from 3.1x at year-end. Management also flagged a refinancing of the 10% notes once the call premium steps down in July 2027. That is a tangible future earnings lever, given roughly $8 million of quarterly interest expense. The completed exit of Parallel49 removes a long-standing ownership overhang and widens the float.
The market setup is more complicated than the surprise figures suggest. Shares surged after the August report to a 52-week high of $31.25 on August 11, then gave back most of that move. Ahead of this release they traded at $24.69, 21% below the high and only 2.9% above the post-August opening price. The stock still sits about 26% above its 200-day moving average, and the Earnings Whispers trend readings are mostly positive, with sequential growth, momentum and AVWAP all favorable. Investor sentiment, however, remained negative and slipped slightly, from -0.33 to -0.36. Investors appear to accept the revenue story but remain unconvinced about profit conversion.
The bottom line is that CPI's quarter strengthened the growth and balance-sheet case while sharpening the margin question. Broad-based demand, new issuer wins, deleveraging and a second guidance raise show a business gaining share. However, the EPS miss, rising SG&A and an EBITDA outlook that implies a weaker fourth quarter mean investors are being asked to fund growth before seeing operating leverage. Whether 2027 brings that payoff, aided by a cheaper refinancing, is now the key question.
Read our earnings preview for CPI Card Group Inc.: https://www.earningswhispers.com/article/PMTS/21729
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 5 hours | |
| 15 hours | |
| Oct-27 | |
| Oct-21 | |
| Sep-29 | |
| Sep-22 | |
| Sep-14 | |
| Sep-11 | |
| Sep-10 | |
| Aug-26 | |
| Aug-08 | |
| Aug-06 | |
| Jul-23 | |
| Jul-01 | |
| May-05 |
