SelectQuote's Shrink-To-Profit Pivot Faces First Test As Stock Sinks Toward 30 Cents
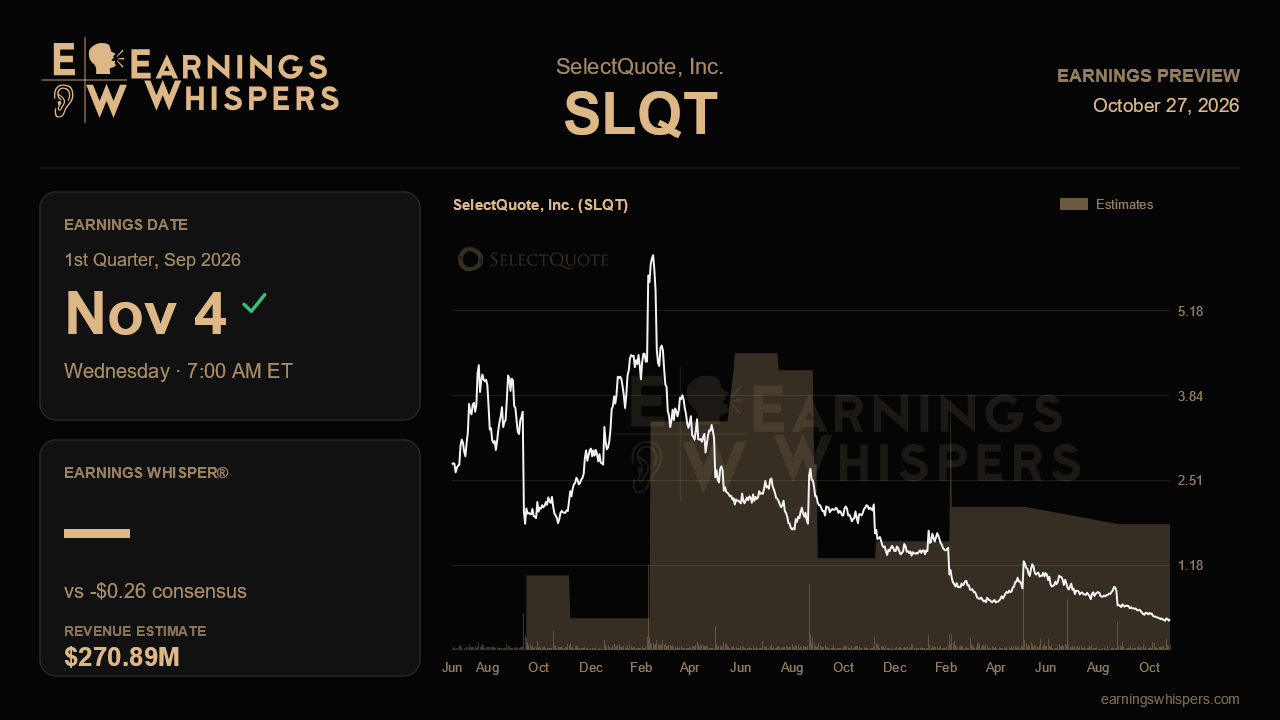
SelectQuote told investors three months ago that it would get smaller on purpose. It planned fewer Medicare Advantage policies, a lighter pharmacy top line and a leaner cost base, all in exchange for roughly doubling operating cash flow. The market's verdict has been brutal. Shares have fallen about half since that report while the S&P 500 was essentially flat, leaving the stock near $0.33. The fiscal first-quarter release, due before the open on November 4, is the first chance to show the contraction is the controlled kind management described rather than the start of something worse.
The Street expects a loss of $0.26 per share, identical to the year-ago result, on revenue of about $270.9 million. That would be a 17.6% drop from $328.8 million a year earlier and a steep step down from the $321.7 million posted last quarter. A flat loss on sharply lower sales is the real test. If the company holds the loss steady while revenue falls by nearly a fifth, it would suggest the identified efficiency savings, which management put at more than $30 million on an annualized run-rate basis, are already working. A wider loss would raise doubts about whether costs can come down as fast as revenue.
Guidance frames everything. Management called for fiscal 2027 revenue of $1.35 billion to $1.45 billion, roughly 14% below fiscal 2026 at the midpoint. It also guided adjusted EBITDA to $90 million to $115 million, against the $109 million just delivered. The quarterly consensus appears to reflect that reset, but the full-year revenue consensus of about $1.74 billion sits far above the top of the company's range. That gap suggests some annual estimates have not caught up. Downward revisions could keep pressure on the shares even if the quarter lands as expected. An unusually soft first half also fits management's warning that IRA wraparound effects would make early-year healthcare services comparisons especially noisy.
Operationally, healthcare services is the segment to dissect. It became the company's largest business last year at $845 million in revenue and exited the year at roughly a $50 million annualized EBITDA run rate. Management expects segment revenue to fall 10% to 15% this year while margins roughly double. That promise rests on the Olathe, Kansas facility, said to deliver about 30% shipment efficiency gains, and a newly deployed pharmacy management system. Evidence that segment profitability is holding near that exit rate despite lower revenue would validate the thesis. Slippage would undercut the central argument for the shrink. On the senior side, investors want confirmation that the planned 10% to 15% decline in approved Medicare Advantage policies is a choice rather than a symptom of carrier pullback. Commentary on the key carrier that cut its marketing investment, and on early enrollment-season trends, will matter.
Cash is the other pillar. Management issued its first-ever cash flow targets, calling for operating cash flow of $60 million or more and free cash flow near $50 million. The September quarter is seasonally light, so one period cannot prove the full-year figure. Still, signs of progress, along with any update on lowering the roughly 12% cost of about $800 million in debt and preferred equity, would carry weight. Management estimates each percentage point of rate relief is worth about $8 million a year.
Sentiment has cooled from modestly bullish ahead of the last report to slightly bearish now. The stock trades far below its 200-day average of $0.81, near the bottom of its post-earnings range of $0.30 to $0.68. That range sits wholly beneath the prior quarter's band of $0.64 to $1.39. Expectations are low, but the market has stopped giving management the benefit of the doubt. The question is whether SelectQuote can show that shrinking revenue is buying better margins and real cash. If it can, the deliberate pullback starts to look like strategy. If it cannot, it looks like retreat.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-14 | |
| Aug-25 | |
| Aug-25 | |
| Aug-25 | |
| Aug-11 | |
| May-14 | |
| May-05 | |
| May-05 | |
| Apr-21 | |
| Mar-25 | |
| Mar-17 | |
| Feb-26 | |
| Feb-25 | |
| Feb-09 |
