SelectQuote Beats On Margin Repair, But Shrinking Revenue And A Reverse-Split Vote Keep The Pressure On
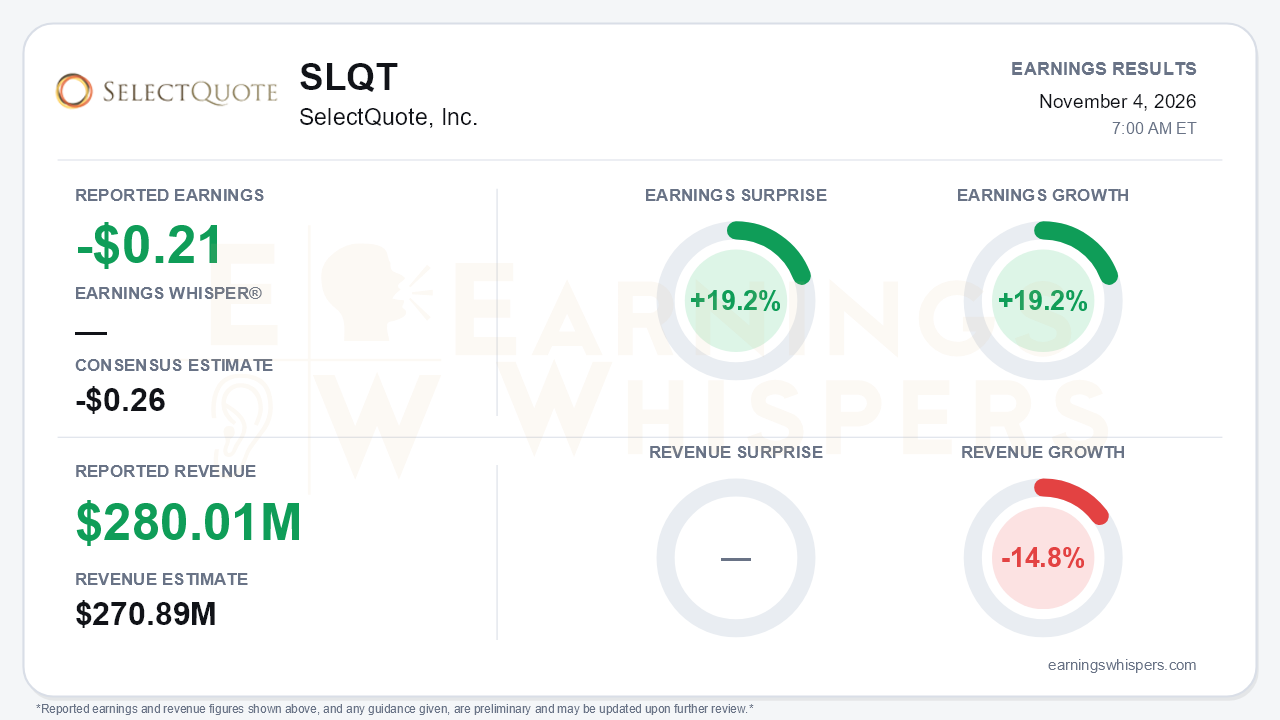
SelectQuote (NYSE: SLQT) delivered another quarter that looks better on profitability than on growth. The fiscal first-quarter loss of $0.21 per share beat the consensus estimate of a $0.26 loss by 19.2% and improved 19.2% from a year ago. Revenue of $280.01 million topped the $270.89 million consensus by 3.4%, but it fell 14.8% from the prior year. That is the central tension. Management is getting markedly more profit out of a business that keeps getting smaller, and the stock trades below $1 ahead of a reverse-split vote. The market is no longer asking whether SelectQuote can cut its way to better margins. It is asking whether the operating gains can outrun the balance-sheet and listing pressures.
The operating improvement is real. Adjusted EBITDA improved to a $17.0 million loss from a $32.1 million loss, and trailing twelve-month adjusted EBITDA rose 30% to $124 million. Even so, the quality of the beat deserves some scrutiny. The GAAP net loss narrowed to $20.3 million from $30.5 million, but a $12.6 million non-cash gain on warrant revaluation cushioned that figure. Per-share results also absorb a growing preferred-stock burden. Accumulated preferred dividends and accretion rose to $20.2 million, so the net loss attributable to common shareholders was $40.5 million. The preferred liquidation preference climbed to $438.6 million from $423.2 million in a single quarter. Operating cash burn improved to $17.2 million from $21.6 million. However, the company drew a net $21 million on its revolver, long-term debt rose to $364 million, and quarter-end cash was only about $13 million to $14 million.
Beneath the consolidated numbers, every segment showed the same pattern: lower volume and better unit economics. In Senior, revenue fell 14% and approved Medicare Advantage policies dropped 18%, reflecting a deliberately smaller agent force. Even so, the segment's EBITDA loss narrowed by $9 million, and MA lifetime value per policy rose 16% to $890. Healthcare Services revenue fell 16% to $186.3 million, pressured by the Inflation Reduction Act and tighter customer qualification. SelectRx membership declined 7% to 99,753, and prescriptions per day slipped to 28,139. Yet segment EBITDA jumped 56% to $11.2 million, and profit per member climbed from $67.1 to $107.6. Life EBITDA rose 31% with a 17% margin, even though final expense premiums fell 32%. Compared with revenue growth of 12% and 6% in the two quarters before last, the top-line deceleration is stark. The FY27 revenue guide of $1.35 billion to $1.45 billion implies the shrinkage persists all year.
What changed most on the call was tone. Management's description of the Medicare Advantage backdrop has moved from "cautious optimism" to "green shoots" and now to an "inflection point." Management said carriers are tracking ahead of profitability targets and commissions are more stable. It also suggested that strong early AEP engagement could curb the guided 10% to 15% decline in MA policies, and it aims to beat last year's roughly 30% recapture rate. AI has become more concrete as well. Management said an AI enrollment agent is deployed in AEP and that voice AI screened more than 200,000 calls in the quarter, saving over 600,000 agent minutes. It also reiterated $30 million-plus in run-rate cost savings and described a path to paying the preferred dividend in cash. The full-year adjusted EBITDA guide of $90 million to $115 million and the $60 million-plus operating cash flow target were reaffirmed, not raised.
Bears still have legitimate ammunition. The reverse stock split proposed for the November 10 annual meeting is a reminder that listing compliance remains unresolved. Further IRA drug-pricing tranches in 2027 and 2028 will delay clean pharmacy comparisons. The smaller agent force caps Senior volume upside. And because fiscal Q2 is the peak cash-investment quarter, the operating cash flow target is weighted toward the back half of the year. Investors are being asked to take that target partly on faith.
The market has been unforgiving. Shares fell from a $0.65 open after the August report to $0.41 heading into this release, a 36.9% decline. The stock sits nearly 47% below its 200-day moving average of $0.77. It hit a 52-week low of $0.30 on October 26 before rebounding about 37% off that level. Investor sentiment remained positive but weakened, slipping from 0.157 to 0.106. The Earnings Whispers price, sequential growth and AVWAP trends remain negative, and momentum is neutral.
The bottom line is that SelectQuote beat expectations and showed that its margin repair is working across all three segments. Management also struck its most constructive Medicare Advantage tone in several quarters. But revenue is shrinking at a mid-teens pace, the preferred stock keeps compounding, liquidity is thin, and the reverse split underscores how much equity value has eroded. The fundamental story improved this quarter. The setup only changes meaningfully if AEP volumes and back-half cash generation deliver on management's more optimistic framing.
Read our earnings preview for SelectQuote, Inc.: https://www.earningswhispers.com/article/SLQT/21740
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Oct-27 | |
| Oct-14 | |
| Aug-25 | |
| Aug-25 | |
| Aug-25 | |
| Aug-11 | |
| May-14 | |
| May-05 | |
| May-05 | |
| Apr-21 | |
| Mar-25 | |
| Mar-17 |
