Shoals Faces A Cash And Conversion Test As Record Backlog Meets A Sliding Stock
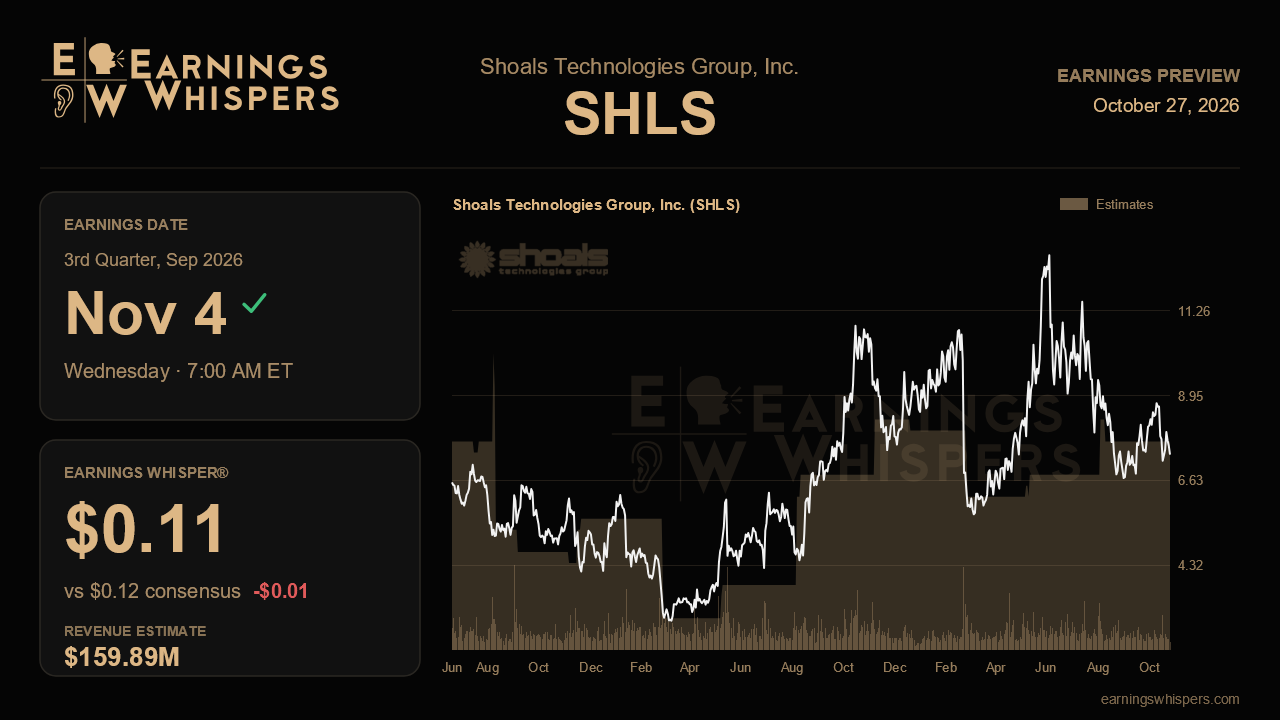
Shoals Technologies enters its third-quarter report with an awkward split screen. On one side sits a record $801.4 million backlog, a 1.3 book-to-bill and gross margins climbing off their first-quarter trough. On the other sits a stock down 19% since the last report, rising net debt and a management team that declined to raise its full-year outlook despite all that order momentum. The November 4 release, due before the open, needs to show that the backlog is turning into revenue, margin and eventually cash, rather than just piling up on the balance sheet.
The Street is looking for earnings of $0.12 a share on revenue of about $159.9 million. The Earnings Whisper sits a penny lower at $0.11, a small gap but one that hints at modest caution rather than a crowd leaning toward an upside surprise. The revenue estimate lands almost exactly at the midpoint of management's $150 million to $170 million guidance, so analysts are taking the company at its word without stretching. That figure would mean roughly 18% growth from the year-ago $135.8 million. Healthy, but a clear slowdown from the 47% pace of the second quarter and a slight sequential dip from $163.4 million. Some of that deceleration reflects tougher comparisons, yet it also fits management's warning that the time between booking and shipping is lengthening, with some orders now stretching into early 2027.
The full-year frame matters here. Shoals raised its 2026 outlook on the first-quarter call to $600 million to $640 million in revenue and $118 million to $132 million in adjusted EBITDA, then simply reaffirmed it last quarter, citing production capacity limits. With roughly $304 million booked in the first half, a midpoint third quarter implies a fourth quarter in the mid-$150 millions, consistent with the step-down management flagged on fewer production days and battery storage timing. A beat this quarter is useful, but a credible case that the business can push toward the top of the annual range would carry more weight. Another flat reaffirmation would likely read as a capacity ceiling rather than conservatism.
Margins are the second pillar. Management framed the first quarter as the low point, and adjusted gross margin improved to 30.6% in the second. A further step up toward the low-to-mid 30s range the company now considers normal would validate that call; a stall near 30% would suggest the structural reset is biting harder than hoped. Battery storage also deserves scrutiny. That backlog fell to $65 million as $20 million of revenue tied to the On Energy data center ramp outpaced roughly $10 million of new orders. Fresh storage bookings would show the AI data center opportunity is repeatable rather than a single large project.
The balance sheet may be what the stock is really reacting to. Net debt rose to $181.1 million, cash fell to $15.7 million and the revolver was temporarily expanded by $50 million to fund inventory. Evidence that working capital is beginning to release cash would go a long way toward easing those concerns. Updates on the TerraFlow storage agreement, the Airlink data center product and the damages phase of the ITC case against Voltage are longer-dated, but they help define what the next growth leg looks like.
Sentiment is essentially unchanged from last quarter, mildly positive, while the shares at $7.34 trade well below their 200-day average of $8.51 and closer to the $6.61 post-earnings low than the $9.64 high. That leaves a low bar emotionally but little patience for balance sheet surprises. The core question is whether Shoals can convert a record backlog into margin expansion and cash generation. If it can, the selloff looks overdone; if inventory and debt keep climbing alongside slowing growth, the market's skepticism will look justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-19 | |
| Oct-13 | |
| Oct-05 | |
| Aug-26 | |
| Aug-18 | |
| Aug-04 | |
| Aug-04 | |
| Aug-04 | |
| Aug-03 | |
| Aug-03 | |
| Jul-30 | |
| Jul-08 | |
| Jun-25 | |
| May-19 |
