Shoals Crushes Q3 Estimates And Raises 2026 Outlook, But The Array Merger Now Defines The Investment Case
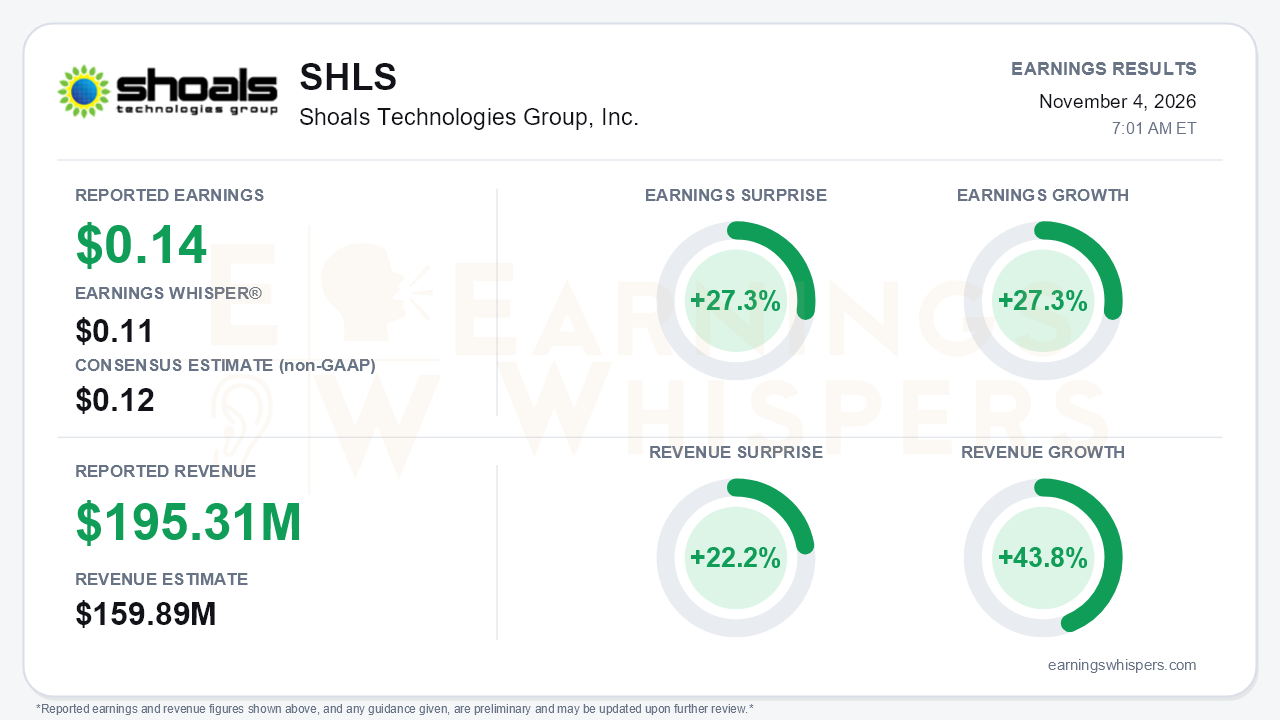
Shoals Technologies Group delivered its strongest quarter in some time, then announced a deal that changes what shareholders own. Third-quarter adjusted EPS of $0.14 beat the $0.12 consensus by 27.3% and cleared the $0.11 Earnings Whisper number. Earnings grew 27.3% year over year. Record revenue of $195.3 million rose 43.8%, topped the $159.89 million consensus by 22.2%, and landed far above management's own $150-170 million guide. On its own, that is a clean beat-and-raise. But Shoals released the numbers alongside a stock-for-stock merger with ARRAY Technologies, and that is the central tension: the standalone business is improving just as investors are asked to price a larger, more leveraged, lower-margin combined company.
The quality of the quarter is better than the year-over-year margin comparison suggests. Gross margin of 31.9% remains well below last year's 37.0%. The release attributes the gap to inefficiencies from the move into the new manufacturing facility, product mix, rework and corrective actions on product quality, and lease amortization. The sequential trend is what matters, though. Margin has climbed from 29.6% in Q1, which management called the trough, to 30.6% in Q2 and now 31.9%. Adjusted EBITDA reached $39.8 million, a 20.4% margin, against a $32-37 million guide, up from $31.6 million in Q2 and $21.1 million in Q1. GAAP results also improved, with net income of $17.9 million, or $0.11 per share, versus $0.07 a year ago, helped by a sharp drop in wire-shrinkback litigation spending.
Cash flow was the other turn. Operating cash flow of $28.9 million, after -$41.4 million in Q1 and $6.8 million in Q2, funded a $33 million revolver paydown. Year to date, however, operating cash flow is still negative at $5.8 million. Inventory has risen to $148 million from $90 million at year-end, and cash sits at just $7.7 million against $163.75 million drawn on the revolver. Shoals raised its full-year outlook to revenue of $665-685 million and adjusted EBITDA of $129-133 million, from $600-640 million and $118-132 million. It also guided to $55-65 million of operating cash flow, which implies a large fourth-quarter cash conversion. The Q4 revenue guide of $165-185 million points to a sequential step down from Q3's record. The raise appeared in the release, but the call did not discuss standalone guidance in any depth.
Bears have legitimate ammunition on demand. Bookings of $186 million, the third highest on record, fell from $207 million in Q2, and book-to-bill slipped to about 1.0 from 1.3. Backlog and awarded orders of $791.7 million were up 9.8% year over year but down 1.2% sequentially. Management still struck a markedly more confident tone and reiterated its "stronger for longer" view of a high-30s to low-40s GW U.S. market. Even so, the order book is no longer expanding as fast as revenue.
The Array deal reshapes the setup. Each Shoals share converts into 1.6931 ARRY shares, leaving Shoals holders with roughly 65% of the combined company and Brandon Moss as CEO. Closing is expected in Q1 2027. Management outlined:
- synergies of $35 million in year one and more than $100 million of incremental EBITDA by year three, about two-thirds commercial;
- a preliminary combined 2027 outlook of $2.2-2.4 billion in revenue and $410-480 million in adjusted EBITDA;
- roughly $3.4 billion of combined backlog;
- an estimated $2.5 billion cross-sell opportunity;
- Shoals' sizable tax assets, which could reduce combined cash taxes.
The costs are real as well. Pro forma 2026 leverage is 2.6x net debt to EBITDA versus Shoals' standalone 1.6x, and pro forma cash is only about $30 million. The combined company also inherits at least $317.6 million of Array preferred redemptions over roughly three years. Array's roughly 10% EBITDA margin dilutes Shoals' roughly 20%. Finally, the deal reverses the tracker-agnostic positioning Shoals emphasized just one quarter ago, which raises channel-conflict risk with other tracker partners.
Investors entered the report cautious. Earnings Whispers sentiment remained positive but weakened modestly, from 0.24 to 0.19. Shares closed at $8.47 before the release, down 6.4% from the $9.05 open after the August report and sitting almost exactly on the 200-day moving average of $8.46. The stock has recovered 28% from its September low of $6.61 but remains 12% below the $9.64 quarterly high set right after the last report. Price and AVWAP trend readings remain negative.
The bottom line is that Shoals proved its operational recovery is real: margins, cash flow and revenue all moved decisively in the right direction. Cooling bookings and a thin balance sheet temper that progress. Because of the Array merger, the stock now trades less on Shoals' quarterly execution and more on integration, leverage and synergy delivery.
Read our earnings preview for Shoals Technologies Group, Inc.: https://www.earningswhispers.com/article/SHLS/21739
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 46 min | |
| Nov-04 |
Array Technologies to merge with Shoals in $1 billion deal, combining solar suppliers
SHLS +8.15%
Albuquerque Journal, N.M.
|
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Oct-27 | |
| Oct-19 | |
| Oct-13 | |
| Oct-05 | |
| Aug-26 | |
| Aug-18 | |
| Aug-04 | |
| Aug-04 | |
| Aug-04 |
